
Tradeweb’s Growth Trajectory: Platform Expansion, Credit Market Gains, and Integrating Trumid
Tradeweb’s strong Q3 2026 earnings, a $1.97B Trumid acquisition, and global multi-asset scale set the stage for a strategic test: can the company sustain margin expansion and defend its competitive advantages as the pace of electronification accelerates and integration complexity rises?
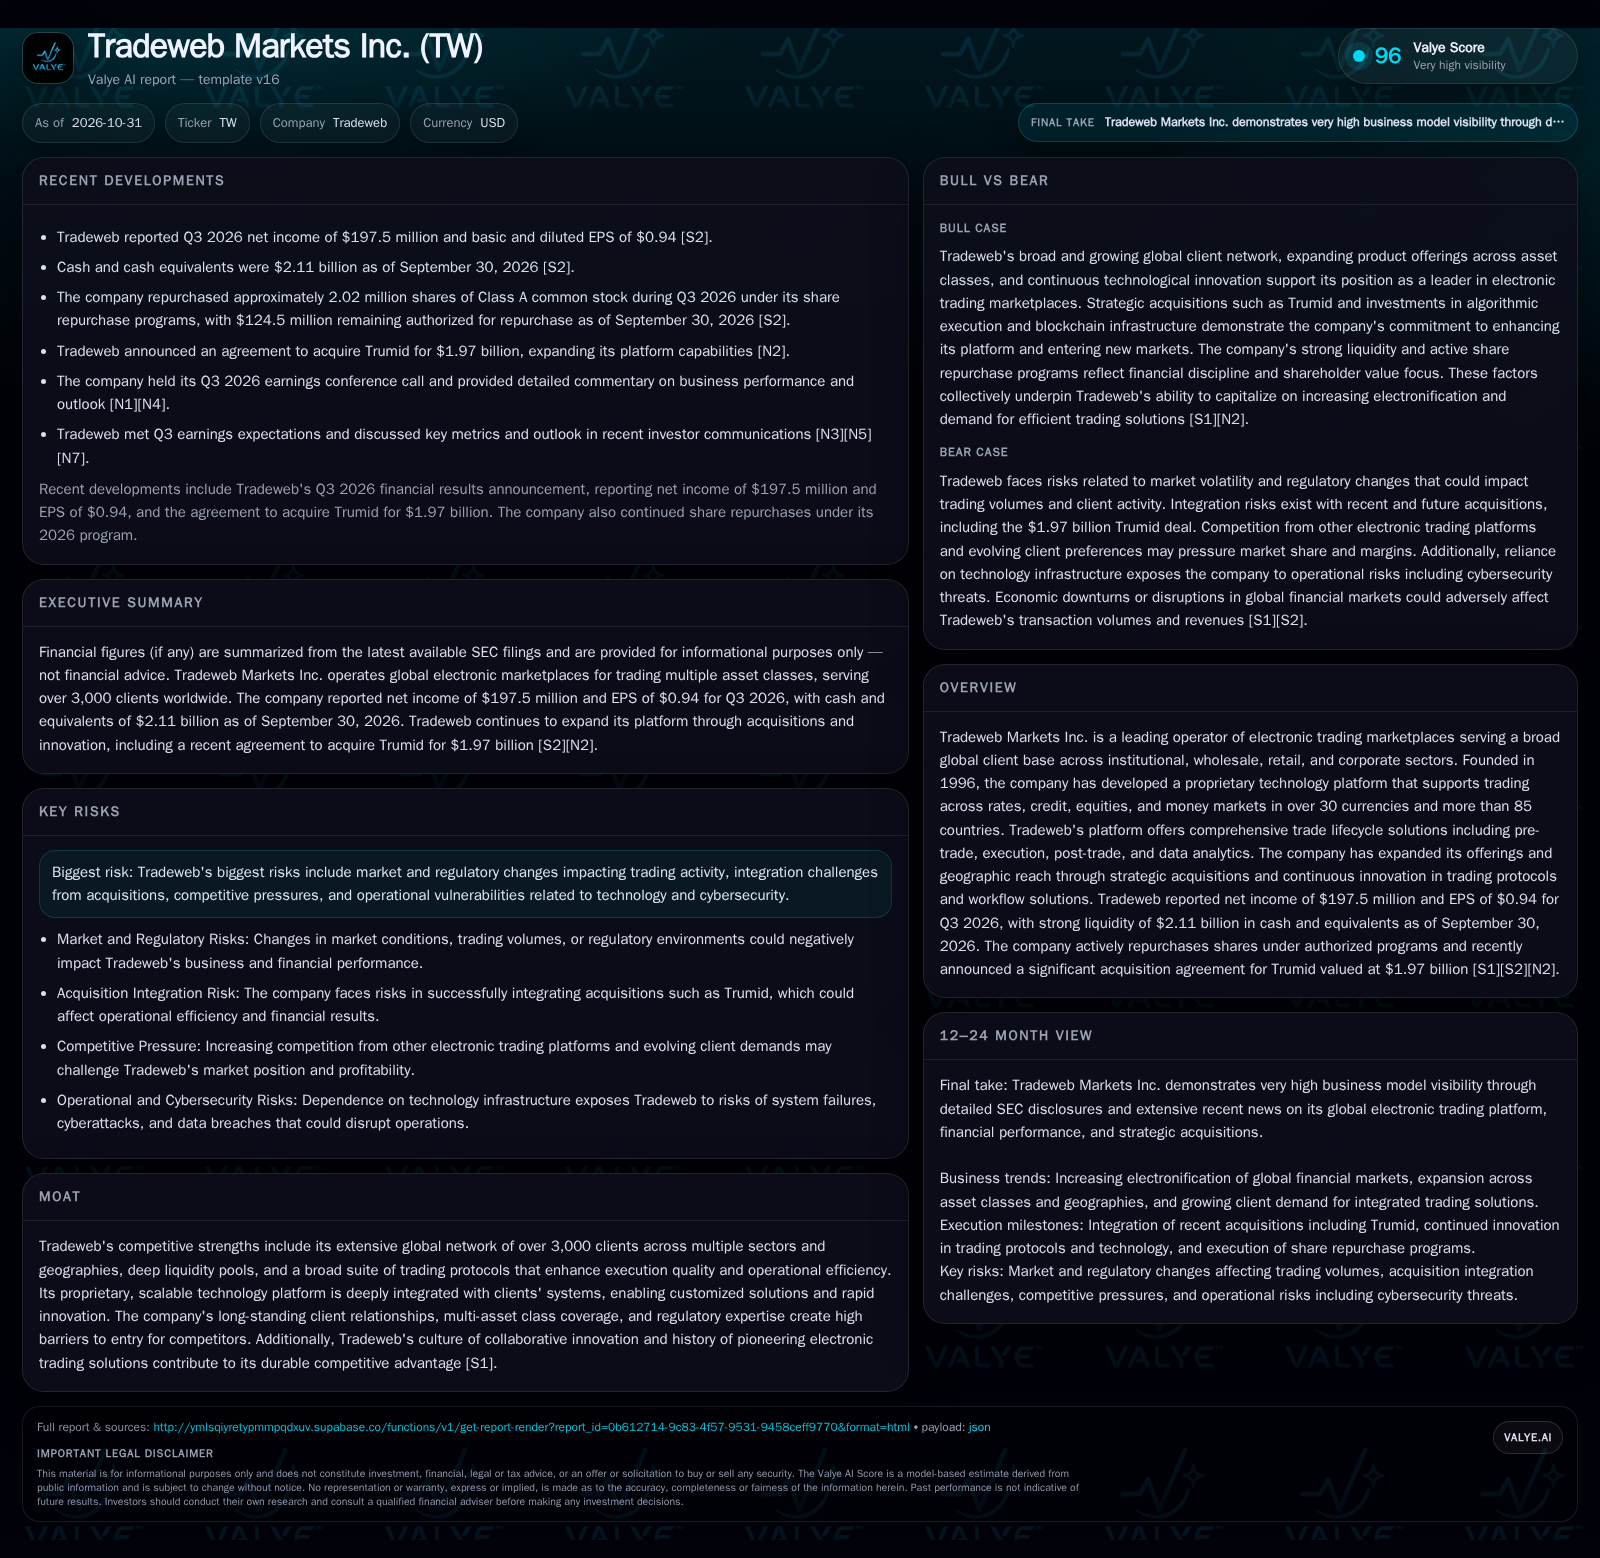
Tradeweb delivered $197.5M in Q3 2026 net income and agreed to acquire Trumid for $1.97B, further consolidating its position as a leading global electronic trading platform. Its average daily volume topped $2.6T in 2025, with credit revenues reaching $488M, reflecting strong franchise momentum. The challenge is whether Tradeweb can integrate new assets, maintain innovation, and defend margins as competition and client sophistication increase. [S1] [S2] [N2]
Tradeweb Markets Inc. stands at a pivotal moment in the evolution of global electronic trading. With Q3 2026 net income of $197.5 million, $2.11 billion in cash, and a new $1.97 billion agreement to acquire Trumid, Tradeweb is doubling down on its multi-asset, multi-protocol strategy. The company’s continued expansion into credit and corporate bond trading—and its ability to integrate new capabilities while keeping margins resilient—will shape its competitive trajectory as electronification reshapes institutional finance. The question is whether Tradeweb can sustain its innovation edge and platform scale as industry complexity and client demands rise. [S1] [S2] [N2]
Tradeweb’s 2026 Outlook: Strategic Initiatives and Financial Highlights
Tradeweb Markets reported net income of $197.5 million for Q3 2026, with basic and diluted EPS of $0.94, and cash and cash equivalents of $2.11 billion as of September 30, 2026. In October 2026, the company announced an agreement to acquire Trumid for $1.97 billion, a move that expands its credit and corporate bond trading capabilities. Tradeweb’s platform supported an average daily trading volume of $2.6 trillion in 2025, up sharply from $0.8 trillion in 2020, demonstrating substantial scale and adoption. Revenues from the credit asset class reached $488 million in 2025, reflecting successful diversification beyond rates and government bonds. These facts underscore Tradeweb’s ongoing shift toward broader asset class coverage, deeper liquidity pools, and more robust technology integration. [S1] [S2] [N2]
Scale, Platform Diversity, and Workflow Integration as Economic Drivers
Tradeweb’s business model centers on transaction-based fees, recurring platform access charges, and data and analytics revenue streams. As trade volumes climb—supported by a broader client base and new asset classes—operating leverage may improve, since the platform’s cost base is heavily weighted toward technology, compliance, and infrastructure rather than incremental transaction costs. The proprietary, scalable architecture allows Tradeweb to accommodate additional trading protocols, asset classes, and geographies with limited incremental expense, giving the company margin-expansion potential as volumes rise.
Acquisitions such as Trumid could further diversify revenue by deepening penetration into corporate credit, a segment where electronification remains less mature than rates or government bonds. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S1] [S2] [N2]
The economics of electronic trading platforms also depend on pricing power, which is shaped by liquidity depth, network effects, and regulatory compliance. Tradeweb’s ability to command premium fees or defend take rates may come under pressure if competitors narrow the technology or liquidity gap, or if clients demand greater price transparency and lower costs as electronification matures.
Maintaining Competitive Advantage Through Network Effects and Deeper Integration
Tradeweb’s moat rests on a combination of global network breadth (serving over 3,000 clients in 85+ countries), deep liquidity pools across rates, credit, and more, and its proprietary platform’s integration with client order, risk, and accounting systems. The company’s multi-protocol capability—including RFQ, CLOB, portfolio trading, and automated execution—enables it to address diverse client workflows and regulatory environments, which can be hard for new entrants to replicate at scale. [S1]
However, the electronic trading landscape is fiercely competitive, with peer platforms and major market infrastructure providers investing aggressively in technology, analytics, and client connectivity. The pace of electronification in credit and less-liquid asset classes is accelerating, attracting new entrants and prompting established players to expand product breadth. The risk is that as more venues achieve critical mass, liquidity may fragment and pricing could become more competitive, eroding incumbent advantages.
Switching costs for large institutions can be significant given workflow integration, compliance, and historical data, but are not insurmountable if alternative platforms offer superior execution or economics. Tradeweb’s ability to maintain its network effects and fend off disintermediation will depend on continued innovation, client engagement, and post-acquisition execution.
Successful Integration Could Accelerate Credit Market Share and Boost Margins
In a favorable scenario, Tradeweb’s acquisition of Trumid catalyzes rapid growth in electronic corporate bond trading. The combined platform leverages Tradeweb’s global reach and workflow integration with Trumid’s technology and client relationships, accelerating the shift from voice to electronic trading in credit. Successful integration would enable cross-selling, data product expansion, and deeper penetration into buy-side and dealer workflows.
If Tradeweb continues to deliver industry-first innovations—such as expanded algorithmic execution and new trading protocols—while maintaining high platform uptime and regulatory compliance, it could reinforce its pricing power and expand margins. Evidence for this scenario would include outsized growth in credit trading volumes, above-peer margin expansion, rapid realization of acquisition synergies, and sustained high client retention rates post-integration. Confirmation would also come from new product launches and notable client wins in credit and emerging markets.
Platform Expansion Continues Despite Competitive and Integration Challenges
The most plausible scenario is that Tradeweb sustains moderate growth in trading volumes and revenues across its core asset classes, with incremental market share gains in credit following the Trumid integration. Integration costs and client migration challenges may temper short-term margin expansion, but the company’s scale, brand, and breadth enable it to weather competitive pricing and occasional market volatility. Innovation continues, but at a measured pace, as resources are partially absorbed by integration and platform harmonization.
Evidence supporting this outcome would be steady increases in average daily trading volume, stable or modestly rising margins, and continued expansion of the client base—particularly in emerging markets and new asset classes. Any delays or setbacks in integrating Trumid would likely be modest and not thesis-altering, provided client retention and cross-sell rates remain healthy. Confirmation would come from quarterly disclosures of credit volume growth, margin trends, and client engagement metrics, if disclosed.
Potential Setbacks from Integration Issues, Margin Compression, and Liquidity Shifts
A less favorable scenario would see Tradeweb struggling to integrate Trumid, with technology or cultural misalignment leading to operational disruptions, client attrition, or delayed product rollouts. If competitors capitalize on the distraction—offering lower-cost alternatives or more advanced analytics—Tradeweb could face margin compression and loss of market share, especially in credit trading where electronification is still maturing.
Liquidity fragmentation across platforms could further dilute Tradeweb’s network effects, while regulatory changes or macro shocks might reduce trading volumes and client risk appetite. Evidence for this scenario would include declining credit trading volumes, margin contraction, integration-related write-downs or impairments, and publicized client defections. Additional warning signs would be negative commentary in earnings calls regarding integration challenges or competitive losses.
Factors Influencing Tradeweb’s Ability to Sustain Platform Expansion Benefits
Quarterly trends in average daily trading volume by asset class—especially credit and corporate bonds—would help test the impact of the Trumid acquisition and Tradeweb’s ability to drive electronification.
Margin trajectory (gross and operating) post-acquisition, as a sign of integration effectiveness and platform operating leverage.
Client retention and cross-sell rates in the wake of the Trumid integration, particularly among key buy-side and dealer clients.
Pace and outcome of new trading protocol and analytics product launches, including adoption rates and client feedback.
Frequency and scale of technology or operational disruptions, especially during the integration period.
Expansion of client count and geographic reach, with particular attention to growth in emerging markets and new asset classes.
Evidence of regulatory or market structure changes that could impact trading volumes, platform economics, or compliance costs.
Public commentary from management and major clients on integration progress, competitive positioning, and strategic priorities.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments