
Envista Holdings in 2026: Innovation-Led Recovery, Segment Dynamics, and the Stakes of Dental Market Competition
Envista’s 2025 rebound features stable margins, accelerating sales from clear aligners and specialty products, and a renewed focus on R&D—but questions remain about the durability of growth, competitive pressures, and integration of acquisitions as the dental technology landscape evolves.
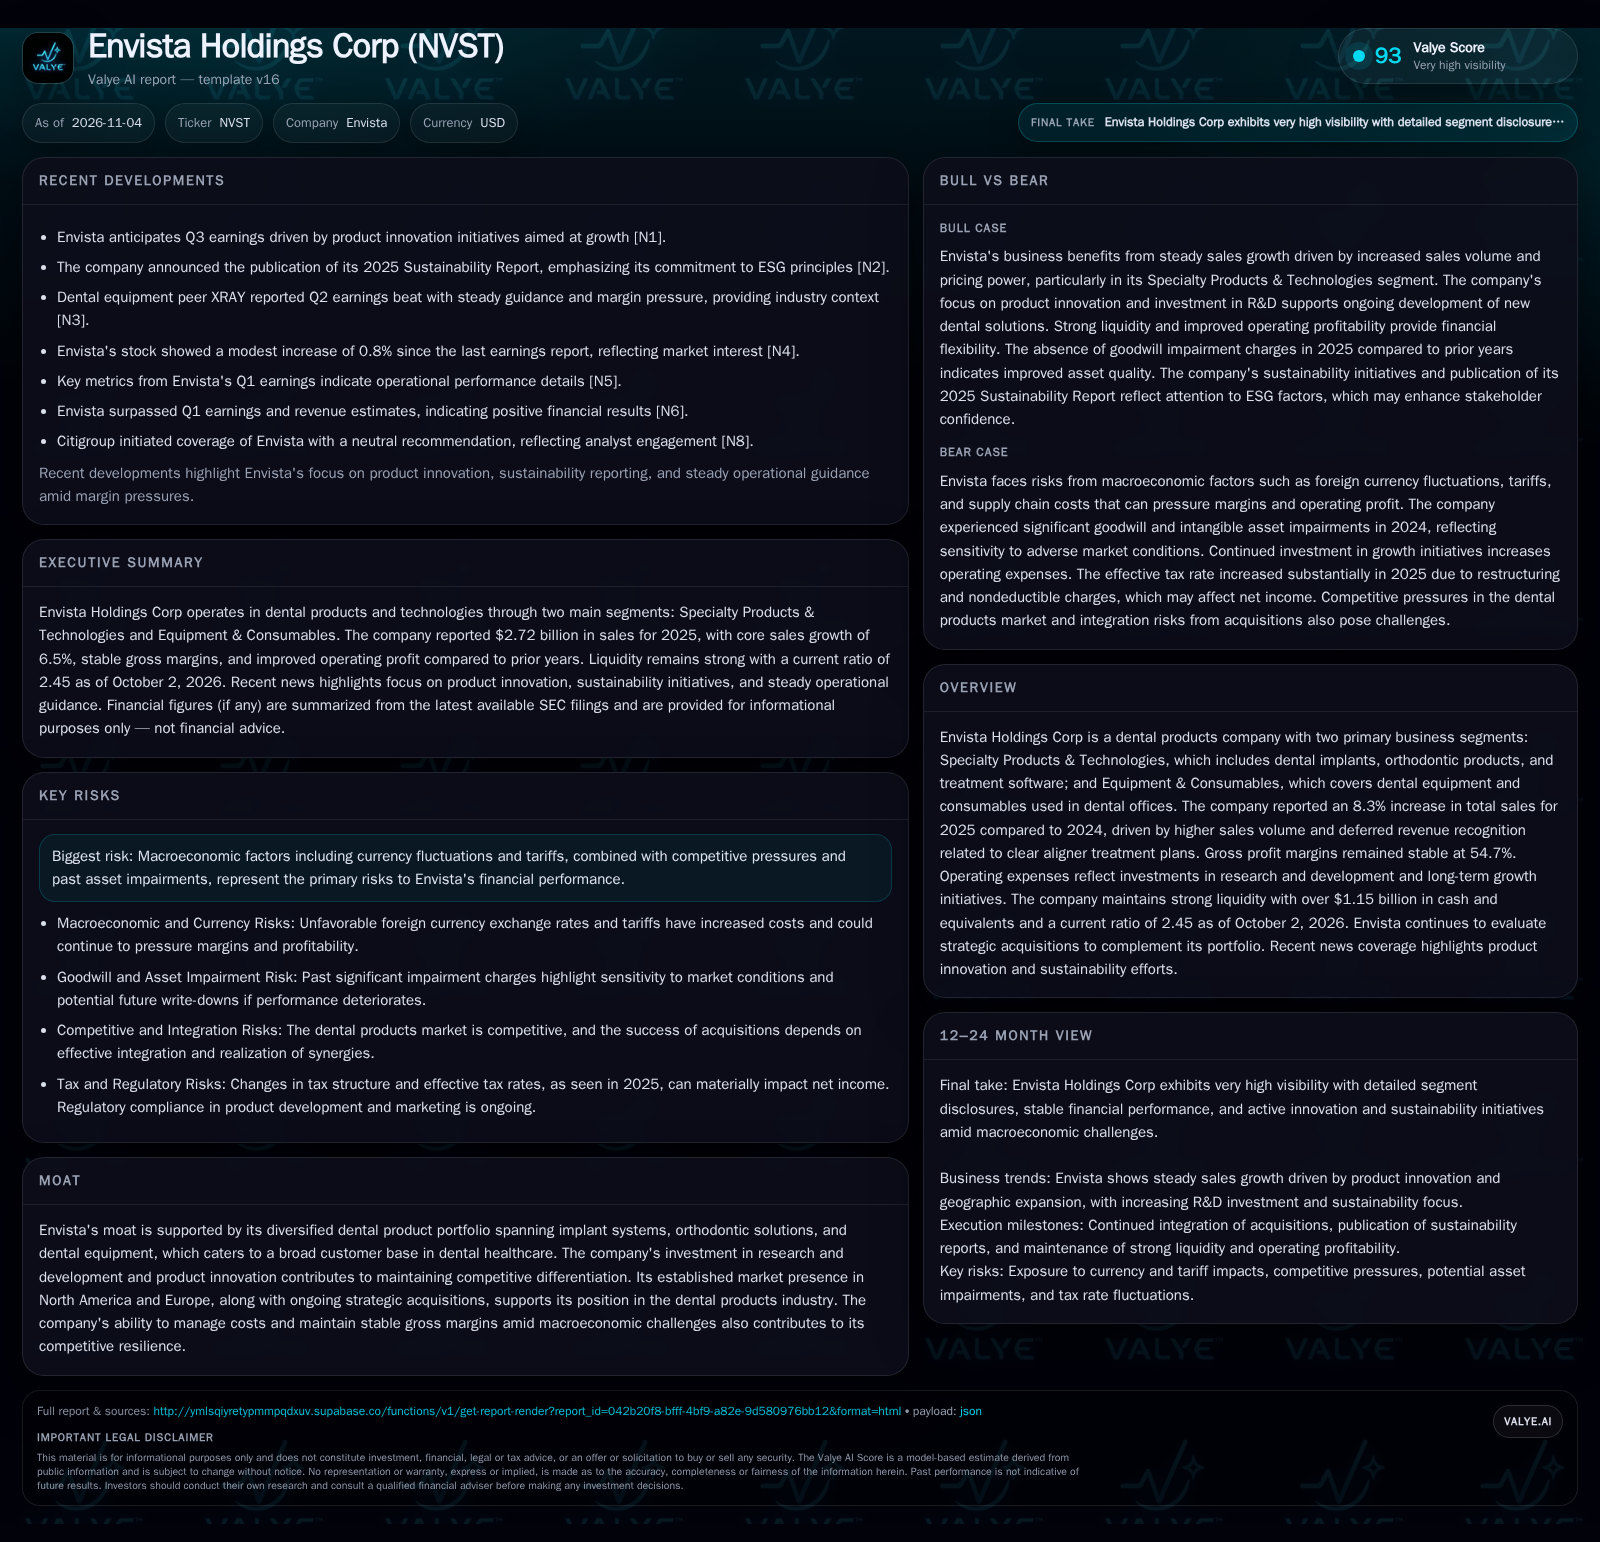
Envista Holdings posted an 8.3% sales increase to $2.72B in 2025, driven partly by deferred clear aligner revenue, with gross margins steady at 54.7%. Operating profit rebounded after prior impairments, and reported liquidity metrics include $1.16B in cash as of October 2026. The company’s strategy leans on product innovation, R&D investment, and potential acquisitions. Key issues ahead include sustaining volume growth, margin resilience amid macro risks, and fending off intensifying competition across dental segments. [S1] [S2]
Envista Holdings’ recent results mark a turning point after a challenging 2024, highlighted by a return to operating profitability, robust sales growth fueled by both core dental products and deferred clear aligner revenue, and a maintained gross margin profile. The company’s strategic focus on innovation and portfolio breadth is set against a backdrop of intensifying competition and macroeconomic uncertainties, raising critical questions about the sustainability of its recovery and the potential for further margin expansion. As Envista invests in R&D and explores acquisitions, the next phase will test its ability to convert product momentum into durable, high-quality earnings.
Recent Financial Turnaround Anchored by Specialty Segment and Clear Aligner Momentum
Envista reported total sales of $2.72 billion for 2025, representing an 8.3% year-over-year increase, with 6.5% core growth excluding acquisitions, discontinued products, and currency effects. This growth was supported by higher sales volumes and the recognition of deferred revenue from clear aligner treatment plans, indicating rising demand for orthodontic offerings and strong execution in the Specialty Products & Technologies segment. Gross profit margin remained stable at 54.7%, helped by pricing actions, manufacturing productivity, and the absence of impairment charges that weighed on prior-year results. Operating profit rebounded to $216.1 million, reversing a previous loss, with the Specialty segment’s margin rising to 10.9%. Envista also reported a cash balance of $1.16 billion and a current ratio of 2.45 as of October 2026, providing a reported liquidity position. [S1] [S2]
How Envista’s Product Mix and Innovation Strategy Shape Margin Potential
Envista’s revenue base is diversified across two main segments: Specialty Products & Technologies (including high-margin implants, clear aligners, and digital solutions) and Equipment & Consumables (typically lower-margin but higher-volume products). The company’s economics are sensitive to shifts in product mix—accelerating adoption of clear aligners and digital orthodontics can drive higher ASPs and gross margins, while equipment sales tend to be more cyclical and capital-expenditure dependent. The stable 54.7% gross margin in 2025 reflects a favorable mix shift and effective cost management, though future margin expansion may depend on continued growth in premium categories and operational leverage from scale.
Operating expenses are weighted toward SG&A, but R&D spending is rising as a share of sales—$114 million in 2025—reflecting a deliberate push for innovation in a tech-driven dental market. While this investment could fuel future product cycles and differentiation, it also raises the company’s fixed cost base. Capital requirements are moderate; the business model is less asset-intensive than heavy manufacturing but requires ongoing investment in product development, regulatory compliance, and go-to-market capabilities. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S1] [S2]
Competing Across Dental Technology: Advantages and Risks in a Crowded Market
Envista’s broad portfolio—spanning implants, orthodontics, digital imaging, and consumables—positions it as a full-spectrum supplier to dental practices and labs. This breadth facilitates cross-selling and helps insulate the business from volatility in any single category. However, the company faces intense competition from specialized players in each segment, as well as from larger diversified device manufacturers.
The clearest advantages for Envista are its established relationships in North America and Europe, ongoing innovation pipeline, and the ability to bundle products and services. However, barriers to switching in dental equipment and consumables are moderate; price sensitivity is significant among dental practices, and new entrants can disrupt categories through digital innovation or aggressive pricing. The orthodontic aligner market, in particular, is highly competitive, with both legacy manufacturers and direct-to-consumer startups vying for share. Envista’s ability to maintain differentiation will hinge on the success of its new product launches, integration of acquired offerings, and responsiveness to evolving practitioner and patient needs.
Unlocking Premium Growth: How Innovation and Strategic Acquisitions Could Accelerate Earnings
If Envista’s investments in R&D and product development yield a robust pipeline of differentiated implants, aligners, and digital workflow solutions, the company could capture outsized share in the fast-growing segments of the dental market. Increased adoption of clear aligners, especially if supported by compelling clinical data and practitioner acceptance, could elevate both sales and margins. Successful execution of bolt-on acquisitions that expand the portfolio or provide access to new geographies would further amplify growth and operational leverage.
The upside scenario would be confirmed by sustained double-digit sales growth in the Specialty Products & Technologies segment, gross margin expansion above 55%, and visible contributions from recently launched or acquired products. Evidence would also include improved customer retention rates (if disclosed), a rising proportion of revenue from digital and premium categories, and positive analyst commentary on portfolio differentiation and innovation velocity.
Steady Growth Amid Competitive Friction and Macro Uncertainty
The most plausible trajectory for Envista is continued mid-single-digit core sales growth, supported by incremental gains in clear aligners, implants, and digital equipment, but tempered by competitive pricing and periodic macro headwinds. Gross margins are likely to remain stable in the low-to-mid 50% range, with SG&A and R&D investment keeping operating margins in the high single to low double digits.
This scenario assumes modest success from product innovation—enough to offset price and volume pressures but not sufficient to fundamentally alter category dynamics. Acquisitions may add breadth but could be offset by integration costs and dilution in the near term. Confirmation would come from quarterly sales growth tracking in the 5-8% range, stable gross margins, and disciplined expense management. Falsification would require evidence of stalled revenue momentum, material margin compression, or failed integration of new acquisitions.
Margin Compression Risks: What Could Derail Envista’s Recovery
An adverse scenario could materialize if macroeconomic pressures—such as currency swings, tariffs, or supply chain disruptions—drive up costs or suppress dental procedure volumes. Increased competition, especially in clear aligners and implants, could trigger price wars or force Envista to accelerate discounting, eroding gross margins. Integration missteps or underperformance from recent acquisitions could further strain operating profit.
Downside confirmation would include a return to significant impairment charges, gross margins falling below 52%, or core sales growth decelerating below 3%. Additional warning signs would be a sharp rise in SG&A or R&D relative to sales without corresponding revenue uplift, and any material deterioration in liquidity or working capital metrics.
Factors That Will Determine Whether Envista’s Growth Is Sustainable
Quarterly core sales growth by segment—especially in Specialty Products & Technologies versus Equipment & Consumables—would help clarify the durability of recent momentum.
Gross margin trajectory, with attention to the impact of product mix, pricing, and manufacturing productivity.
R&D expense as a percentage of sales, and evidence that innovation spend is translating into new product launches and market share gains.
Volume and revenue contribution from clear aligners and other premium categories; a useful metric would be practitioner adoption rates and aligner case starts, if disclosed.
Integration progress and revenue synergies from any newly acquired businesses; management commentary or segment reporting would help track this.
Trends in operating profit margin, especially in the Specialty Products & Technologies segment, to assess leverage from sales growth.
Any indications of renewed impairment charges or asset write-downs, which would signal underlying business stress.
Shifts in customer retention or average revenue per customer (if disclosed), to gauge the stickiness of Envista’s solutions.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments