
Profusa’s High-Stakes Transition: Biosensing Ambition Meets Financial and Strategic Headwinds
The company’s ability to translate innovation into a sustainable business is at a critical juncture, hinging on successful execution, acquisition integration, and stabilization of its capital structure.
The company’s ability to translate innovation into a sustainable business is at a critical juncture, hinging on successful execution, acquisition integration, and stabilization of its capital structure. [S2] [N2] [N6]
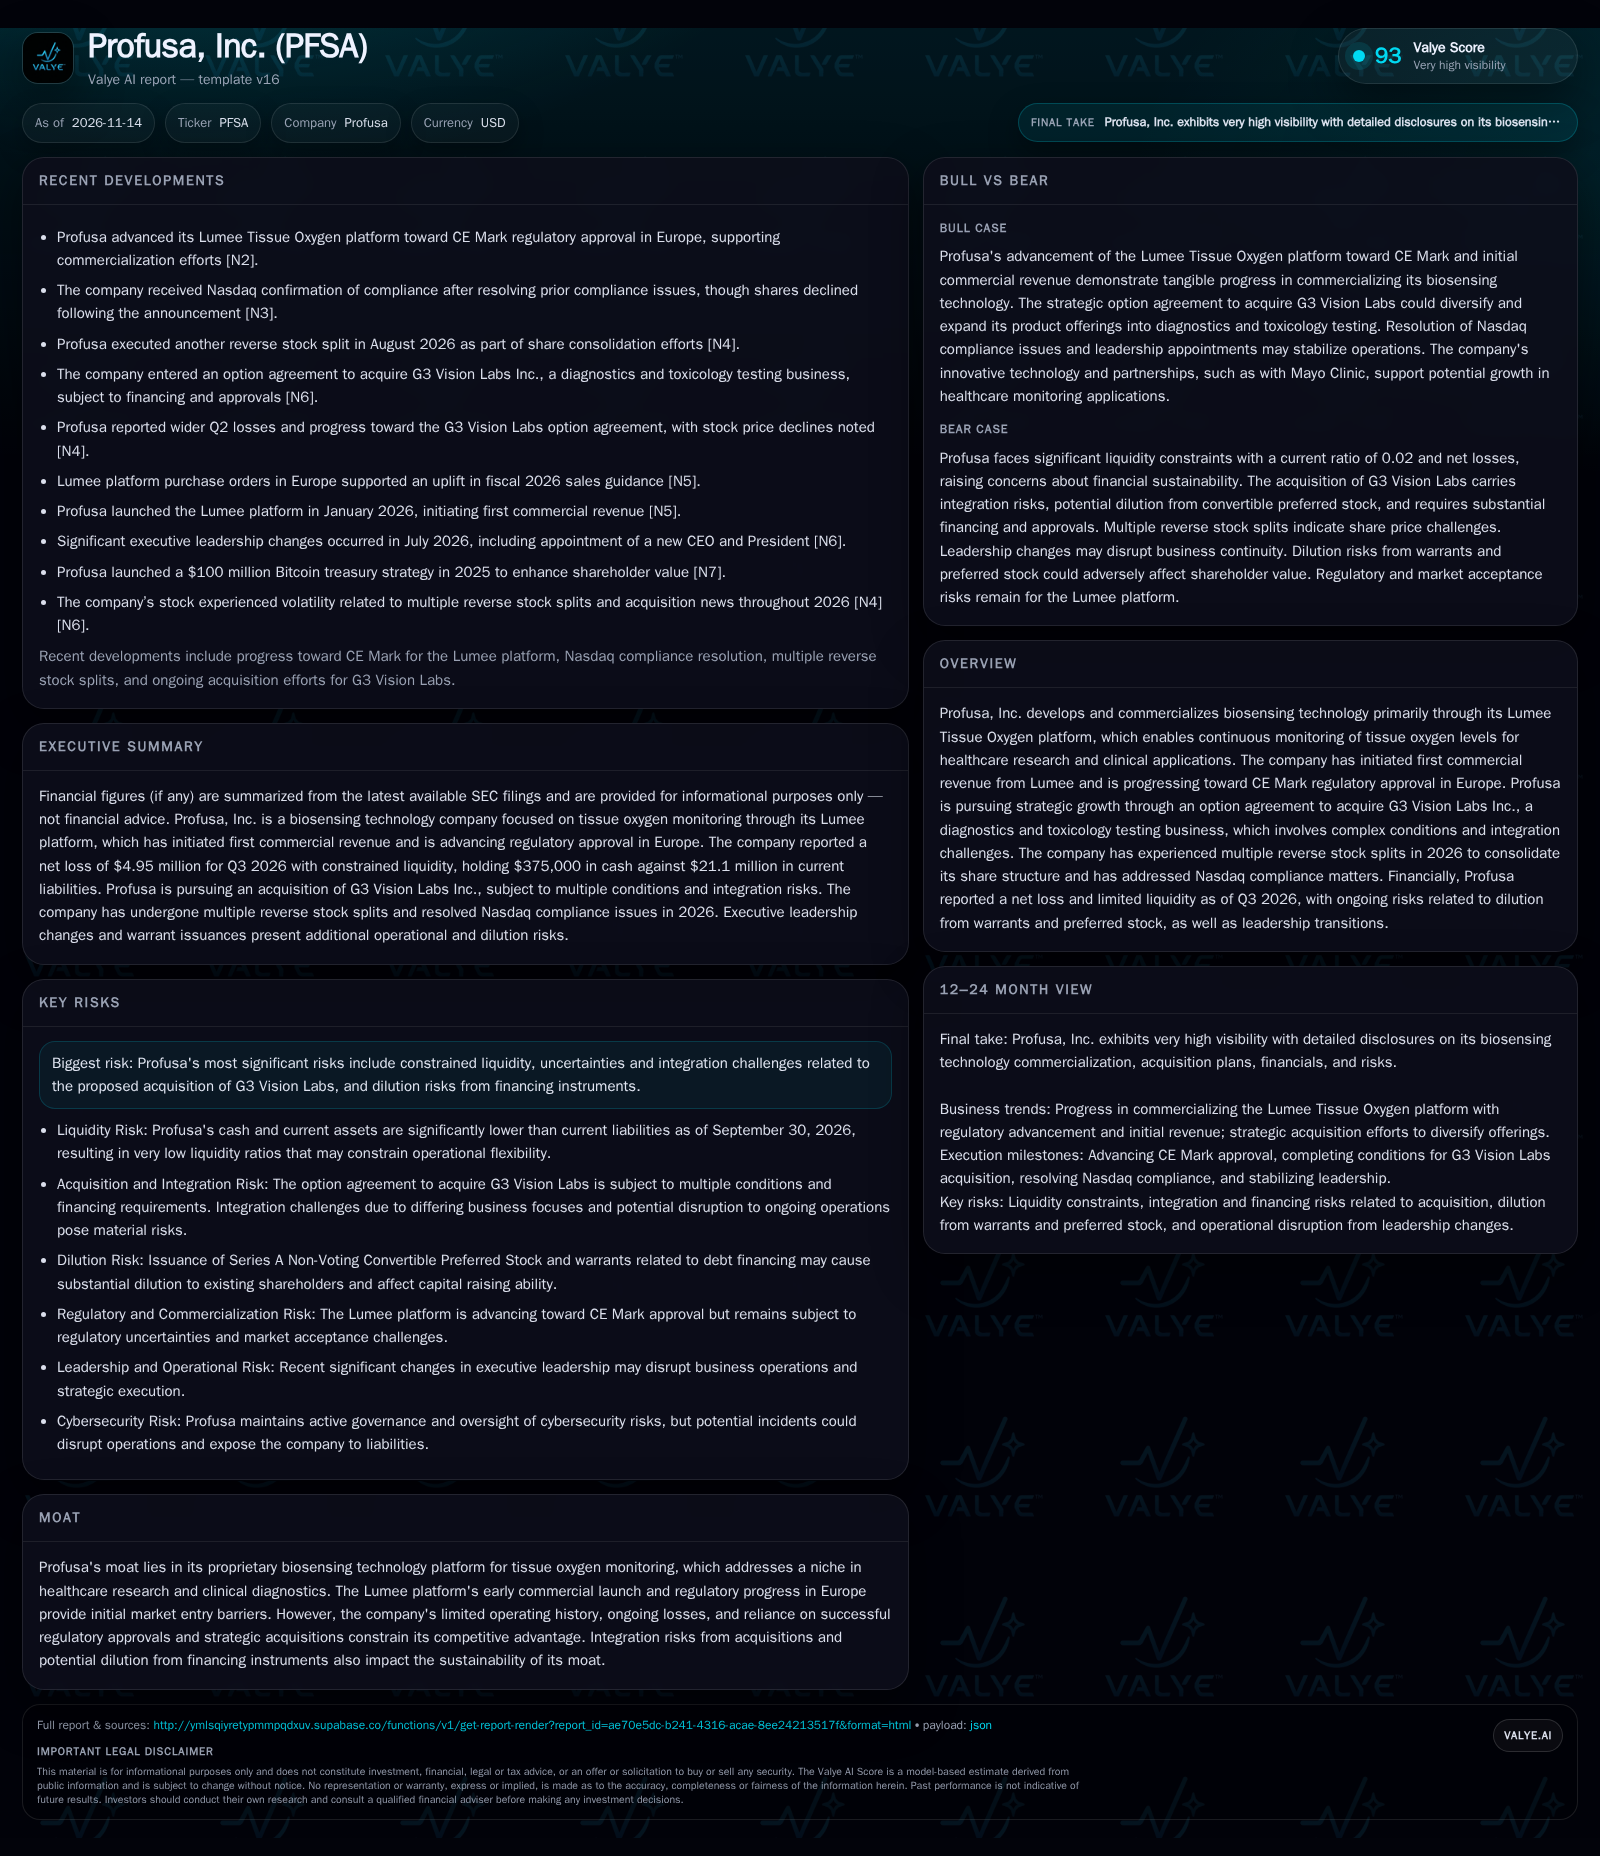
Profusa, Inc. stands at a precarious crossroads. Despite technical progress with its Lumee biosensing platform and steps toward expanding into diagnostics via the G3 Vision Labs acquisition, the company’s financial situation is acutely strained. Whether Profusa can convert its innovation into a viable commercial enterprise or succumbs to structural pressures hinges on near-term execution, financing creativity, and the ability to stabilize both its capital and leadership base. [S2] [N2] [N6]
Liquidity Crunch, Acquisition Gambit, and Leadership Upheaval: Profusa’s Immediate Reality
As of September 30, 2026, Profusa reported cash and equivalents of $375,000 and current assets totaling $394,000—set against a daunting $21.1 million in current liabilities, resulting in a current ratio of just 0.02. This stark imbalance signals severe liquidity strain, with little margin for operational missteps or unexpected expenditures. [S2]
The company is advancing a strategic option agreement to acquire G3 Vision Labs, a diagnostics and toxicology business, but this move introduces complex integration risks and may trigger further dilution through conversion of Series A Preferred Stock. [S2] [N6]
Profusa has executed multiple reverse stock splits in 2026, aiming to consolidate its share structure and maintain Nasdaq compliance, but these actions have coincided with heightened share price volatility and investor uncertainty. [N4] [N6]
A significant leadership shakeup took place in July 2026, with the appointment of a new CEO and President, introducing potential for both strategic redirection and operational disruption during a period of heightened risk. [S2] [N6]
Revenue Potential and Structural Challenges in Profusa’s Commercial Model
Profusa’s core business model centers on the commercialization of its Lumee Tissue Oxygen biosensor platform, targeting continuous tissue oxygen monitoring for clinical and research applications. The platform’s value proposition hinges on providing real-time, minimally invasive data to healthcare professionals, potentially improving patient outcomes and enabling new research paradigms.
While Profusa has received purchase orders for the Lumee system in Europe, the scale, pricing structure, and gross margin profile of these sales remain undisclosed. If the company adopts a razor-and-blade model—selling disposable sensors alongside a reusable reader—recurring revenue could be substantial, provided clinical adoption and reimbursement pathways are established. Alternatively, if sales are predominantly capital equipment, revenue predictability would be lower and working capital needs higher.
The planned acquisition of G3 Vision Labs suggests a strategic pivot toward diagnostics and toxicology testing, which may offer higher throughput and more stable cash flows if integration succeeds. However, G3’s business focus differs from Profusa’s biosensing roots, raising questions about operational synergies and the risk of management distraction.
Operating leverage is a double-edged sword: while fixed R&D and regulatory costs could yield margin expansion if sales scale, the current cost base is outstripping revenues, as evidenced by a Q3 2026 net loss of $4.95 million. With limited cash, Profusa faces urgent capital needs—likely requiring dilutive equity, high-cost debt, or asset sales unless a near-term commercial inflection is achieved. [S2]
Niche Technology Meets Fragmented Markets and Scaling Barriers
Profusa’s competitive edge is rooted in its proprietary biosensing platform, which addresses a relatively underserved need for continuous tissue oxygen monitoring. Existing alternatives—such as pulse oximetry and transcutaneous sensors—are less suited for certain clinical and research environments where continuous, localized, or minimally invasive measurement is required.
However, the biosensing and diagnostics markets are highly fragmented, with entrenched medical device incumbents, aggressive startups, and technology giants eyeing digital health opportunities. Profusa’s ability to build durable differentiation rests on successful regulatory approvals, clinical validation, and integration into standard care pathways—none of which are guaranteed.
The G3 Vision Labs acquisition could expand Profusa’s footprint into diagnostics and toxicology, but brings new competitors with established scale, distribution, and customer relationships. Integration missteps could erode focus and slow innovation, while dilution from financing may weaken Profusa’s ability to invest in R&D and commercialization.
Switching costs for healthcare providers are generally low unless Profusa can demonstrate clear clinical advantages, cost savings, or seamless integration with hospital IT systems. Without robust evidence of superior outcomes or workflow efficiency, customer adoption could stall.
What It Would Take for Profusa to Unlock Commercial Traction and Broaden Its Platform
The most favorable scenario is one where Profusa achieves regulatory milestones for the Lumee platform in major healthcare markets (e.g., CE Mark in Europe), translates early purchase orders into repeat, scaled institutional contracts, and demonstrates clinical value that drives reimbursement and adoption. If the G3 Vision Labs acquisition closes smoothly, Profusa could cross-sell diagnostics and biosensing solutions, leveraging broader customer relationships and diversifying revenue.
This path would require: 1) evidence of recurring sales growth from the Lumee platform, 2) successful integration of G3 operations without significant attrition or culture clash, and 3) non-dilutive or minimally dilutive financing to bridge to positive cash flow.
Confirmation would come from sequential revenue growth, gross margin improvement, new contract wins, and clear disclosure of commercial terms and customer retention. A stabilized leadership team with relevant experience in scaling medtech platforms would also affirm this trajectory.
Falsification would occur if regulatory approvals are delayed, if sales remain lumpy and non-recurring, or if integration issues with G3 lead to operational setbacks or unexpected costs.
Staying Afloat: Managing Cash Burn While Seeking a Commercial Beachhead
The most plausible near-term outcome is that Profusa continues to face acute cash constraints, necessitating ongoing dilutive financings and cost containment while attempting to prove commercial traction for the Lumee platform. The company may close the G3 Vision Labs acquisition, but integration will likely be rocky, with possible delays in realizing revenue or cost synergies.
Incremental progress on regulatory and commercial fronts could be offset by persistent net losses, heightened dilution from warrants and preferred stock conversions, and continued share price volatility. Leadership changes may yield strategic refocusing, but also risk further operational disruption if not managed carefully.
Confirmation of this scenario would be continued reverse splits, new equity or convertible debt issuance, modest but inconsistent revenue growth, and limited disclosure of customer concentration or contract duration. Falsification would require either a dramatic commercial breakthrough or, conversely, a rapid loss of operational viability (e.g., bankruptcy or delisting).
Liquidity Exhaustion and Strategic Options Narrowing
The adverse scenario is one in which Profusa’s liquidity is depleted before the Lumee or G3 platforms reach meaningful commercial scale. In this case, the company could be forced into highly dilutive financings, distressed asset sales, or even bankruptcy if new funding is unavailable.
Operational execution could deteriorate under leadership turnover and integration complexity, leading to missed regulatory milestones, loss of key personnel, or customer attrition. Shareholder value would erode further if warrants and preferred shares are converted at depressed prices.
This scenario would be confirmed by missed payroll, delayed filings, auditor going-concern warnings, or public disclosures of default or insolvency. A lack of progress on regulatory or commercial milestones, paired with further leadership churn, would reinforce the downside risk.
Milestones and Evidence That Will Clarify Profusa’s Trajectory
Updates on the G3 Vision Labs acquisition: Milestones such as definitive agreement closure, integration progress, or early revenue contribution would help validate or undermine the diversification thesis.
Regulatory progress for the Lumee platform: Timelines for CE Mark or other approvals, as well as any setbacks, will directly impact commercial potential.
Gross margin and unit economics: Disclosure of average selling prices, contribution margins, and recurring versus one-time revenue would clarify business model viability.
Customer concentration and contract nature: Information on the number, size, and recurrence of purchase orders would indicate whether revenue is sustainable or opportunistic.
Warrant and preferred stock conversion activity: If disclosed, the pace and size of conversions will directly impact dilution and capital structure stability.
Leadership team stability: Announcements regarding retention of key executives or further turnover would be a leading indicator of operational continuity.
Nasdaq compliance and share structure: Any new reverse splits, delisting notices, or compliance updates would signal ongoing or worsening structural challenges.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments