
QNB Corp.: Integration, Restructuring, and the Stakes of Community Banking Scale
QNB Corp.'s acquisition of Victory Bancorp and balance sheet restructuring signal a bid for greater market relevance, but integration costs and competitive headwinds test the durability of its community banking model. The company’s ability to convert scale into sustainable profitability hinges on operational execution, technology adaptation, and resilience to regulatory and economic pressures.
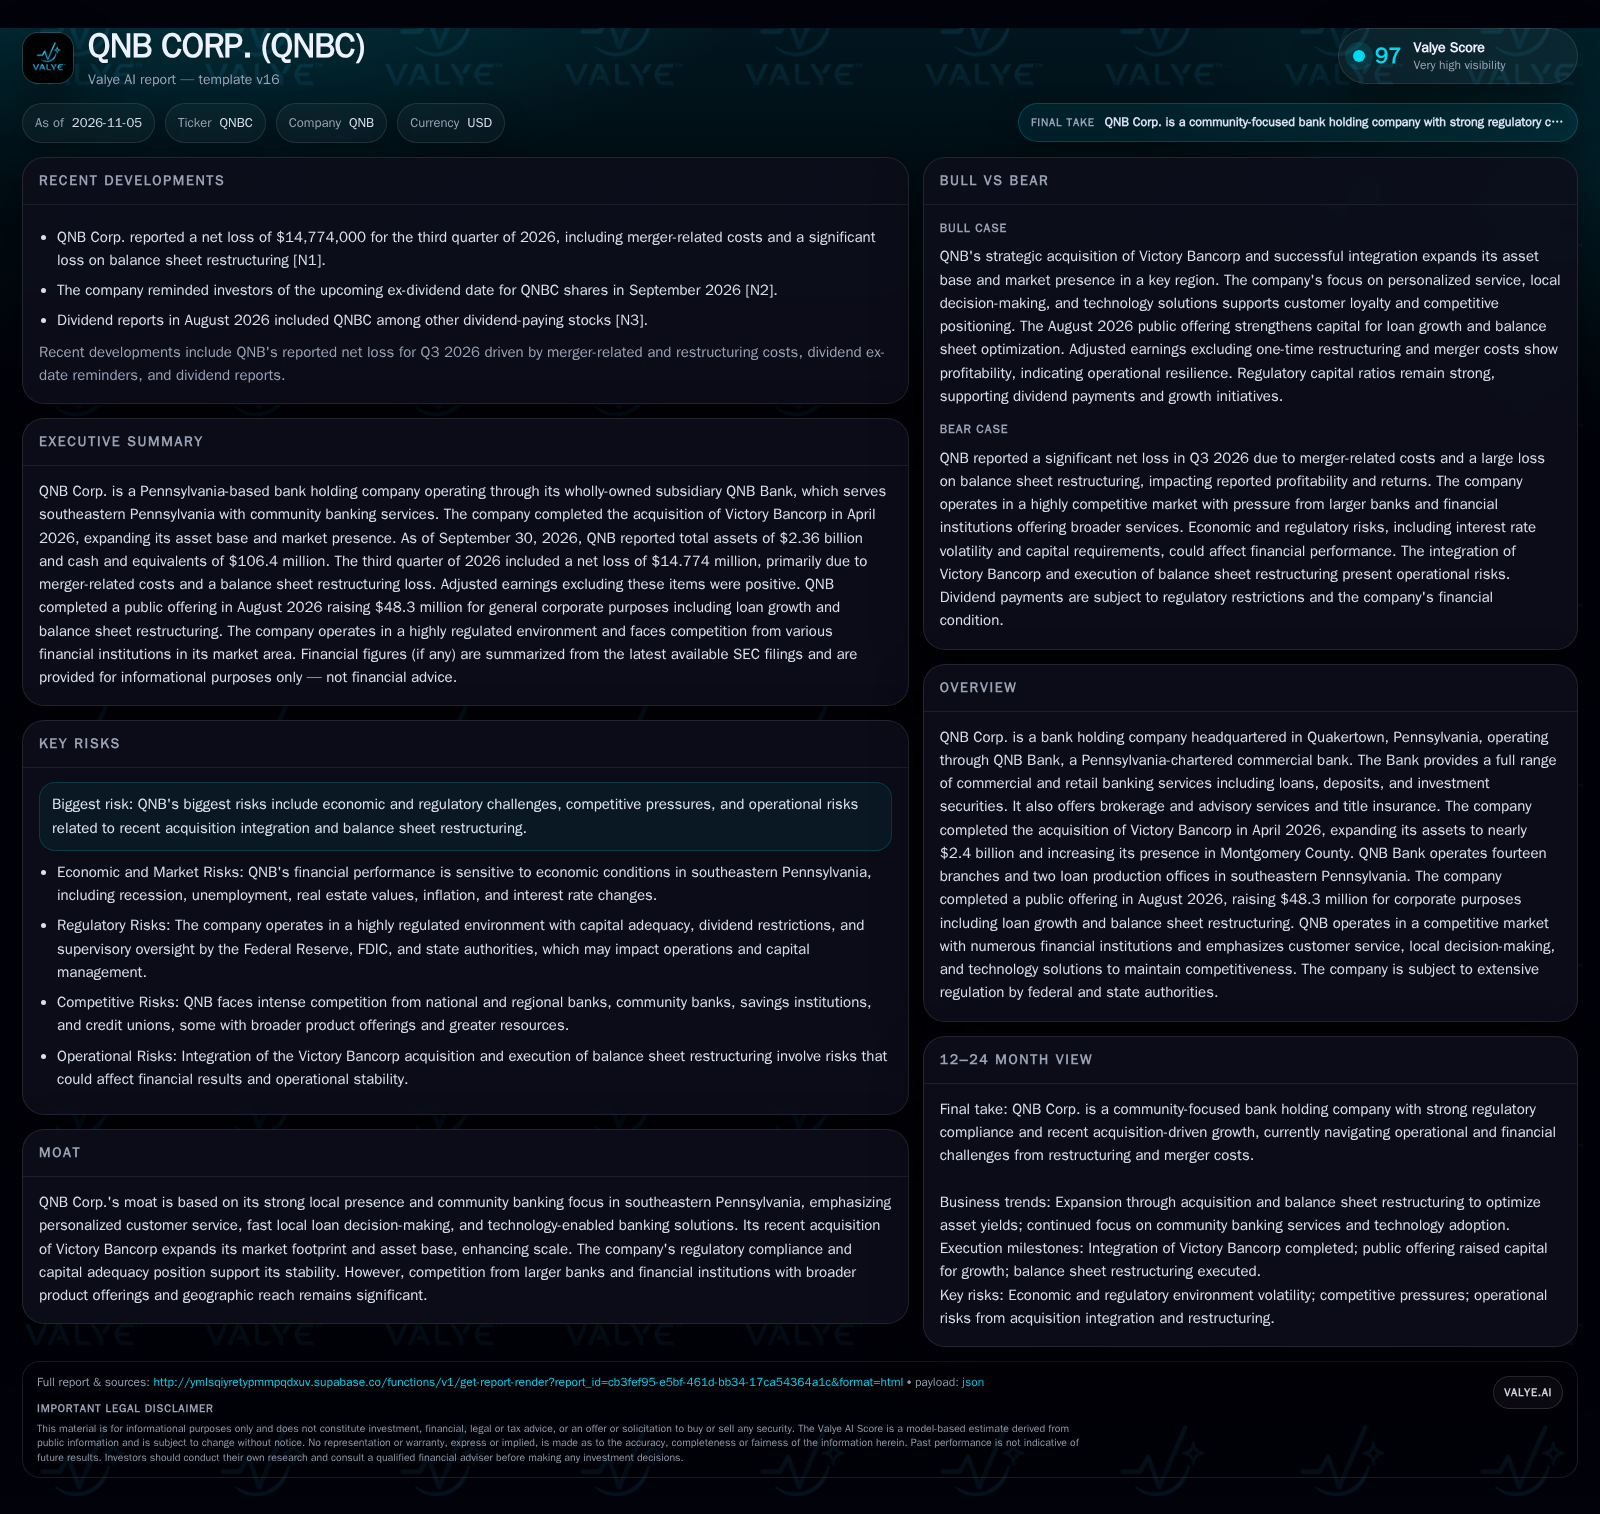
QNB Corp. expanded to nearly $2.4 billion in assets with its April 2026 acquisition of Victory Bancorp, but reported a Q3 2026 net loss of $14.8 million due to merger and restructuring costs. Adjusted earnings were positive and the August 2026 capital raise added $48.3 million, positioning the company for loan growth and balance sheet optimization. The success of QNB’s community banking strategy now depends on integration execution, technology investment, and navigating a competitive, regulated landscape. [S2]
QNB Corp.'s strategic leap—marked by the 2026 acquisition of Victory Bancorp and an August capital raise—aims to reposition the company as a more formidable community banking player in southeastern Pennsylvania. While these moves expanded QNB’s assets and branch footprint, they also brought significant integration and restructuring expenses, resulting in a headline net loss for the third quarter. With adjusted earnings still positive, QNB’s near-term trajectory will be defined by its ability to realize the intended benefits of scale, manage operational risks, and maintain competitiveness amid technological change and regulatory scrutiny. The next phase tests whether local focus and augmented scale can deliver sustainable returns in a crowded market. [S2]
Recent Acquisition and Restructuring Alter the Strategic Landscape
QNB Corp. completed its acquisition of Victory Bancorp in April 2026, increasing total assets to nearly $2.4 billion and extending its community banking reach in Montgomery County. The company now operates 14 branches and two loan production offices, solidifying its regional footprint. In Q3 2026, QNB reported a net loss of $14.774 million, with management attributing this to merger-related costs and a balance sheet restructuring loss. Excluding these one-time charges, adjusted diluted EPS was positive at $1.30, suggesting that underlying operations remained profitable. The August 2026 public offering raised $48.3 million, earmarked for loan growth and further balance sheet optimization. These developments collectively set the stage for QNB’s next chapter, as the company seeks to leverage new scale while resolving the immediate financial drag of integration and restructuring. [S2]
How QNB Generates Value: Revenue Streams, Cost Structure, and Capital Needs
QNB’s core business model revolves around traditional commercial and retail banking—originating loans, gathering deposits, and investing in securities. Revenue is primarily driven by net interest income (the spread between interest earned on loans/securities and interest paid on deposits), complemented by fee income from brokerage, advisory, and title insurance services. The acquisition of Victory Bancorp increases potential loan and deposit volumes, which can improve operating leverage if incremental branch and back-office costs are controlled.
In the near term, however, integration and restructuring costs are likely to weigh on reported margins. Community banks typically face a high fixed-cost base related to branch networks, compliance, and technology infrastructure. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. The mix of commercial versus consumer lending, deposit pricing discipline, and non-interest income generation will be critical levers. If QNB can successfully cross-sell services to its expanded customer base, the franchise could see improved fee income and relationship stickiness.
Community Banking in a Crowded Field: Differentiation and Threats
QNB’s competitive positioning is rooted in its local brand, customer service orientation, and ability to make lending decisions quickly at the branch level. This is a classic community banking value proposition, appealing to small businesses and consumers seeking personalized service and local knowledge. The Victory Bancorp acquisition increases branch density and market presence, but also exposes QNB to intensified competition from national and regional banks, online-first institutions, credit unions, and fintech entrants.
Larger banks typically have advantages in technology investment, broader product suites, and pricing power, while digital challengers can erode fee income and attract rate-sensitive deposits. To defend its niche, QNB must continue to invest in digital banking channels and maintain high service standards. The risk is that increased scale could dilute the local touch that underpins customer loyalty, while failing to keep pace with technology would erode competitiveness. The ability to adapt product offerings, leverage data, and partner with third-party fintechs may determine whether QNB’s expanded footprint translates into durable customer relationships and economic returns.
Turning Scale Into Earnings: What a Successful Integration Could Unlock
The most optimistic outcome for QNB rests on its ability to integrate Victory Bancorp smoothly, realize cost synergies, and accelerate loan and deposit growth across its enlarged footprint. If management can contain integration expenses within guidance and deliver on technology upgrades, the bank could improve its efficiency ratio and expand net interest margins through greater pricing power and cross-selling. The $48.3 million capital raise provides the necessary fuel for new lending and balance sheet restructuring, potentially boosting asset yields and compressing funding costs as the rate environment stabilizes.
Confirmation of this scenario would come from sustained positive adjusted earnings, improving efficiency ratios, and evidence of above-market loan growth in the combined footprint. Additional signals would include growth in non-interest income from brokerage and title services, stable or rising deposit balances, and customer retention rates that outpace local peers. A successful technology rollout—such as increased digital adoption or new product launches—would further validate QNB’s ability to compete at scale.
Integration Headwinds and Incremental Progress Define the Next Phase
A more probable outcome is that QNB experiences a period of uneven financial performance as it works through the operational and cultural challenges of merging two community banks. Integration costs may remain elevated for several quarters, offsetting some of the benefits from increased scale. Loan and deposit growth could be moderate, reflecting both the opportunities from an expanded customer base and the competitive pressures from larger banks and fintechs.
In this scenario, adjusted earnings remain positive but margin expansion is gradual. The company continues to invest in digital capabilities and customer service, but faces ongoing pressure to balance cost discipline with the need to keep up with evolving customer expectations and regulatory requirements. Evidence confirming this middle path would include continued positive adjusted EPS, stable capital ratios, and incremental improvement in operating metrics such as the efficiency ratio and non-interest income contribution.
Integration Missteps or Adverse Market Shocks Could Derail Progress
The principal risk to QNB is that merger integration proves more challenging than anticipated, resulting in higher-than-expected costs, operational disruptions, and customer attrition. If the company struggles to harmonize systems, cultures, or product offerings, the projected synergies may fail to materialize. Additionally, adverse shifts in the regional economy—such as rising unemployment, commercial real estate stress, or a downturn in local business activity—could lead to higher credit losses and pressure net interest margins.
A further risk is that regulatory requirements or compliance costs escalate, particularly as the company grows in size and complexity. Evidence of this downside would include persistent net losses, declining capital ratios, stalled or negative loan/deposit growth, or a spike in non-performing assets. If technology investment lags, QNB could also lose ground to digitally advanced competitors, further eroding profitability and relevance.
Milestones That Will Reveal Whether QNB’s Scale Delivers Sustainable Returns
Branch-level and consolidated loan growth rates, especially in new Victory Bancorp markets, would help test whether QNB is realizing the intended benefits of scale.
Efficiency ratio trends—if disclosed—will indicate whether integration and restructuring are producing sustainable cost savings.
Adjusted return on assets (ROA) and return on equity (ROE) metrics will be central to assessing profitability post-integration.
Net interest margin evolution, particularly as balance sheet restructuring progresses, will reveal QNB’s ability to reprice assets and manage funding costs.
Trends in non-interest income from brokerage and title insurance services could signal the success of cross-selling and product diversification.
Deposit retention and growth by customer segment would provide insight into customer loyalty amid competitive pressures.
Credit quality indicators—such as non-performing asset ratios and net charge-offs—are critical for monitoring downside risk as the loan portfolio expands.
Progress on digital banking adoption, measured by user growth or product launches (if disclosed), would demonstrate QNB’s ability to compete technologically.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments