
Sensei Biotherapeutics: Can Multi-Node Inhibition Unlock New Value in Oncology?
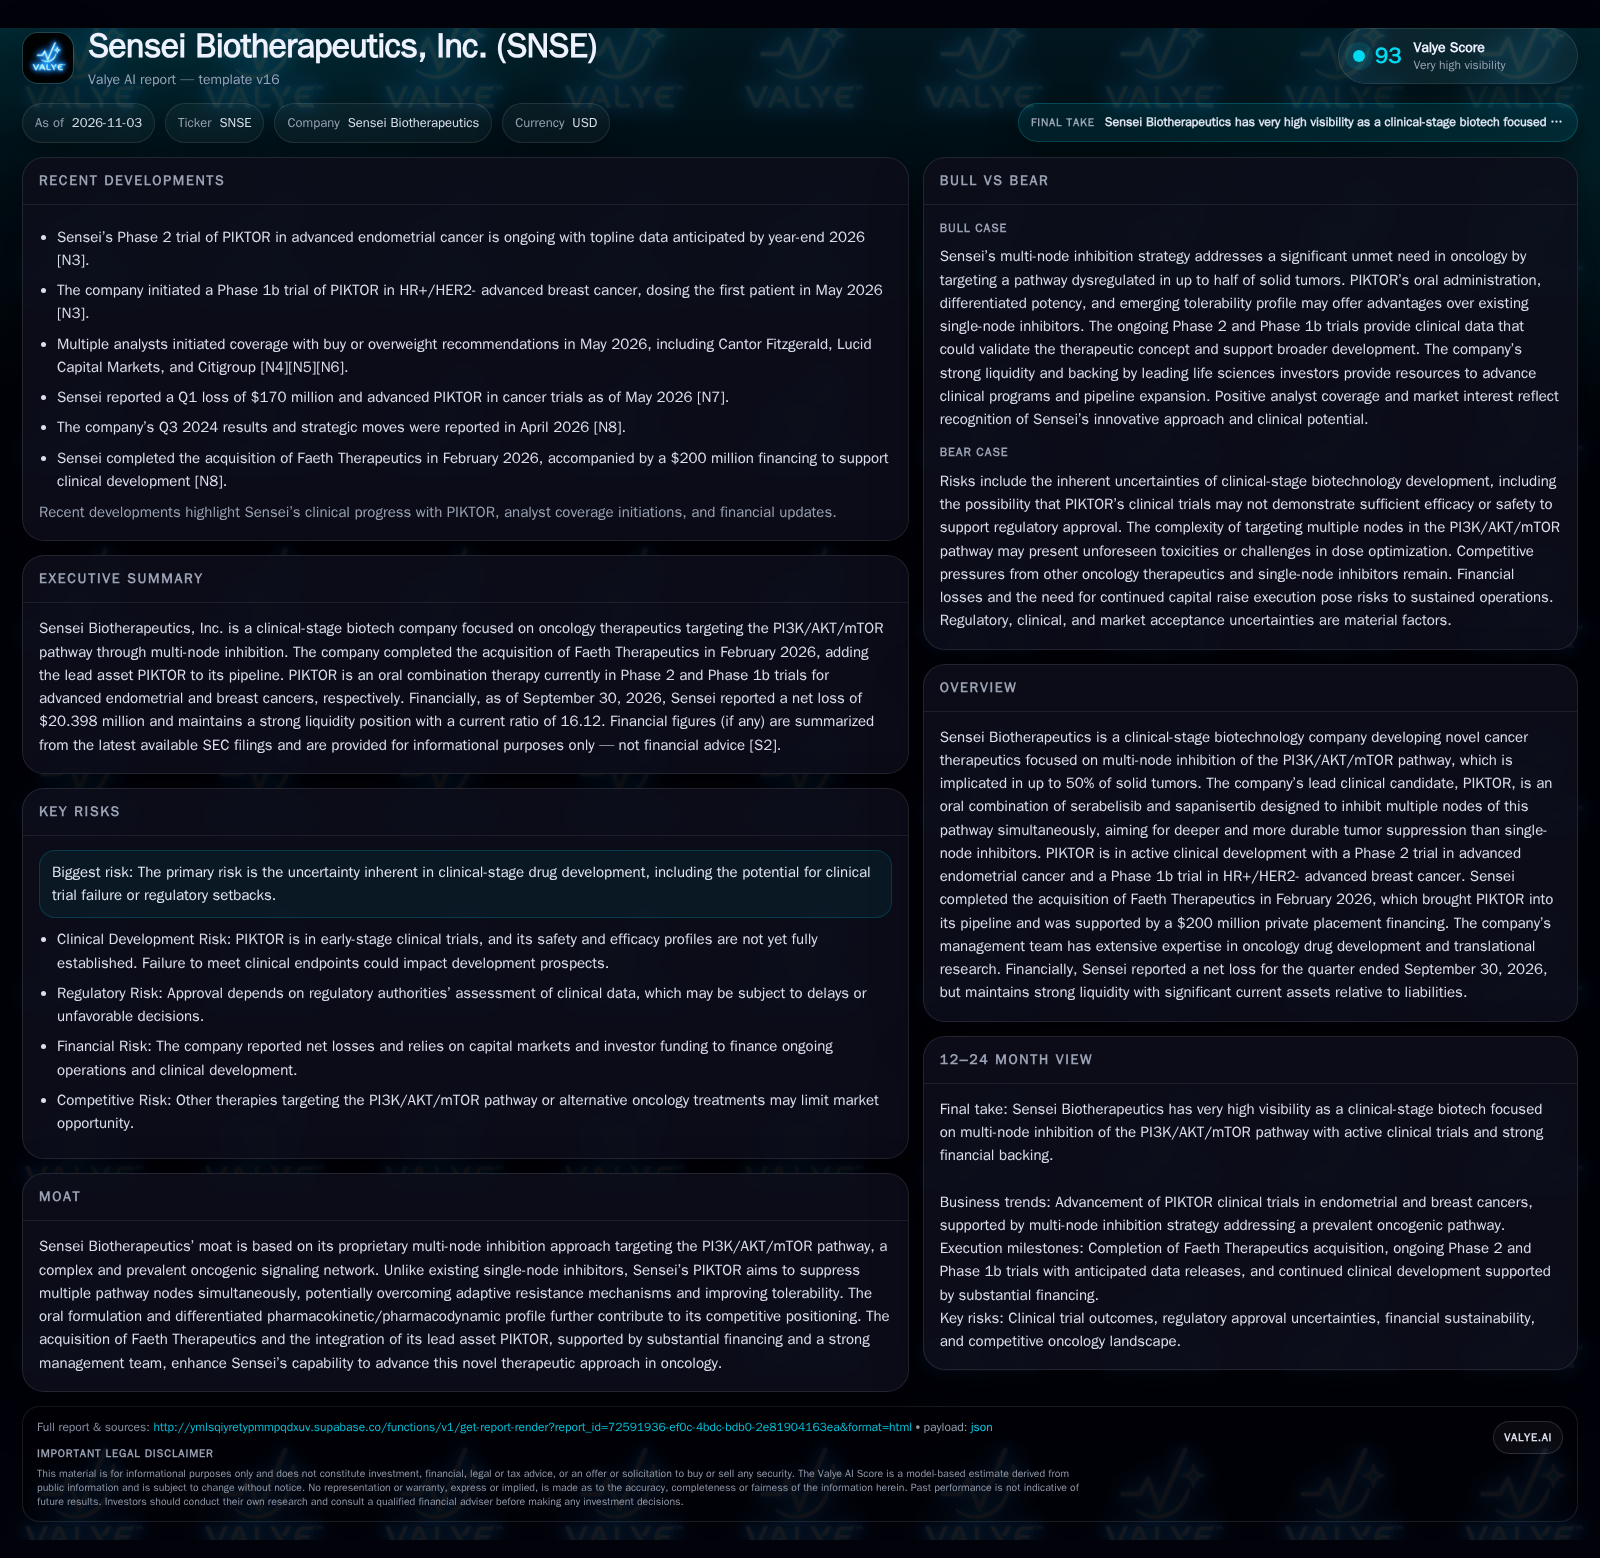
Sensei Biotherapeutics has repositioned itself with the acquisition of Faeth Therapeutics and a $200 million financing, now advancing PIKTOR—a dual PI3K/mTOR inhibitor—through clinical trials in endometrial and breast cancer.
Sensei Biotherapeutics, now operating as Faeth Therapeutics, is advancing its lead asset PIKTOR—an oral dual inhibitor targeting the PI3K/AKT/mTOR pathway—through Phase 2 and Phase 1b trials in endometrial and breast cancer. [S1] [S2]
Sensei Biotherapeutics, newly rebranded as Faeth Therapeutics, is making a high-conviction bet on the power of multi-node inhibition to address one of oncology’s most prevalent and resilient pathways: PI3K/AKT/mTOR. The company’s lead program, PIKTOR—an oral combination of serabelisib and sapanisertib—aims to overcome limitations of existing single-node inhibitors by simultaneously targeting multiple points in the pathway. With the acquisition of Faeth and a $200 million financing, Sensei has both a new scientific thesis and the financial runway to advance two clinical trials through key milestones. But the market’s ultimate question is whether deeper pathway suppression can translate into meaningfully better patient outcomes and a commercially viable product, especially given the historic challenges and competitive pressures in this therapeutic space.
Transformative Acquisition and Clinical Progress Redefine the Sensei Story
The February 2026 acquisition of Faeth Therapeutics brought PIKTOR, a dual PI3K/mTOR inhibitor, into Sensei’s portfolio and was paired with a $200 million private placement. This capital injection provides the means to advance PIKTOR through its ongoing Phase 2 trial in advanced endometrial cancer and Phase 1b trial in HR+/HER2- breast cancer, with topline Phase 2 data expected by year-end 2026. The company reported $14.18 million in cash and $177.84 million in current assets as of September 30, 2026, resulting in a reported current ratio of 16.12. These developments mark a strategic shift, positioning Sensei as a focused clinical-stage oncology player with the resources to test its multi-node inhibition thesis in the clinic. [S1] [S2]
How Multi-Node Inhibition Could Change Oncology Economics for Sensei
Sensei’s business model centers on developing and, if successful, commercializing novel therapeutics for solid tumors by inhibiting multiple nodes of the PI3K/AKT/mTOR pathway. The rationale is that multi-node inhibition can produce more durable and profound tumor suppression than single-node inhibitors, potentially enabling lower doses and improved tolerability. If PIKTOR demonstrates clear efficacy and safety, Sensei could pursue out-licensing, co-development, or direct commercialization, each with distinct economic implications.
Oncology drugs with differentiated profiles—especially those addressing prevalent targets like PI3K/AKT/mTOR—can command premium pricing and rapidly scale if supported by strong clinical evidence. However, commercialization in this space typically requires substantial investment in sales infrastructure, medical affairs, and post-marketing commitments. Any transition from clinical to commercial stage would require additional capital, partnerships, or licensing. The economics will ultimately hinge on whether PIKTOR can command a favorable reimbursement profile and whether its clinical advantages are clear enough to drive adoption over established and emerging competitors.
Competing Against Legacy Inhibitors and Next-Generation Oncology Therapies
Sensei operates in a highly competitive oncology landscape, particularly within the PI3K/AKT/mTOR pathway, which is a target for multiple approved and investigational agents. Single-node inhibitors have often faced durability and toxicity issues, especially with hyperglycemia and stomatitis. PIKTOR’s intermittent dosing and multi-node mechanism are designed to mitigate these shortcomings, but the clinical bar is high: any new entrant must show not only improved efficacy but also a safety/tolerability profile that supports real-world use.
Competitive pressures come from several categories: (1) established single-node inhibitors with regulatory approval and clinical experience, (2) novel agents targeting alternative pathways or mechanisms (such as immune checkpoint inhibitors and antibody–drug conjugates), and (3) other companies pursuing multi-targeted or combination approaches. Large pharma and well-funded biotechs dominate the commercial landscape, making differentiation and data credibility critical. If PIKTOR’s clinical results are meaningfully superior, Sensei may carve out a niche, but the threat of rapid competitor innovation and payer scrutiny remains.
If Superior Tumor Suppression and Tolerability Are Clinically Proven
The most favorable scenario for Sensei is that PIKTOR’s ongoing trials yield compelling objective response rates and progression-free survival in populations with high unmet need, such as advanced endometrial and breast cancers. If multi-node inhibition translates into deeper and more durable responses with manageable adverse events—specifically, lower rates of severe hyperglycemia and stomatitis compared to existing agents—then Sensei could rapidly advance PIKTOR into registrational trials or secure partnerships with major oncology players.
Evidence that would confirm this scenario includes statistically significant improvements in ORR and PFS relative to historical controls, a safety profile that avoids dose-limiting toxicities, and clear signals of clinical benefit in biomarker-defined subgroups. Early positive analyst coverage and Fast Track designation for PIKTOR in combination with paclitaxel for endometrial cancer provide additional momentum. Material partnering or licensing deals, or a strategic buyout, would further validate the upside case.
Most Likely Trajectory: Data Readouts, Incremental Progress, and Continued Capital Needs
The central scenario is that Sensei advances PIKTOR through its planned Phase 2 and Phase 1b trials, generating interpretable but mixed efficacy and safety data. While some signals of efficacy may emerge—especially in biomarker-selected patients—incremental improvements over single-node inhibitors may not be sufficient for rapid regulatory or commercial inflection.
Confirmation of this scenario would include Phase 2 data showing modest improvements in ORR or PFS, with tolerability broadly similar to existing drugs. Absence of severe toxicity would be a positive, but if efficacy is not clearly differentiated, Sensei could face challenges in attracting partners or investors for pivotal trials. Ongoing analyst interest and continued trial enrollment would indicate the market is reserving judgment pending more mature data.
When Multi-Node Inhibition Fails to Translate: Clinical, Regulatory, or Financial Setbacks
The principal risk is that PIKTOR’s clinical trials fail to demonstrate meaningful efficacy or expose new safety liabilities, such as unacceptable rates of hyperglycemia or other off-target effects. If the multi-node approach does not yield better outcomes than single-node inhibitors, or if toxicity proves unmanageable, Sensei could be forced to halt development or pivot to earlier-stage assets.
Downside evidence would include missed primary endpoints, high rates of severe adverse events, or regulatory feedback requiring additional or redesigned trials. Financially, negative data could close the window for further capital raises or partnerships, forcing restructuring or strategic alternatives. In this event, the current liquidity cushion may only delay—rather than prevent—value erosion.
What Will Determine Whether Sensei’s Multi-Node Strategy Delivers Lasting Value
Topline results from the Phase 2 trial of PIKTOR in advanced endometrial cancer (FTH-PIK-201), focusing on objective response rate and progression-free survival.
Emerging safety and tolerability data, especially incidence and severity of hyperglycemia and stomatitis compared to historical benchmarks for PI3K/mTOR inhibitors.
Interim data from the Phase 1b trial in HR+/HER2- breast cancer, including response rates in biomarker-defined subgroups.
Regulatory feedback—such as additional Fast Track or Breakthrough Therapy designations—or requirements for further studies.
Updates on cash burn, operating expenses, and runway estimates as PIKTOR advances through clinical milestones.
Evidence of partnering, licensing, or co-development deals with larger oncology players or strategic investors.
Analyst and investor sentiment shifts following data disclosures, particularly changes in coverage, price targets, or recommendations.
If disclosed, payer and KOL feedback on the clinical differentiation and commercial potential of multi-node inhibition versus standard of care.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments