
Viemed Healthcare’s Growth in Home Respiratory Care Reflects Regulatory and Market Dynamics
Viemed Healthcare’s technology-enabled, home-based clinical model targets the rising demand for respiratory and chronic care in the U.S., but faces reimbursement headwinds, regulatory changes, and intensifying market consolidation. Recent earnings softness highlights execution challenges as the company balances personnel-driven scaling with inflationary and compliance pressures.
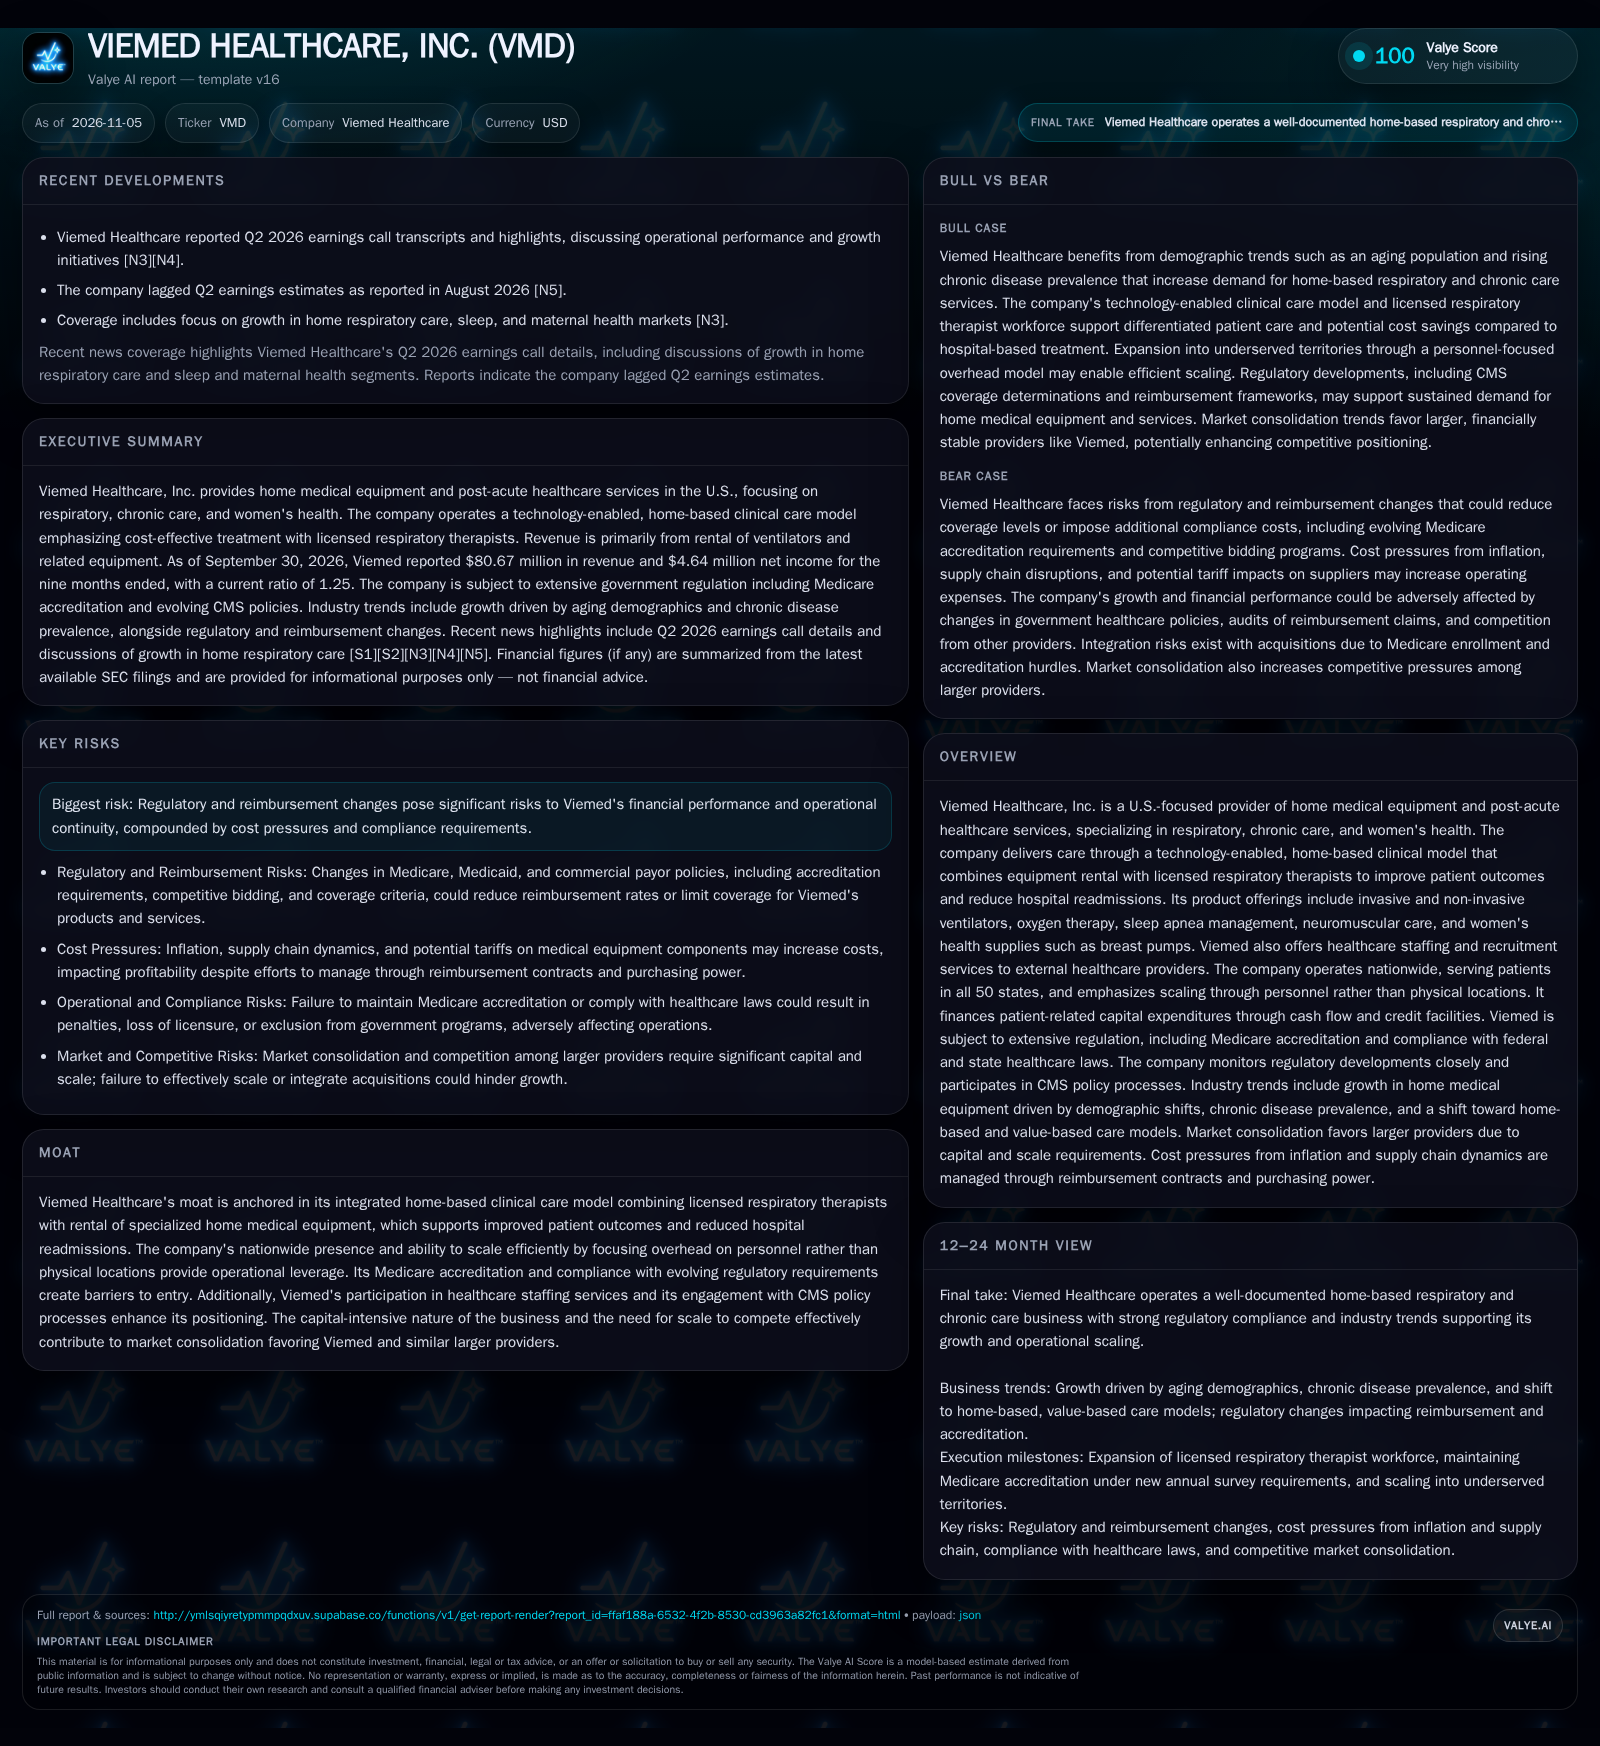
Viemed Healthcare combines home medical equipment rental with licensed clinical staffing to serve chronic respiratory and women’s health needs nationwide. The company’s model leverages a scalable, personnel-focused approach, but recent Q2 2026 earnings lagged expectations as cost pressures and evolving Medicare policies loom. Market dynamics favor larger, well-capitalized providers, but regulatory and reimbursement risks remain central to the investment case. [S2] [N3] [N4] [N5]
Viemed Healthcare, Inc. sits at the intersection of demographic tailwinds and volatile healthcare policy, delivering home-based respiratory and chronic care services across all 50 states. Its technology-enabled model, driven by a clinical workforce rather than bricks-and-mortar buildout, seeks to capitalize on the shift toward value-based care and the growing prevalence of chronic disease. Yet, as recent Q2 2026 earnings disappointed and regulatory clouds gather on the horizon, the company’s ability to preserve margin and expand efficiently will be tested by both industry consolidation and the unpredictability of reimbursement frameworks. [S2] [N5]
Recent Performance and Regulatory Environment Influence Outlook
Viemed Healthcare reported $80.67 million in revenue and $4.64 million in net income for the nine months ended September 30, 2026, with a current ratio of 1.25 and cash of $9.68 million. Revenue continues to be anchored by ventilator rentals and respiratory care services, which together made up approximately 46% to 52% of recent revenue. [S2]
Q2 2026 results lagged earnings estimates, a signal that inflation, supply chain pressures, and potentially tighter reimbursement may be compressing margins or slowing growth. [N5]
The company’s regulatory environment is in flux, with recent CMS coverage determinations on ventilator use for COPD and the upcoming One Big Beautiful Bill Act potentially reshaping Medicare and Medicaid reimbursement starting in 2027. Viemed continues to monitor and participate in policy processes to mitigate these risks. [S2]
Industry consolidation is accelerating, favoring well-capitalized providers with scale and regulatory compliance infrastructure. This landscape both supports Viemed’s expansion ambitions and raises the stakes for operational execution.
Revenue Streams and Operational Leverage in Home-Based Care
Viemed’s core business model centers on renting high-value respiratory equipment—primarily non-invasive and invasive ventilators—bundled with clinical services provided by licensed respiratory therapists. This rental model creates recurring revenue streams with moderate capital intensity: devices are sourced from vendors and deployed to patients, while ongoing care and compliance monitoring are delivered remotely or in-home.
The company’s emphasis on personnel-driven scaling means that fixed costs are weighted toward clinical salaries and compliance rather than physical locations, allowing relatively rapid market entry and flexibility. However, this approach could limit operating leverage compared to asset-heavy models if labor costs rise faster than revenue or if therapist productivity is constrained by regulatory or quality requirements.
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2]
Reimbursement rates—largely set by Medicare, Medicaid, and commercial payers—are the primary determinant of gross margin. Any reduction in coverage, competitive bidding, or increased audit activity directly impacts profitability. Cost inflation (labor, equipment, supply chain) can erode margins unless reimbursement contracts allow for timely pass-throughs or renegotiation.
Industry Consolidation and Regulatory Hurdles Define Competition
Viemed’s competitive position is defined by its nationwide reach, Medicare accreditation, and integrated clinical model. The use of licensed respiratory therapists provides both a service differentiation and a barrier to entry, as compliance and quality requirements are stringent and subject to frequent regulatory updates.
The broader home medical equipment (HME) market is consolidating, with larger and better-capitalized players able to weather reimbursement volatility, invest in compliance, and negotiate better equipment sourcing terms. Smaller providers may struggle to meet new accreditation or competitive bidding standards, especially as CMS policies evolve.
However, as the market concentrates, competition for payer contracts, referral sources, and clinical talent intensifies. Substitutes include hospital-based post-acute care, other HME providers, and emerging telehealth or remote monitoring solutions that could bypass or commoditize aspects of Viemed’s service stack.
Switching barriers for payers and patients are moderate: clinical relationships, therapist continuity, and regulatory compliance create some friction, but reimbursement-driven network decisions or cost pressures could still drive churn.
Potential Gains from Increased Home Care Adoption and Supportive Policies
A bullish outcome for Viemed would see continued migration of chronic respiratory care from institutional to home settings, supported by favorable CMS policy—such as expanded ventilation coverage, stable or rising reimbursement rates, and limited audit or competitive bidding disruption.
In this scenario, Viemed’s personnel-driven scaling enables rapid penetration of underserved markets, leveraging its clinical therapist workforce to win referrals and contract extensions. The company’s purchasing power and established regulatory infrastructure could allow it to absorb inflationary pressures better than smaller peers.
Confirmation would come from above-market revenue growth, margin stability or expansion despite industry cost pressures, and visible gains in market share—potentially evidenced by additional payer contracts or public reporting of patient volumes. Regulatory filings or CMS policy updates that maintain or improve reimbursement for home ventilation would further support the thesis.
Expected Trends: Margin Challenges Amid Consistent Chronic Care Needs
The most plausible path is one in which Viemed continues to grow modestly, with demographic tailwinds—aging population, chronic disease prevalence—driving steady demand for home-based respiratory support. However, reimbursement rates remain flat or face minor downward adjustments, and cost inflation (labor, equipment) must be managed through modest price renegotiations or efficiency gains.
Personnel-based expansion continues, but hiring and retention of skilled respiratory therapists becomes a limiting factor in some territories, especially as competition for clinical talent intensifies. Market share gains are incremental rather than dramatic.
Confirmation for this scenario would include revenue growth in line with industry averages, stable but not expanding margins, and continued compliance with evolving regulatory requirements. Any major reimbursement shocks or regulatory penalties would falsify this base case.
Risks from Reimbursement Cuts and Rising Operational Costs
A bearish scenario would manifest if Medicare and Medicaid reimbursement for home ventilation and chronic care is cut meaningfully—either through competitive bidding, new audit requirements, or unfavorable policy changes tied to the One Big Beautiful Bill Act or other CMS initiatives.
Further, if inflation in labor or equipment outpaces Viemed’s ability to renegotiate contracts or pass on costs, margins could compress sharply, especially as recent Q2 2026 results have already lagged expectations. [N5]
Operational risks—such as failure to maintain accreditation, regulatory penalties, or significant payer churn—could amplify downside. Market consolidation could also backfire if larger competitors undercut pricing or win exclusive payer relationships.
Confirmation would include declining revenue or shrinking margins, negative earnings surprises, or disclosures of adverse regulatory findings, contract losses, or therapist attrition.
Key Developments That Could Validate Viemed’s Strategy
Sustained revenue growth in the respiratory and chronic care segments, particularly outpacing industry benchmarks, would indicate successful scaling and demand capture. [S2]
Gross margin trends, especially in the face of inflationary pressures, will reveal Viemed’s ability to manage costs and maintain pricing power. [S2]
Updates on regulatory developments—such as CMS policy changes, competitive bidding outcomes, or new accreditation requirements—should be monitored for material impacts on reimbursement or compliance costs. [S2]
Retention and productivity metrics for licensed respiratory therapists, if disclosed, would help assess the scalability and quality of Viemed’s clinical model.
Any changes in payer mix, contract wins/losses, or expansion of value-based care contracts would clarify competitive positioning and long-term margin potential.
Patient volume growth, particularly in newly entered or previously underserved territories, would support the scaling thesis—disclosure of these numbers would be useful.
Evidence of increased audit activity, regulatory penalties, or loss of accreditation would quickly undermine the investment case.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments