
VSee Health: Customizable Telehealth Platform Meets Financial Strain and Competitive Pressures
VSee Health's clinician-configurable telehealth platform and specialty ICU telemedicine services are positioned to address healthcare staffing shortages and patient engagement gaps.
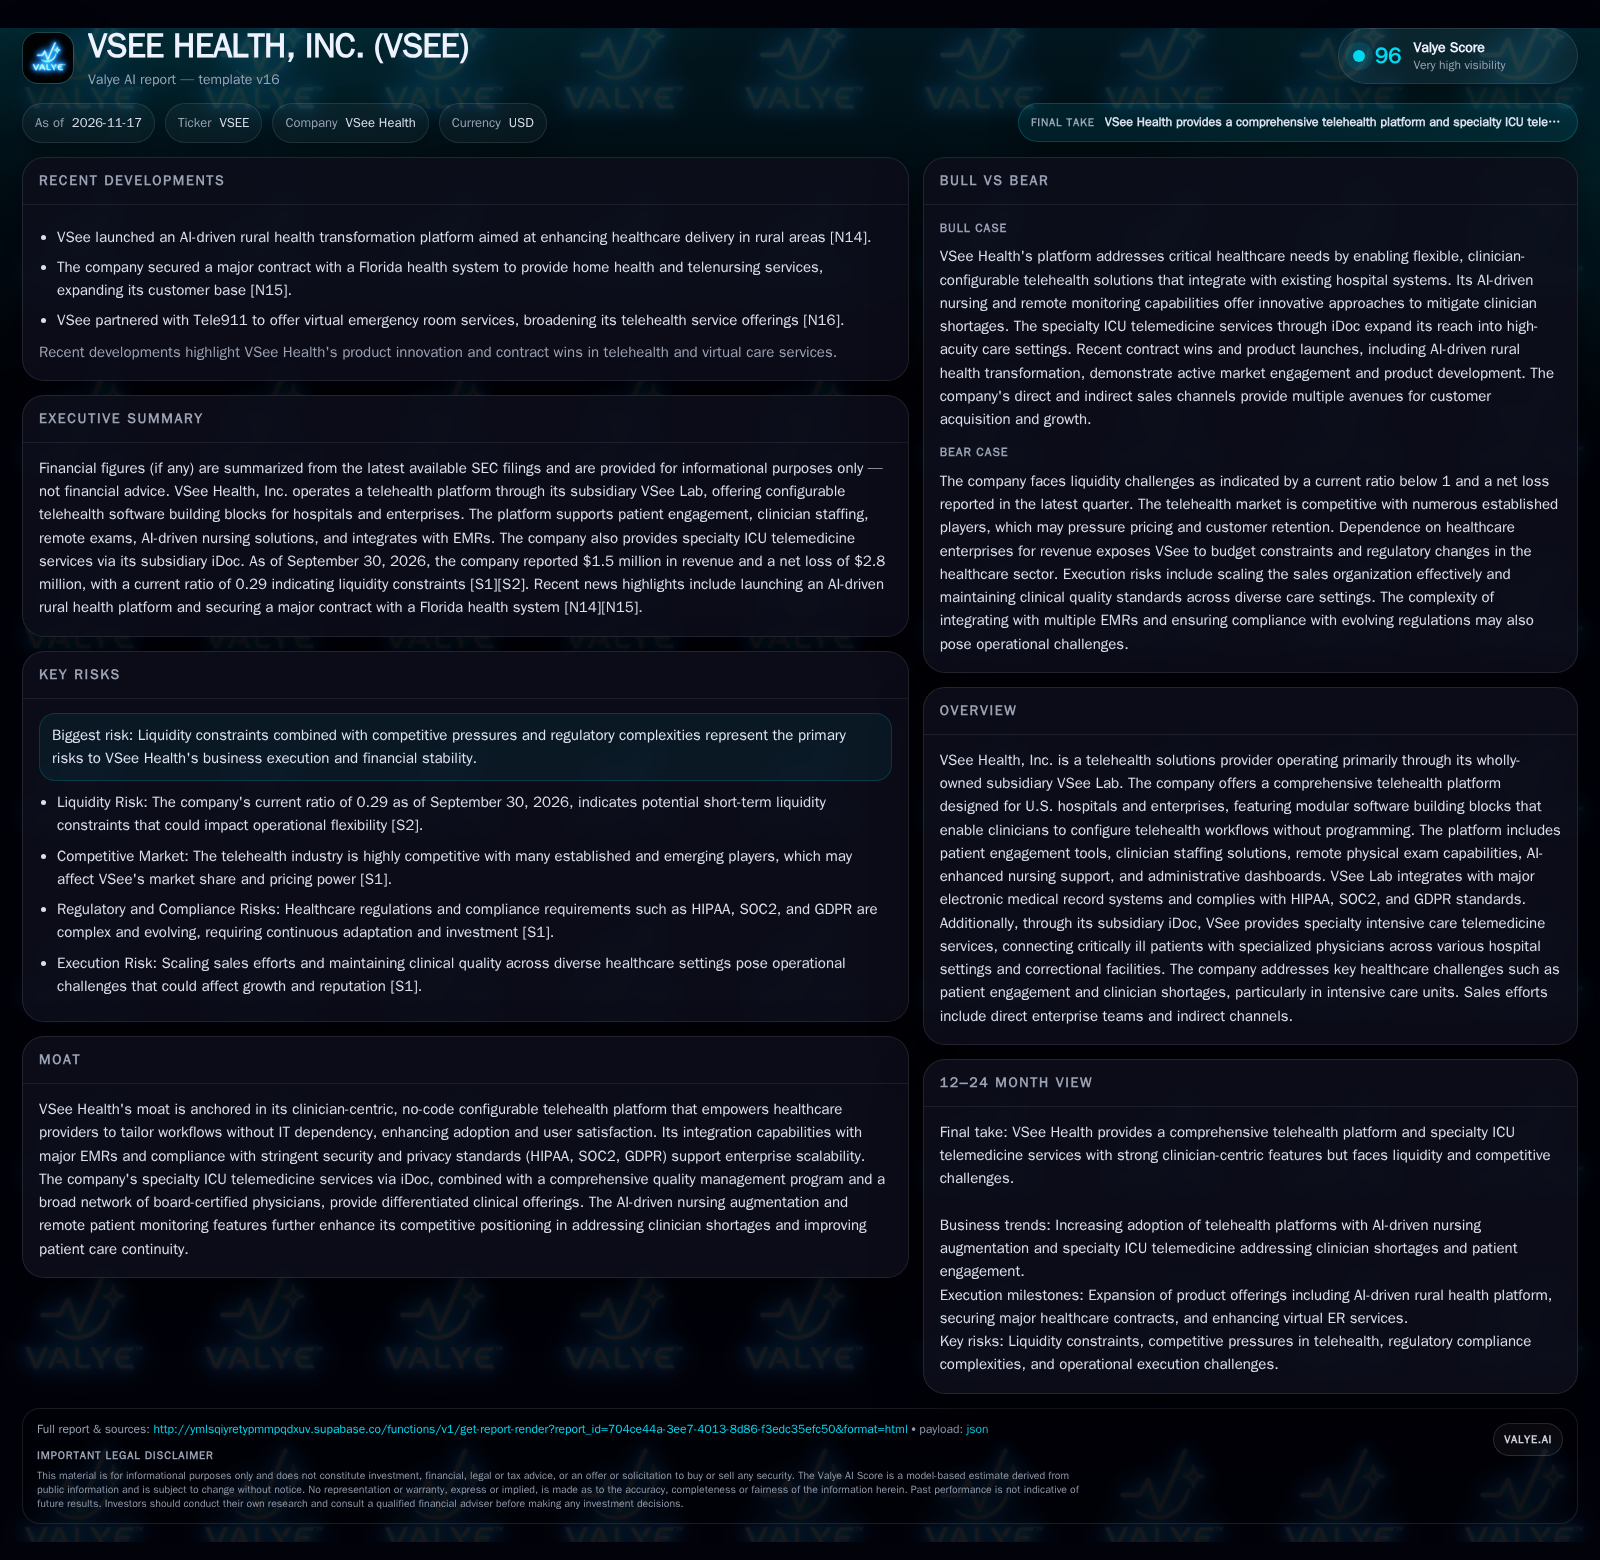
VSee Health's clinician-configurable telehealth platform and specialty ICU telemedicine services are positioned to address healthcare staffing shortages and patient engagement gaps. However, recent financials reflect a net loss and a current ratio of 0.29, highlighting urgent liquidity issues. With direct and indirect sales channels, integration with major EMRs, and compliance with stringent security standards, VSee has carved out differentiated technical capabilities, but faces execution, scaling, and competitive challenges that could determine its viability in a consolidating telehealth sector. [S1] [S2]
VSee Health, Inc. sits at the intersection of technology-driven care delivery and the operational realities of U.S. healthcare. Its flagship telehealth platform empowers clinicians to build custom workflows without programming, integrates with leading EMR systems, and offers AI-augmented nursing and ICU telemedicine services via its iDoc subsidiary. The company’s future now hinges on its ability to convert product differentiation into scalable, recurring enterprise contracts before liquidity pressures force strategic retrenchment or capital raises. [S1] [S2]
Liquidity Constraints and Platform Breadth Define Near-Term Reality
VSee Health’s most material current facts are its $1.5 million in revenue and $2.8 million net loss for the quarter ended September 30, 2026, alongside a cash and equivalents position of just $41,666 and a current ratio of 0.29. [S2]
On the product side, VSee’s platform delivers no-code, clinician-configurable telehealth workflows, robust EMR integrations (EPIC, Cerner), and AI-driven nursing augmentation—addressing both patient engagement and clinician shortages. Its iDoc subsidiary provides specialty ICU telemedicine to a spectrum of hospital and correctional settings, further expanding its clinical reach. [S1]
The juxtaposition of technical breadth and financial fragility sets the stage: VSee must translate its differentiated offering into durable, high-value contracts fast enough to overcome its liquidity gap.
How VSee’s Modular Approach Could Shape Revenue and Margin Dynamics
VSee Health’s business model is built around selling a comprehensive, modular telehealth platform to hospitals and enterprises—potentially via recurring SaaS-like contracts, integration or implementation fees, and value-added AI/ICU telemedicine services. The platform’s no-code configuration and deep EMR integration could enable rapid deployment and reduce switching costs for customers, but commercial terms (e.g., contract length, per-user pricing, or usage-based fees) are not disclosed, leaving margin structure and revenue visibility uncertain. [S1]
Variable revenue streams likely include per-seat or per-visit charges for telehealth, usage fees for remote monitoring, and possibly premium charges for AI-driven nursing or specialty ICU consults delivered via iDoc. Fixed costs include ongoing R&D, compliance, clinical quality management, and salesforce expansion. The model could exhibit operating leverage if recurring contracts scale, but the current net loss and reported cash balance suggest that current revenues do not yet cover fixed expenses. [S2]
Differentiation in a Crowded Telehealth Arena: Moats and Counterforces
VSee Health’s main competitive advantages stem from its clinician-centric, no-code workflow customization, integration with major EMRs, and AI-driven nursing augmentation. These features may reduce IT bottlenecks for hospital customers and support adoption in settings where workflow flexibility and compliance are paramount. [S1]
However, the telehealth market is intensely competitive, with established EHR vendors, pure-play telemedicine companies, and new digital health entrants all vying for enterprise contracts. Many competitors also offer EMR integrations and HIPAA/SOC2 compliance, blunting VSee’s technical moat. Larger players may have more robust ecosystems, greater brand recognition, and deeper sales resources.
AI-driven telesitter and ICU telemedicine features could be differentiators, especially for rural hospitals or those facing acute staffing shortages, but may face substitution from incumbent telehealth providers or in-house hospital IT solutions as AI capabilities become more commoditized.
VSee’s direct and indirect sales channels provide access to varied healthcare customers, but scaling these channels against entrenched competitors is resource-intensive and may be hampered by current liquidity constraints.
If Workflow Flexibility and AI Integration Win Enterprise Adoption
The bull case for VSee Health is that its no-code, highly customizable telehealth platform—combined with AI-powered nursing and specialty ICU telemedicine—addresses urgent pain points for U.S. hospitals: clinician shortages, workflow adaptation, and regulatory compliance. Should these features drive rapid adoption among large hospital systems, VSee could secure multi-year, high-value contracts that provide recurring revenue and improve margins.
Confirmation of this scenario would require evidence of major new enterprise wins (e.g., health systems with multi-site deployments), growing contract backlog, and a shift toward positive operating cash flow. Successful expansion of virtual ER partnerships (like Tele911), adoption in rural and underserved markets, and visible customer retention would reinforce the thesis.
Falsification would occur if customer wins remain small or episodic, if churn rises due to competitive displacement, or if the platform’s workflow flexibility proves insufficient to drive switching from entrenched vendors.
Sustained Technical Progress, but Commercial Traction Lags Financial Needs
The most plausible trajectory is that VSee continues to enhance its platform and secures incremental contracts in niche or underserved hospital segments, but faces a slow ramp in enterprise adoption due to long healthcare sales cycles and budgetary caution among customers. The company may need to pursue bridge financing or strategic partnerships to address its liquidity gap while maintaining product development and compliance investment.
Evidence supporting this scenario would include modest quarter-over-quarter revenue growth, new customer logos in specialized care settings, and gradual improvement in gross margin, but continued negative net income and low cash balances. Announcements of pilot projects, rather than large-scale rollouts, would suggest traction but not yet a flywheel effect.
A shift in this trajectory—up or down—would be signaled by either a breakthrough enterprise contract or, conversely, by disclosure of further liquidity actions or cost-cutting measures that threaten growth capacity.
Liquidity Erosion and Competitive Displacement Threaten Continuity
The adverse scenario is that VSee’s acute liquidity constraints force it to scale back operations, delay product enhancements, or accept unfavorable financing terms, undermining customer confidence and sales momentum. In parallel, larger telehealth and EHR vendors may accelerate competitive displacement by bundling similar functionality or leveraging deeper relationships with hospital IT and procurement.
Confirmation of this downside path would include a further decline in cash and current ratio, missed payroll or vendor payments, layoffs, or a distressed capital raise. Customer attrition or publicized contract losses to larger competitors would exacerbate the risk. Regulatory changes or a high-profile compliance failure would further impair reputation and growth prospects.
The scenario could be partially mitigated if VSee successfully pivots to a narrower, high-margin specialty or secures a strategic investor willing to fund continued technology development.
Milestones and Metrics That Will Clarify VSee Health’s Strategic Trajectory
Quarterly revenue growth rates and evidence of expanding average contract value—a useful metric would be disclosed multi-year enterprise contract wins.
Cash burn rate and updates on external financing or capital raise progress.
New or renewed partnerships with large health systems or virtual ER providers, including deployment scale and duration if disclosed.
Customer retention and churn rates—if disclosed—especially among hospital system and ICU telemedicine clients.
Expansion of AI-driven telesitter and telenursing adoption, measured by hospital site count or number of clinicians served.
Updates on EMR integration depth and breadth—new partnerships with EMR vendors or certifications would help test platform stickiness.
Gross margin evolution, particularly as software and AI services scale relative to labor-intensive telemedicine offerings.
Regulatory or compliance audit outcomes, especially regarding HIPAA/SOC2 and evolving state telehealth rules.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments