
AAON’s R&D-Driven Differentiation: Innovation, Internal Controls, and the Next Phase of HVAC Competition
AAON’s record Q3 results and raised outlook highlight momentum in premium HVAC manufacturing, but material weaknesses in internal controls and the scale of industry competition frame a complex risk/reward calculus. The company’s strategy hinges on advanced R&D, energy efficiency, and lifecycle value, but future gains will depend on execution, remediation, and the ability to defend its niche against larger rivals.
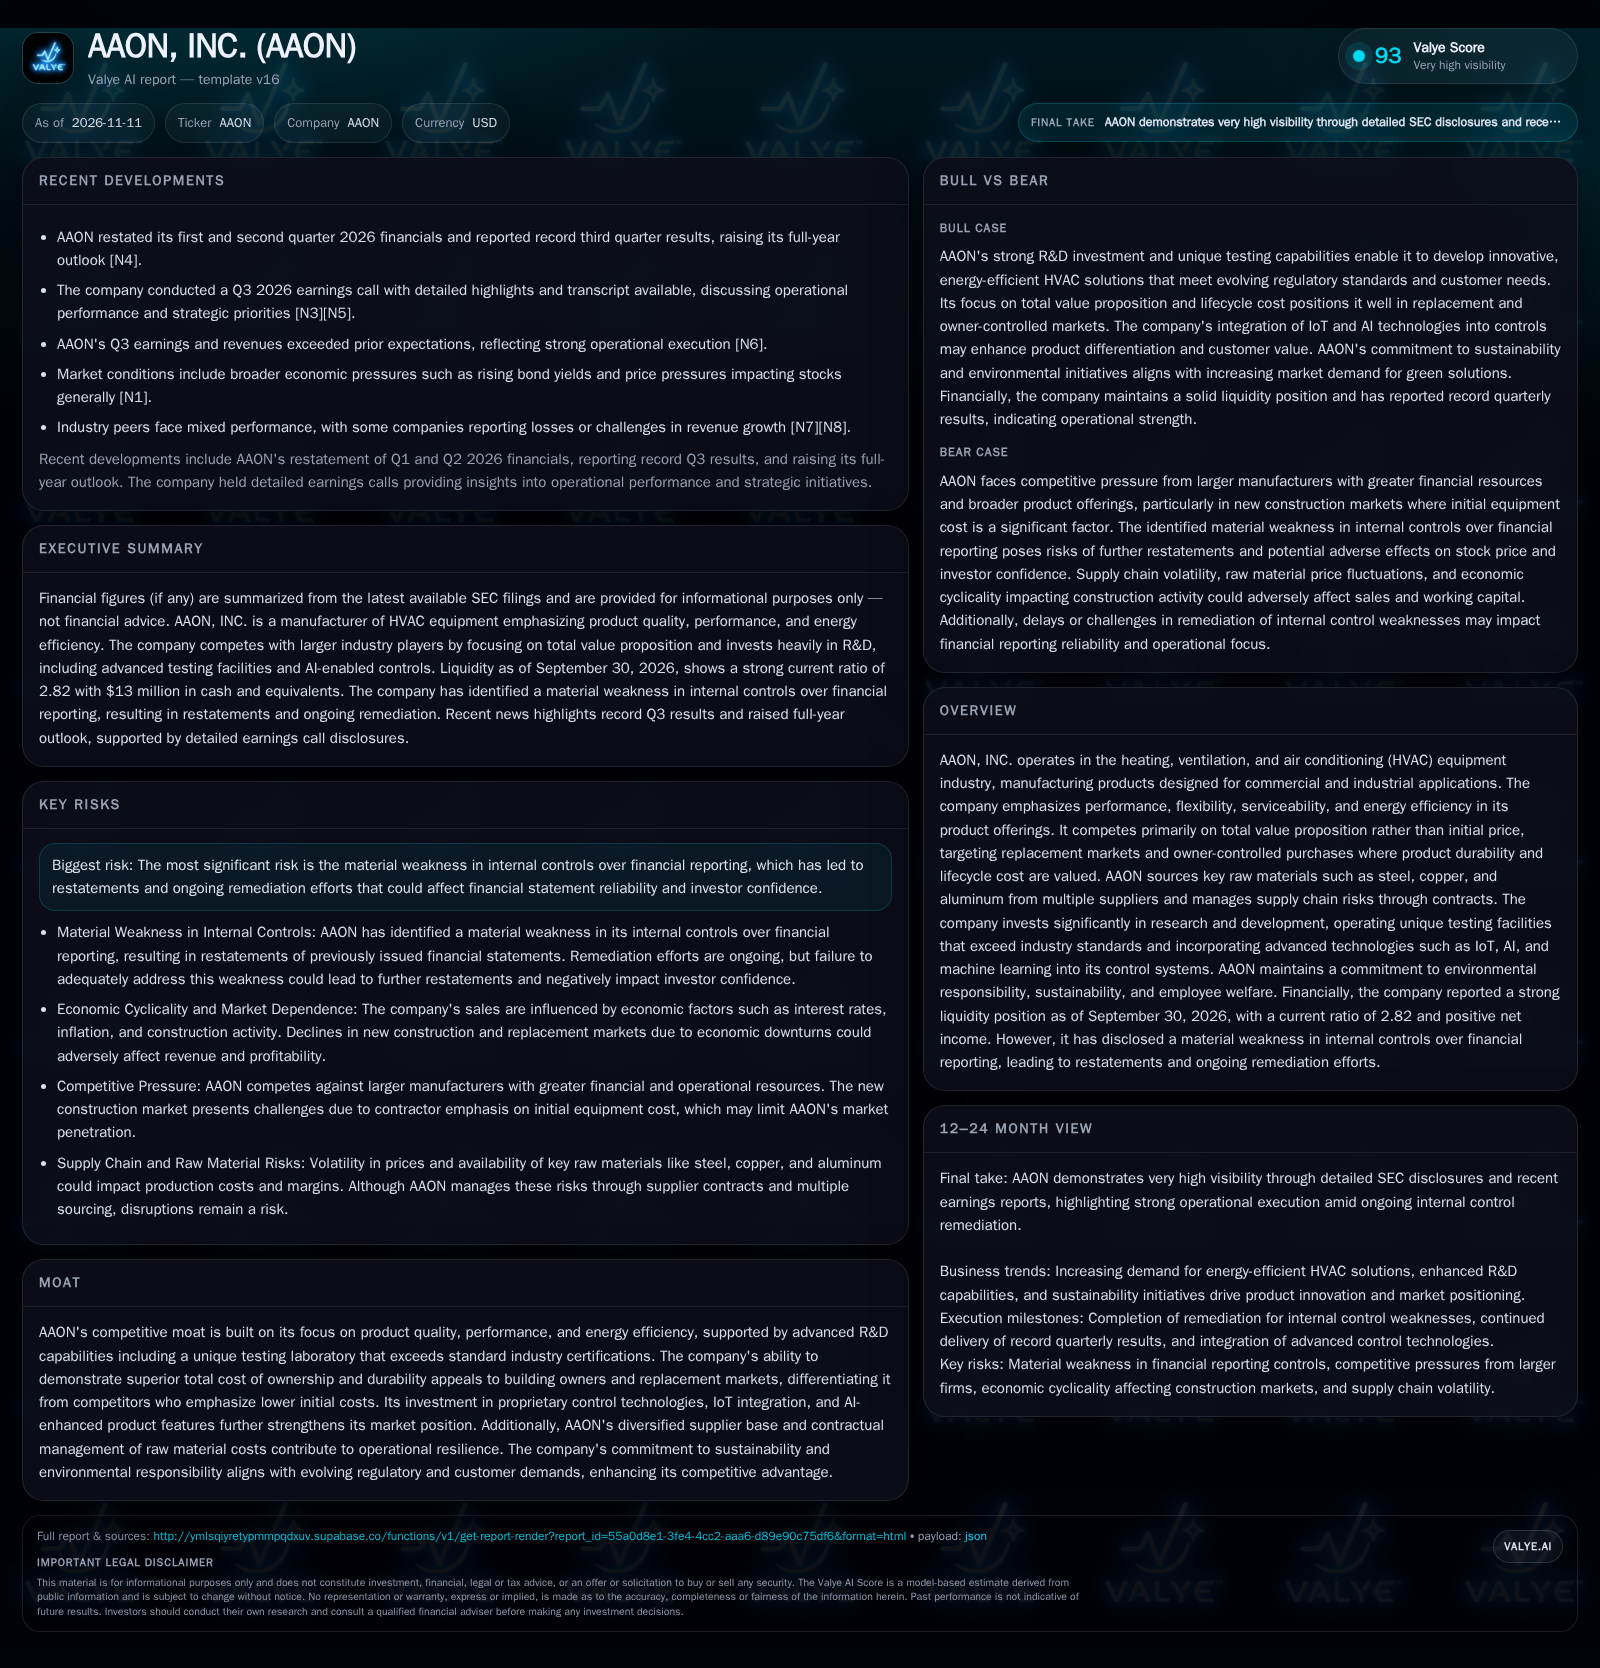
AAON delivered record Q3 results and raised its full-year outlook, underscoring strong operational execution and sustained demand for premium, energy-efficient HVAC solutions. However, a material weakness in internal controls led to restatements of prior financials, introducing uncertainty around reporting reliability and management focus. The company’s differentiation is rooted in advanced R&D, IoT, and AI integration, but competitive risks from larger incumbents and supply chain volatility remain significant. AAON’s ability to translate innovation and service into sustainable market share and margin expansion will be tested as it remediates controls and navigates industry headwinds. [N4] [N6]
AAON, INC. has emerged as a high-visibility contender in the commercial and industrial HVAC market, leveraging advanced R&D, proprietary testing, and a value-over-price strategy to win share in owner-driven and replacement segments. The company’s record Q3 2026 results and raised outlook signal robust demand and effective operational execution. However, a recently disclosed material weakness in internal controls—leading to restatements of prior quarters—casts a shadow over reporting reliability and raises the stakes for management’s remediation efforts. The next phase for AAON will hinge on its ability to sustain innovation-driven differentiation while restoring investor confidence and defending its premium positioning against much larger, resource-rich competitors. [N4] [N6]
Record Results Tempered by Internal Control Remediation
AAON reported record earnings for Q3 2026, exceeding expectations and prompting a raised full-year outlook—a clear sign of continued operational strength and market demand for its premium HVAC solutions. However, these positive developments were juxtaposed with the restatement of Q1 and Q2 2026 financials, following the identification of a material weakness in internal controls over financial reporting. Management is currently engaged in remediation, but the episode introduces uncertainty regarding the reliability of historical numbers and the focus required to resolve governance issues. [N4] [S2]
How AAON Converts Innovation and Service into Profitable Growth
AAON’s business model centers on manufacturing premium HVAC equipment for commercial and industrial applications, with a deliberate focus on performance, energy efficiency, and serviceability—attributes that command a higher total value proposition rather than competing solely on initial equipment cost. The company’s revenue mix is influenced by replacement cycles, owner-driven purchases, and product durability, which typically yield higher margins and lower price sensitivity compared to new construction markets dominated by low-bid contractors.
AAON invests substantially in research and development—$58.2 million in 2025—with a unique NAIC-accredited laboratory enabling it to test beyond standard industry benchmarks and accelerate product iteration. This R&D commitment supports the integration of IoT and AI into control systems, potentially unlocking future streams of software-enabled services or differentiated maintenance offerings, though the commercial structure of such offerings is not fully detailed in current disclosures.
Revenue recognition includes both standard sales and contracts recognized over time, supported by extended warranty offerings that smooth revenue and may provide recurring cash flow. The company manages raw material cost volatility through supplier contracts (six to 18 months), but is still exposed to swings in steel, copper, and aluminum prices. Operating leverage may be achieved through continuous improvement in production cycle times and inventory turnover, but working capital requirements fluctuate with demand, supplier schedules, and macroeconomic conditions. [S2]
Defending the Premium Niche in an Industry Dominated by Giants
AAON operates in a highly competitive HVAC landscape, facing formidable rivals such as Lennox, Trane, Carrier, and Daikin. These larger manufacturers possess deeper financial resources, broader product portfolios, and entrenched distribution channels, especially in new construction markets where initial equipment price is often the primary decision driver. AAON’s counter-positioning is to prioritize total cost of ownership, product durability, and advanced control features, targeting building owners and replacement customers who value long-term performance and serviceability.
The company’s proprietary R&D capabilities—including its advanced testing laboratory and patent portfolio (expiring 2032-2039)—are designed to support sustained differentiation in energy efficiency and control technology. Its early adoption of IoT and AI integration could create switching frictions for customers once embedded in building management systems, but the durability of this moat will depend on continued innovation and the ability to keep pace as industry leaders invest in similar technologies. The risk is that, over time, larger competitors may replicate or commoditize features that AAON currently markets as unique, eroding its premium positioning unless it can maintain a persistent edge in innovation and service.
If AAON’s Innovation and Control Remediation Translate to Sustainable Gains
The most favorable outcome for AAON would see it fully remediating its internal control weaknesses, restoring investor confidence and eliminating the distraction of financial restatements. With trust in reporting reestablished, the company could leverage its record Q3 momentum and raised outlook to capture greater share in the replacement and owner-driven segments, where lifecycle economics and energy regulations increasingly favor high-efficiency, smart-enabled systems.
Continued investment in R&D and successful commercialization of AI- and IoT-enabled controls could further differentiate AAON’s offerings, potentially opening new recurring revenue streams from software, predictive maintenance, or data services. If these advanced features become embedded in customer operations, AAON could see improved retention, higher average selling prices, and margin expansion. Confirmation of this upside would come from disclosures showing sustained revenue growth outpacing industry averages, margin improvements, increasing attachment rates for advanced controls or services, and evidence of successful control remediation such as clean audit opinions and absence of further restatements. [N4] [N6]
Maintaining Share and Margin in a Maturing, Competitive Market
A more probable outcome is that AAON continues to execute well in its chosen niche, maintaining moderate growth and solid margins as demand for energy-efficient retrofits and replacements persists. The company’s innovation engine and service focus allow it to defend share in owner-controlled and replacement markets, but gains are incremental rather than transformative as larger competitors adapt and regulatory tailwinds are absorbed into industry norms.
Internal control remediation proceeds on schedule, but the process absorbs management attention and may delay some strategic initiatives. While supply chain volatility and raw material pricing create short-term margin noise, AAON’s supplier contracts and planning discipline help dampen the impact. Performance in this scenario would be confirmed by steady, but not accelerating, revenue and profit growth, continued R&D outlays, and gradual normalization of financial reporting with no new material weaknesses disclosed.
When Control Failures and Competitive Pressure Undermine the Thesis
The principal risk is that AAON’s remediation of internal controls proves slower or less effective than expected, leading to further restatements, regulatory scrutiny, or erosion of investor confidence. This could distract management, constrain access to capital, or trigger customer hesitation—particularly in a sector where reliability and trust are paramount for long-term equipment investments.
Meanwhile, if larger HVAC manufacturers accelerate their own innovation cycles and undercut AAON’s value proposition, the company could face margin compression and lost share, especially if energy-efficient features become industry standard. Supply chain shocks or raw material price spikes would exacerbate these pressures, while any signs of macroeconomic weakness in construction or replacement cycles could further dampen demand. Downside confirmation would include additional restatements, auditor reservations, margin contraction, or loss of premium pricing power relative to peers.
What Could Prove or Disprove AAON’s Premium HVAC Thesis in 2027
Progress and final resolution of internal control remediation, including audit opinions and absence of new restatements.
Quarterly revenue growth versus broader HVAC industry benchmarks, particularly in the replacement and owner-driven segments.
Gross and operating margin trends, with attention to impact from raw material volatility and supply chain management.
Adoption rates and revenue contribution of AI- and IoT-enabled products and services—if disclosed.
R&D spending as a percentage of sales, and evidence of new patents or proprietary technology launches.
Customer retention rates and new customer wins in targeted owner-controlled markets—would help test the stickiness of AAON’s value proposition.
Any additional disclosures related to warranty claims, product reliability, or service costs, which could signal operational execution or quality challenges.
Updates on competitive responses from larger HVAC manufacturers, especially regarding feature parity or pricing pressure.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments