
Adaptive Biotechnologies: MRD Growth, Platform Leverage, and the Stakes in Immune Medicine Commercialization
Adaptive Biotechnologies is scaling its MRD business through expanding clinical adoption, payor coverage, and biopharma collaborations, while investing in its immune medicine platform to unlock diagnostic and therapeutic opportunities. The company’s ability to translate immune repertoire data into sustainable commercial products will determine the long-term value of its proprietary technology.
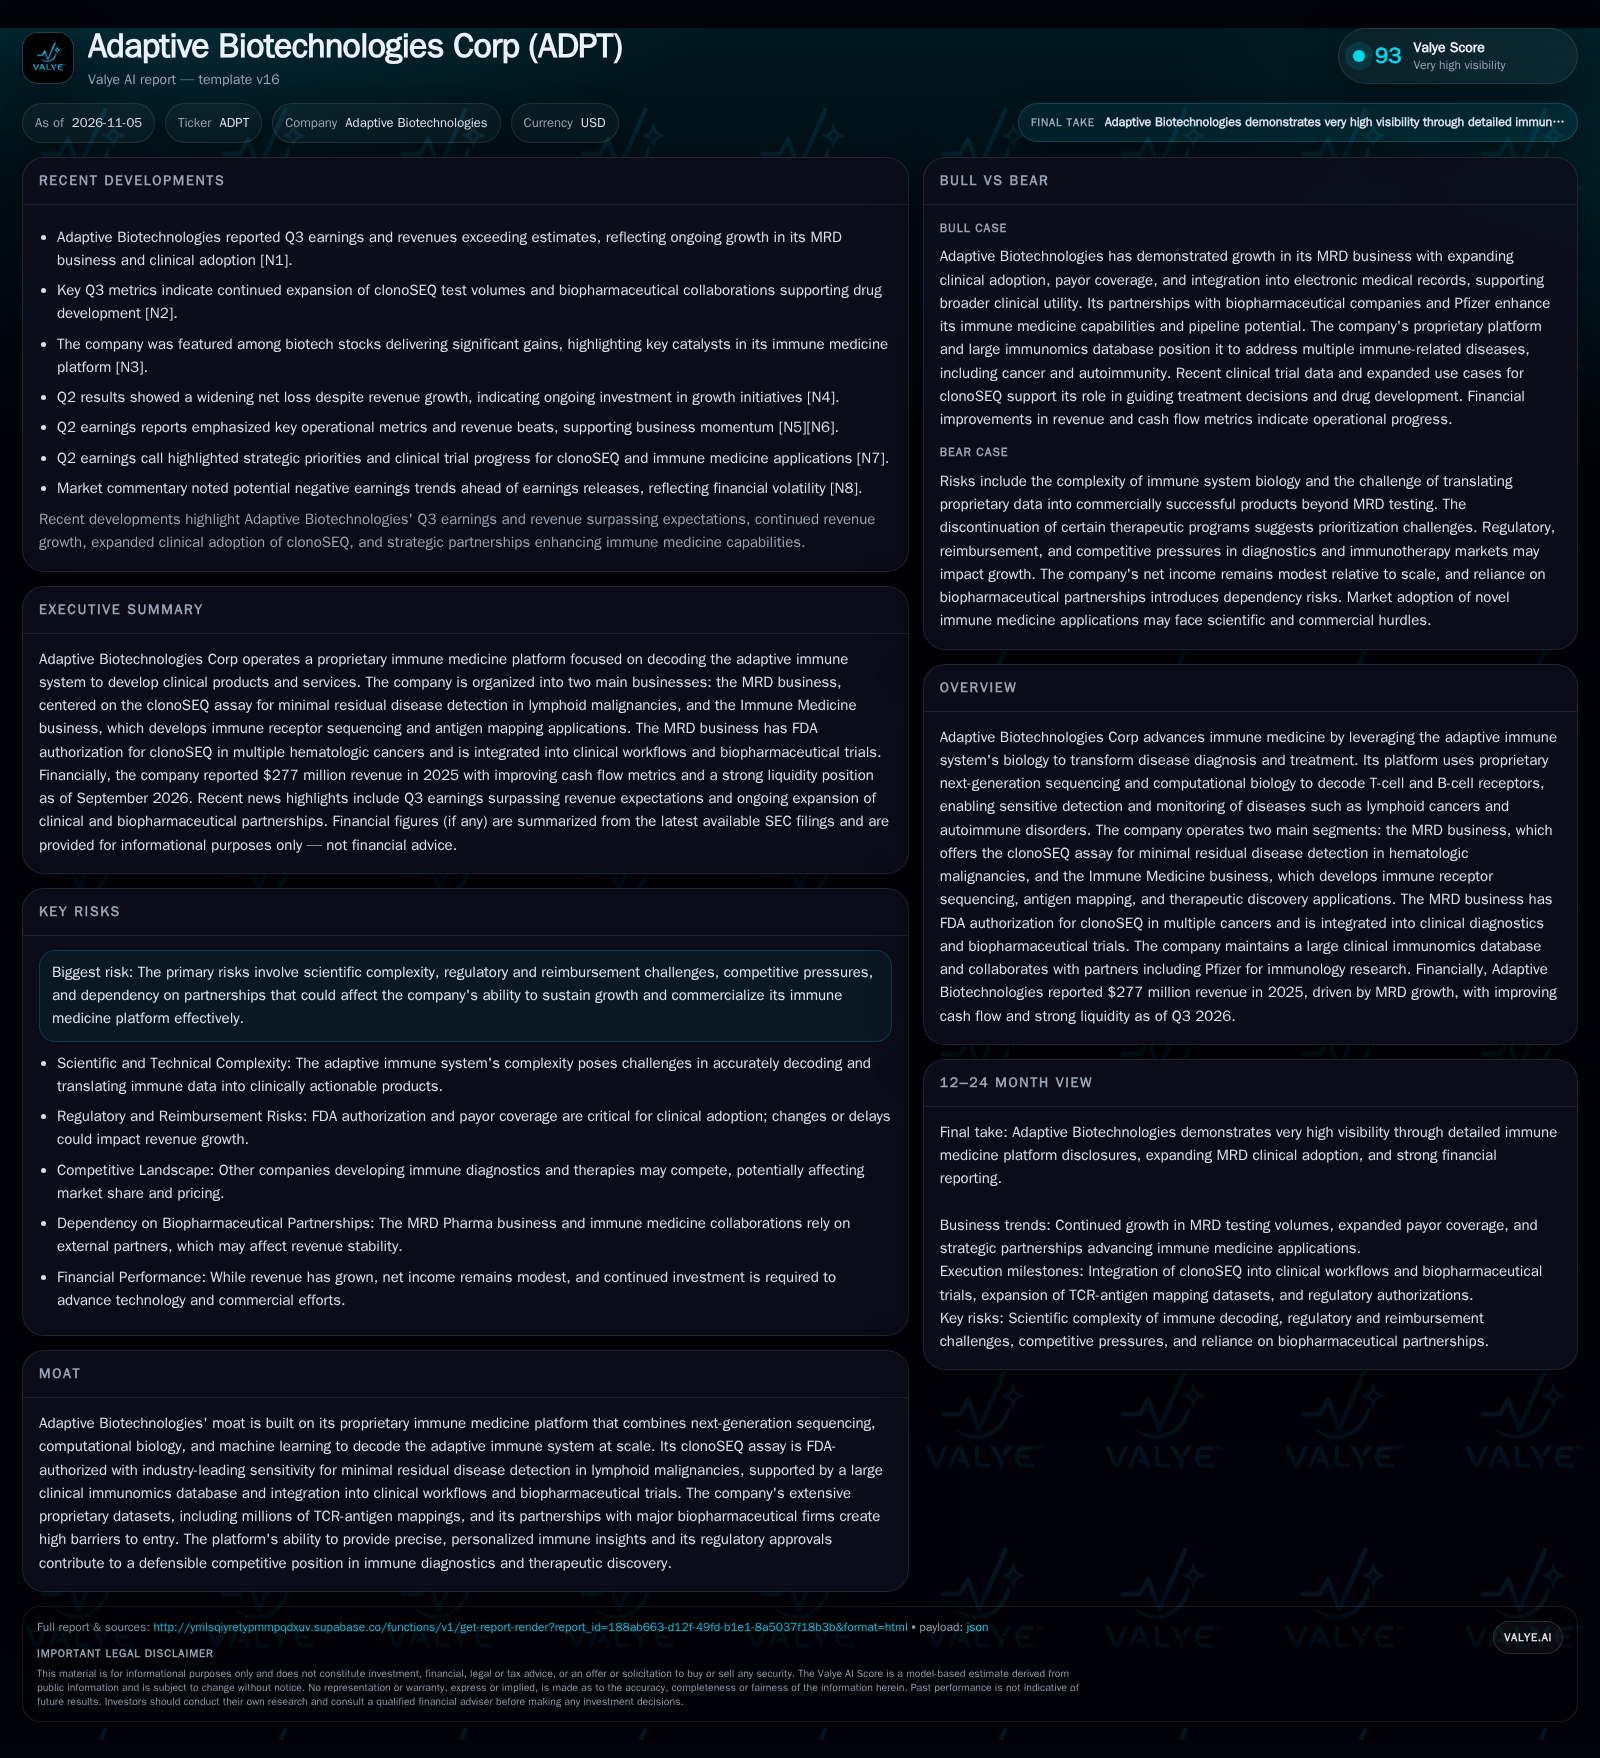
Adaptive Biotechnologies is executing on MRD testing expansion with strong payor coverage and clinical integration, driving revenue and narrowing cash burn. The company’s immune medicine platform, anchored by a vast TCR-antigen database and new pharma partnerships, positions it for broader applications, but the commercial pathway beyond MRD remains unproven. Key watchpoints include MRD test volume growth, IM business monetization, operating leverage, and the durability of biopharma collaborations. [S1] [S2]
Adaptive Biotechnologies is at a pivotal juncture, with its MRD business demonstrating accelerating clinical adoption, payor coverage, and revenue growth, while its immune medicine platform aspires to redefine diagnostics and therapeutics through immune repertoire sequencing. The company’s recent financials show improving operational efficiency and positive net income, but the sustainability of growth hinges on its ability to extend commercial success beyond MRD testing. The evolving relationship with biopharmaceutical partners and the translation of its immunomics database into new revenue streams will be critical determinants of Adaptive’s long-term trajectory. [S1] [S2]
MRD Expansion, Financial Inflection, and Immune Medicine Platform Momentum
Three recent developments stand out for Adaptive Biotechnologies: First, the MRD business drove a sharp rise in 2025 revenue to $277 million, with clonoSEQ test volumes up 39% to 105,587 tests. This indicates broadening clinical adoption and demand for minimal residual disease monitoring in hematologic malignancies. Second, payor coverage for clonoSEQ expanded to over 300 million lives in acute lymphoblastic leukemia and multiple myeloma, with substantial coverage in CLL and DLBCL, and Medicare coverage for recurrence monitoring in mantle cell lymphoma. This breadth of reimbursement lays the foundation for routine clinical use and sustained volume growth. Third, the company reported its first quarter of positive net income ($2.88 million) in Q3 2026, with a current ratio of 3.97 and cash and equivalents of $75.6 million, reflecting improved operating discipline and a narrowing cash burn. Collectively, these facts suggest that Adaptive is achieving operating leverage in its core MRD business, while its immune medicine platform continues to expand its database and pharmaceutical collaborations, as evidenced by new agreements with Pfizer. [S1] [S2]
How Adaptive Converts Immune Data into Revenue—And Where the Operating Leverage Lies
Adaptive’s core business model monetizes proprietary sequencing of T- and B-cell receptors for both clinical diagnostics (primarily MRD testing via clonoSEQ) and research/partnering (immune medicine). The MRD segment benefits from a high-mix, high-volume clinical testing model: as patient access expands through payor coverage and EMR integration, incremental test volumes can drive substantial operating leverage given fixed platform costs and automation in processing. The cost structure is characterized by significant upfront investment in R&D and regulatory compliance, with gross margins potentially expanding as test throughput increases and reimbursement rates stabilize.
The Immune Medicine business, in contrast, is still in the early stages of monetization. Its revenue streams include immune receptor sequencing for research, data licensing, and target discovery partnerships. These are often milestone- or usage-based, and may fluctuate with the pace of pharmaceutical R&D cycles. The economics here are less predictable: the value of each partnership (such as the Pfizer agreements) can be substantial if it leads to novel target discovery or therapeutic validation, but the business is sensitive to project success rates and the negotiation of revenue-sharing or licensing terms.
Long term, Adaptive’s ability to generate recurring, high-margin revenue from its immunomics database—by enabling companion diagnostics, drug development, and potentially direct therapeutics—will determine whether it transitions from a diagnostics company to a broader immune medicine platform. This shift could require additional capital for clinical trials, regulatory submissions, and commercial infrastructure, particularly if it pursues therapeutic programs in-house.
Defensibility in MRD and the Challenge of Platform Extension
Adaptive’s competitive advantages in MRD stem from several factors: FDA authorization of clonoSEQ for multiple cancer indications, integration into major EMR systems (including 173 Epic sites), and broad payor coverage. These create switching frictions for clinicians and institutions, supporting recurring test volumes and embedding clonoSEQ into standard care protocols. The company’s proprietary NGS-based platform, with sensitivity to 1 in 1,000,000 cells, offers technical differentiation over some traditional flow cytometry and PCR-based MRD assays.
In the Immune Medicine domain, Adaptive’s moat is built on its large-scale TCR-antigen mapping database (over 5 million pairs), proprietary sequencing and computational technologies, and established collaborations with leading biopharma firms. However, the field is highly competitive: other diagnostics and platform genomics companies are pursuing immune profiling, multi-omic diagnostics, and AI-driven target discovery. Barriers to entry include the scale and curation of immune datasets, regulatory approvals, and clinical validation, but the threat of technology substitution is real as new sequencing modalities, machine learning approaches, or cell-based assays emerge.
Adaptive’s dependency on biopharma partners introduces risk: while these relationships can accelerate platform validation and provide non-dilutive funding, they expose the company to the budget cycles and strategic priorities of external parties. Success in the next phase will depend on Adaptive’s ability to move from partner-driven projects to direct clinical and commercial products in new indications.
If the Platform Unlocks New Diagnostics or Therapies: What Would It Look Like?
The most favorable scenario for Adaptive sees sustained MRD volume growth, further payor expansion, and margin improvement as clonoSEQ becomes the entrenched standard of care for lymphoid malignancies and potentially expands into new cancer types. Meanwhile, the Immune Medicine business successfully translates its TCR-antigen mapping into new diagnostic tests for autoimmune conditions or infectious diseases, or enables high-value therapeutic partnerships (e.g., companion diagnostics for immunotherapy, or proprietary target discovery leading to out-licensing or co-development deals).
Confirmation of this scenario would require evidence of: (1) ongoing double-digit MRD test volume growth and new FDA authorizations; (2) new clinical launches or commercial partnerships in the IM business, with disclosed revenue contributions or milestones from partners like Pfizer; (3) continued improvement in operating leverage, with expanding gross margins and positive free cash flow; and (4) the announcement of new products or platforms (such as TCR-based diagnostics or therapeutics) achieving regulatory or commercial milestones.
Falsification would occur if MRD volume growth stalls or reimbursement erodes, or if the IM business remains confined to low-revenue research services without producing independent commercial products or meaningful partnership economics.
MRD Drives Reliable Growth, But Platform Leverage Remains a Longer-Term Bet
The most plausible outcome is that Adaptive’s MRD business continues to deliver steady revenue growth and improving margins, leveraging its regulatory approvals, payor coverage, and EMR integration to deepen penetration in existing hematologic malignancy markets. Incremental growth may come from the adoption of MRD as a clinical endpoint in pharmaceutical trials and potential expansion into adjacent cancer indications. The IM business, while rich in data and partnerships, likely remains a modest contributor to revenue in the medium term, with milestone payments and research collaborations offsetting ongoing R&D spend but not yet transforming the company’s financial profile.
Evidence supporting this view would include consistent quarterly MRD test volume increases, stable or growing reimbursement rates, ongoing cash discipline, and periodic partnership announcements from the IM business without a step-change in revenue contribution. The scenario is challenged if MRD adoption plateaus due to competitive dynamics, reimbursement headwinds, or clinical guideline changes, or if the IM business fails to generate new high-value partnerships over several reporting cycles.
If MRD Adoption Slows or Partnerships Falter: How the Thesis Could Be Disrupted
The primary risk is that MRD testing volumes plateau or decline due to competitive encroachment, reimbursement cuts, or reduced clinical guideline support. In this event, Adaptive’s fixed-cost base could result in margin compression and a return to negative operating cash flow. Simultaneously, if biopharma partnerships in the IM business do not convert into recurring revenue or new product launches, the company may be forced to scale back R&D or raise additional capital to sustain operations.
This scenario would be confirmed by flat or declining MRD test volumes, reductions in payor coverage, deteriorating gross margins, or disclosure of lost or diminished partnerships (e.g., project discontinuations or non-renewal of key agreements). Early signals might include a reversal of recent cash flow improvements, a return to net losses, or management guidance signaling lower expectations for IM monetization.
Milestones That Will Determine Whether Adaptive’s Platform Can Deliver Durable Value
Quarterly MRD test volume growth, segmented by indication (e.g., ALL, MM, CLL, DLBCL), to assess ongoing clinical adoption and market penetration. [S1] [S2]
Updates on payor coverage breadth and reimbursement rates, especially for new indications or geographies; a useful metric would be the proportion of covered lives relative to total addressable market. [S1]
Number and value of new or expanded biopharma partnerships in the Immune Medicine business, particularly those with disclosed milestone or royalty economics. [S1]
Progress on regulatory submissions and new FDA authorizations for clonoSEQ or other diagnostic products; announcements of successful clinical validation would help test the expansion thesis. [S1]
Gross margin trends and operating cash flow, as evidence of sustainable operating leverage in the MRD business. [S1] [S2]
Disclosure of revenue or milestone payments attributed to IM business products or partnerships, especially those that diversify revenue beyond MRD. If disclosed, this would clarify the commercial impact of the platform.
Clinical or commercial launches of novel diagnostics or therapeutics enabled by Adaptive’s platform; announcements of first-in-class approvals or companion diagnostic designations would be pivotal.
Retention or expansion of integration with major EMR systems (e.g., Epic), as a proxy for embeddedness in clinical workflows and switching friction.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments