
Affirm’s Transaction-Level Risk Engine and Ecosystem Expansion: Stakes and Scenarios in Pay-Over-Time Finance
Affirm Holdings, Inc. leverages proprietary AI-driven underwriting and network effects across a vast merchant-consumer ecosystem to scale its pay-over-time platform, but faces intensifying competition and the need for risk model resilience as it balances profitability with growth.
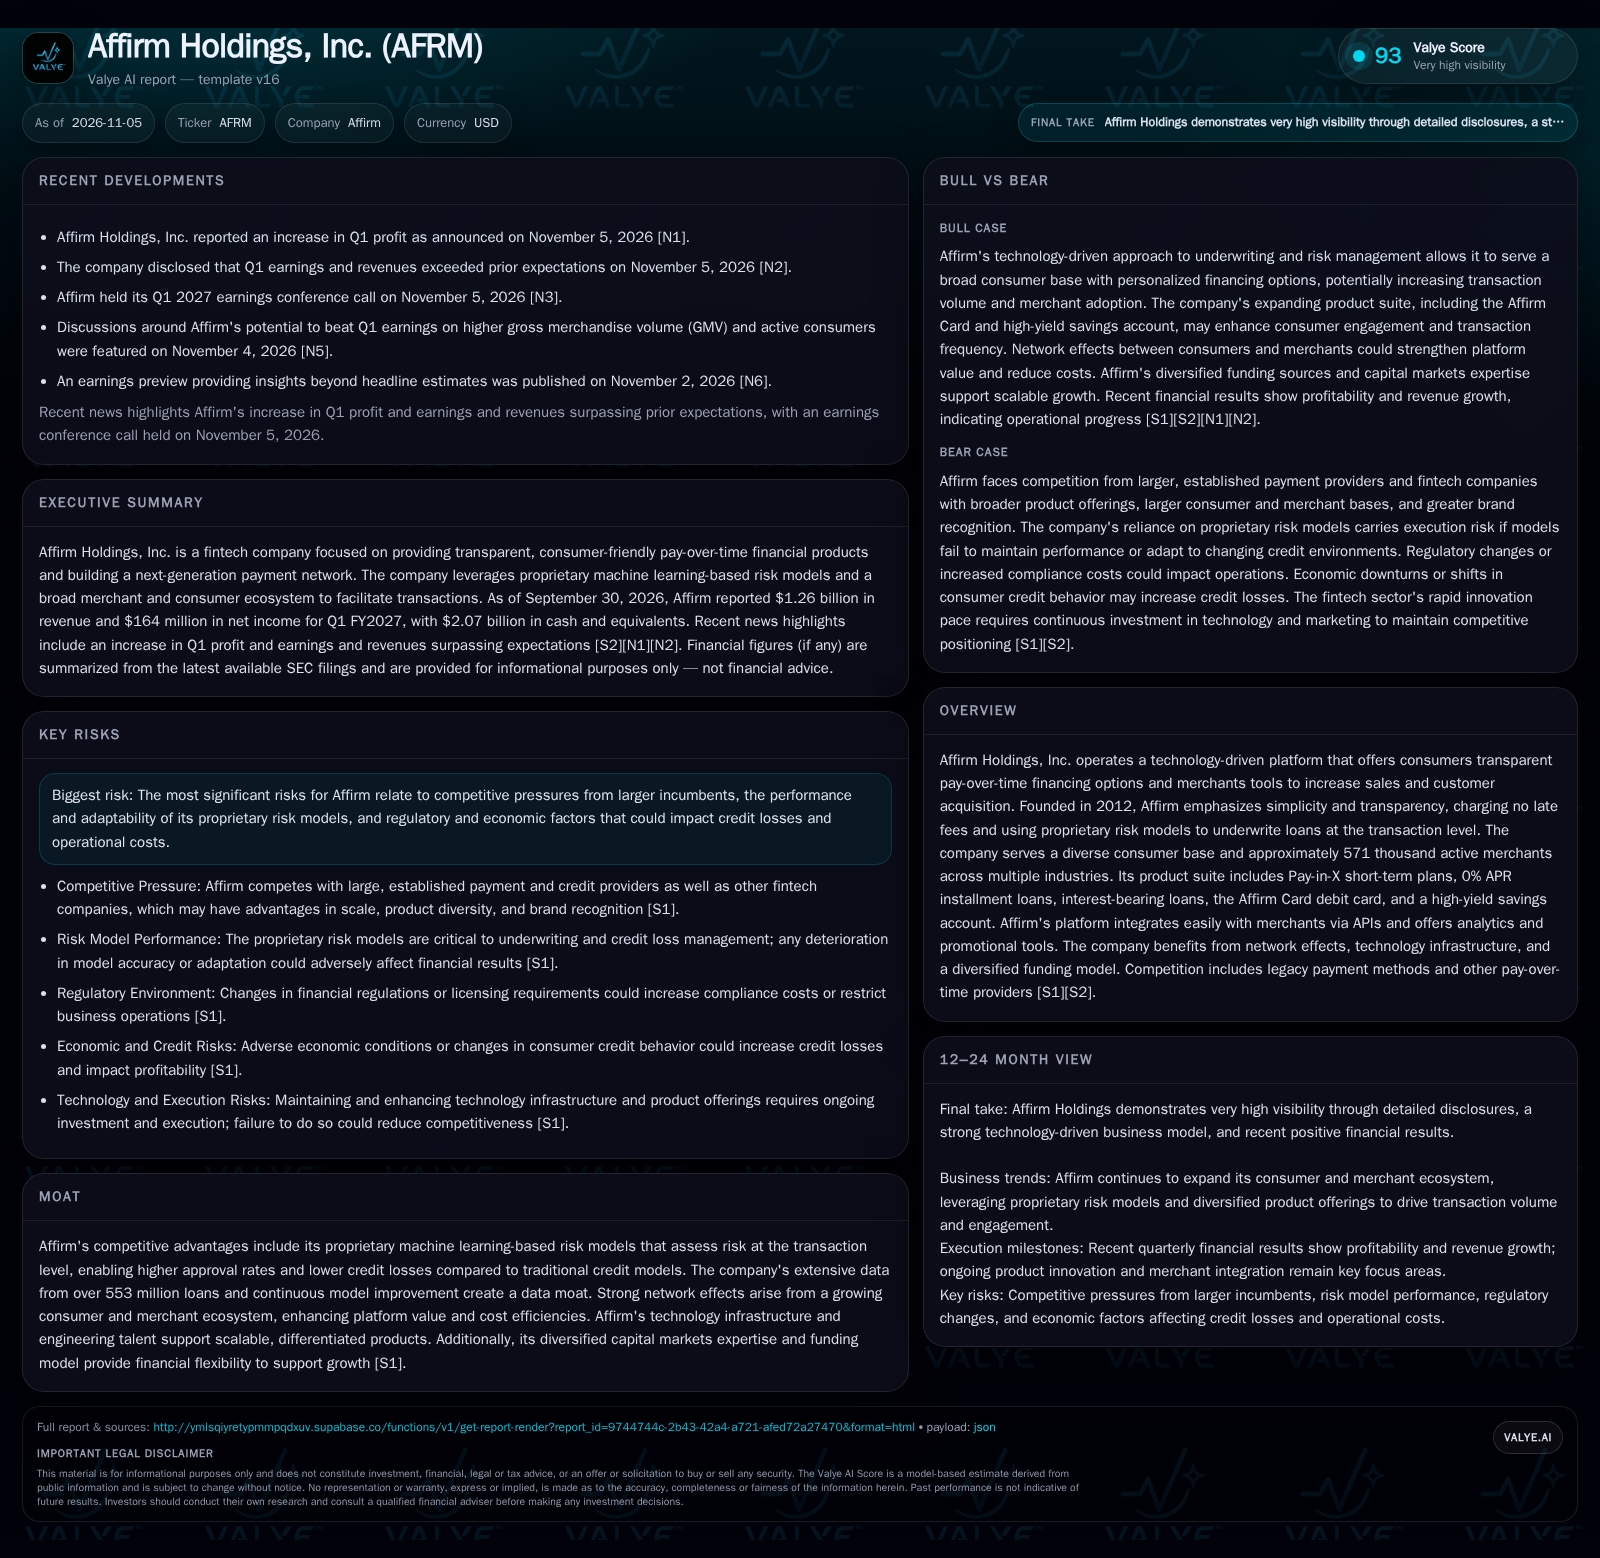
Affirm reported $1.26 billion in revenue and $164 million in net income for Q1 FY2027, fueled by $50.2 billion in annual GMV and a merchant network exceeding 570,000. Its platform’s strength lies in data-driven risk assessment, diverse loan products, and a two-sided network, but the stakes rise as rivals accelerate, economic volatility tests credit models, and regulatory scrutiny looms. The company’s ability to sustain profitable growth depends on maintaining underwriting edge, deepening merchant relationships, and adapting to evolving consumer behavior.
Affirm Holdings, Inc. stands at a pivotal moment in the evolution of consumer finance, scaling a platform that combines transaction-level AI underwriting with a rapidly expanding merchant-consumer ecosystem. Its Q1 FY2027 results reflect both momentum and the rising complexity of managing risk, regulatory exposure, and intensifying competition. As Affirm deepens its product suite and merchant integrations, the company’s future hinges on its ability to maintain underwriting discipline, leverage network effects, and respond to shifting market and regulatory dynamics.
Affirm’s Latest Financial Performance Highlights Profitable Growth Amid Strategic Uncertainties
Affirm reported revenue of $1.26 billion and net income of $164 million for the quarter ended September 30, 2026, translating to a diluted EPS of $0.47 [S2]. This profitability milestone follows a period of rapid expansion, with GMV reaching $50.2 billion for the fiscal year ended June 30, 2026 [S1]. The merchant network now encompasses approximately 571,000 active partners across diverse industries [S1]. These results confirm that Affirm’s business model has reached significant operational scale and can deliver positive bottom-line results, at least in the current credit environment.
Interest-bearing installment loans accounted for 70% of GMV, while 0% APR and Pay-in-X products made up 14% and 16%, respectively [S1]. This mix highlights Affirm’s evolving positioning between consumer affordability and yield generation. The company’s risk infrastructure—anchored by proprietary models trained on over 553 million loans—remains central to both growth and financial stability [S1].
While Q1 profit and revenue exceeded expectations [N1] [N2], the challenge is whether Affirm’s underwriting edge and network advantages can persist as competitors scale up and as macroeconomic or regulatory conditions shift.
Revenue Streams and Margin Challenges Within Affirm’s Platform Model
Affirm’s economics are anchored in two primary revenue streams: merchant fees and consumer interest income. Merchant fees are earned on each transaction, with higher fees typically associated with 0% APR and Pay-in-X products, as merchants subsidize financing to drive conversion and basket size [S1]. Interest income is generated from longer-term, interest-bearing installment loans, which represented the majority of GMV in FY2026 [S1].
Operating leverage is possible as Affirm’s technology, risk, and onboarding costs are largely fixed or semi-variable, while incremental transaction volume adds revenue with comparatively lower marginal cost. However, loan funding and credit loss provisions are meaningful variable costs that scale with volume. Affirm’s diversified funding model—including warehouse lines, securitizations, and loan sales—offers flexibility but exposes the company to capital markets cycles and potential shifts in funding cost [S1].
The Affirm Card introduces an interchange-driven revenue stream, but its profitability depends on consumer adoption, transaction mix, and the ability to cross-sell financing at the point of sale. The high-yield savings account (Affirm Money Account) could serve as a low-cost funding source and deepen consumer relationships, but also introduces regulatory and margin tradeoffs.
The fundamental tension is between maximizing merchant and consumer adoption (which may require lower fees and higher approval rates) and maintaining credit quality and margins—especially as Affirm expands into broader segments of the credit spectrum.
Affirm’s Competitive Moat: Network Effects and Data Advantages Under Pressure
Affirm’s competitive position is built on a two-sided network: as more merchants join, the platform becomes more attractive for consumers, and vice versa. This network effect can increase switching costs, particularly for merchants integrated via APIs and for consumers who benefit from Affirm’s transparency and flexible payment options [S1].
The proprietary risk models, trained on an ever-growing dataset, underpin Affirm’s underwriting edge. Theoretically, this data moat improves credit selection and loss forecasting, enabling higher approval rates and lower fraud relative to traditional credit models [S1]. However, the durability of this advantage depends on continued model refinement and the absence of sudden regime shifts in consumer credit behavior.
Affirm faces entrenched competition from legacy credit cards, mobile wallets, and other pay-over-time providers such as PayPal, Block, and Klarna, as well as proprietary merchant financing solutions [S1]. Many of these competitors have greater brand recognition, deeper pockets, and broader product ecosystems. Additionally, barriers to merchant switching may be lower than in traditional payments if integration and settlement standards converge or if merchants seek to avoid over-reliance on a single provider.
The risk is that Affirm’s network effects and data advantages are not insurmountable moats, especially if rivals match or exceed its underwriting and integration capabilities, or if regulatory changes level the playing field.
Conditions for Affirm to Establish Dominance in Pay-Over-Time Financing
The most bullish outcome for Affirm is a scenario in which its proprietary risk models continue to outperform competitors, enabling high approval rates and low credit losses across cycles. This would allow Affirm to serve a broader swath of consumers without compromising unit economics, driving further merchant adoption and reinforcing network effects.
In this scenario, the Affirm Card achieves mass adoption, becoming a top-of-wallet payment method and funneling more consumer spend through Affirm’s ecosystem. The high-yield savings account deepens relationships and provides a stable, low-cost funding base, reducing dependence on external capital markets.
Affirm’s product suite could expand into adjacent financial services, leveraging its data and technology infrastructure to cross-sell insurance, personal loans, or even wealth products, further increasing lifetime value per user.
Evidence that would confirm this scenario includes: sustained improvement in credit loss rates relative to peers, rapid growth in both merchant and consumer adoption metrics, rising share of wallet among existing users, and a demonstrable decline in funding cost volatility. A falsification would be any sign of rising credit losses or declining merchant/consumer engagement despite overall GMV growth.
Affirm’s Position as a Strong Competitor in a Crowded Pay-Over-Time Market
The most plausible outcome is that Affirm maintains its position as a leading independent pay-over-time platform, but faces margin pressure and slower growth as competition intensifies and as the market matures. Its risk models remain effective but are matched by improvements from rivals, leading to a gradual convergence in approval, loss, and pricing metrics.
Affirm continues to grow GMV in line with or slightly ahead of the broader pay-over-time market, but merchant fee rates and interest spreads compress as both merchants and consumers become more price-sensitive. The Affirm Card and Money Account gain traction among a segment of users but do not become mainstream payment or savings vehicles.
Funding remains accessible but subject to broader credit market conditions, requiring Affirm to maintain prudent balance-sheet management. Regulatory scrutiny increases, but Affirm adapts without major business model disruption.
Confirmation of this scenario would include stable or modestly improving credit and operating metrics, steady but not explosive growth in GMV and active users, and margin compression offset by operating leverage. Falsification would be a significant drop in market share, inability to access funding, or regulatory changes that materially alter Affirm’s economics.
Risks from Credit Fluctuations and Regulatory Changes That Could Undermine Affirm’s Model
The bear case for Affirm is driven by a combination of deteriorating credit conditions, regulatory tightening, and competitive displacement. If macroeconomic shocks or changes in consumer credit behavior undermine the predictive power of Affirm’s risk models, credit losses could spike, forcing higher provisions and stricter underwriting that reduce approval rates and merchant appeal.
Simultaneously, if regulators impose new requirements on pay-over-time lending—such as APR caps, tighter disclosure rules, or increased capital requirements—Affirm’s business model could become less profitable or more operationally complex.
Competition from larger payment networks or banks could erode Affirm’s merchant and consumer base, especially if those rivals bundle financing with broader financial services or subsidize rates through cross-subsidization.
This scenario would be confirmed by a sharp and sustained rise in net charge-offs, declining GMV or active user counts, merchant defections, or regulatory actions that directly impact Affirm’s product economics or approval processes.
Critical Developments Influencing Affirm’s Long-Term Platform Success
Quarterly trends in net charge-off and delinquency rates—any significant deterioration would test the resilience of Affirm’s risk models and underwriting discipline.
Growth or contraction in active merchants and active consumers—sustained increases would indicate strengthening network effects, while stagnation or decline could signal competitive losses.
GMV per merchant and per consumer—rising figures would suggest deeper engagement and wallet share, whereas declines may point to commoditization or competitive leakage.
Adoption rates and transaction volume for the Affirm Card—if disclosed, this would help gauge the platform’s ability to extend beyond point-of-sale financing into everyday spend.
Interest rate spreads and merchant fee yields—compression would indicate competitive and regulatory pressure, while stability or expansion would support margin durability.
Funding cost and capital market access—volatility or tightening could constrain growth or increase risk, especially during credit market stress.
Regulatory developments—new rules on pay-over-time lending, consumer disclosures, or capital requirements could materially affect Affirm’s economics.
Rate of product innovation and new feature adoption—evidence of rapid rollout and uptake would reinforce Affirm’s technology and ecosystem advantage.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments