
AdaptHealth Refocuses on Sleep and Respiratory Segments Amid Profitability and Supply Chain Headwinds
With the divestiture of its Diabetes Health unit and renewed focus on Sleep and Respiratory Health, AdaptHealth is doubling down on higher-growth, higher-complexity segments. Yet persistent net losses, supplier concentration, and regulatory burdens may constrain the company’s ability to translate scale and technology investments into durable margin improvement.
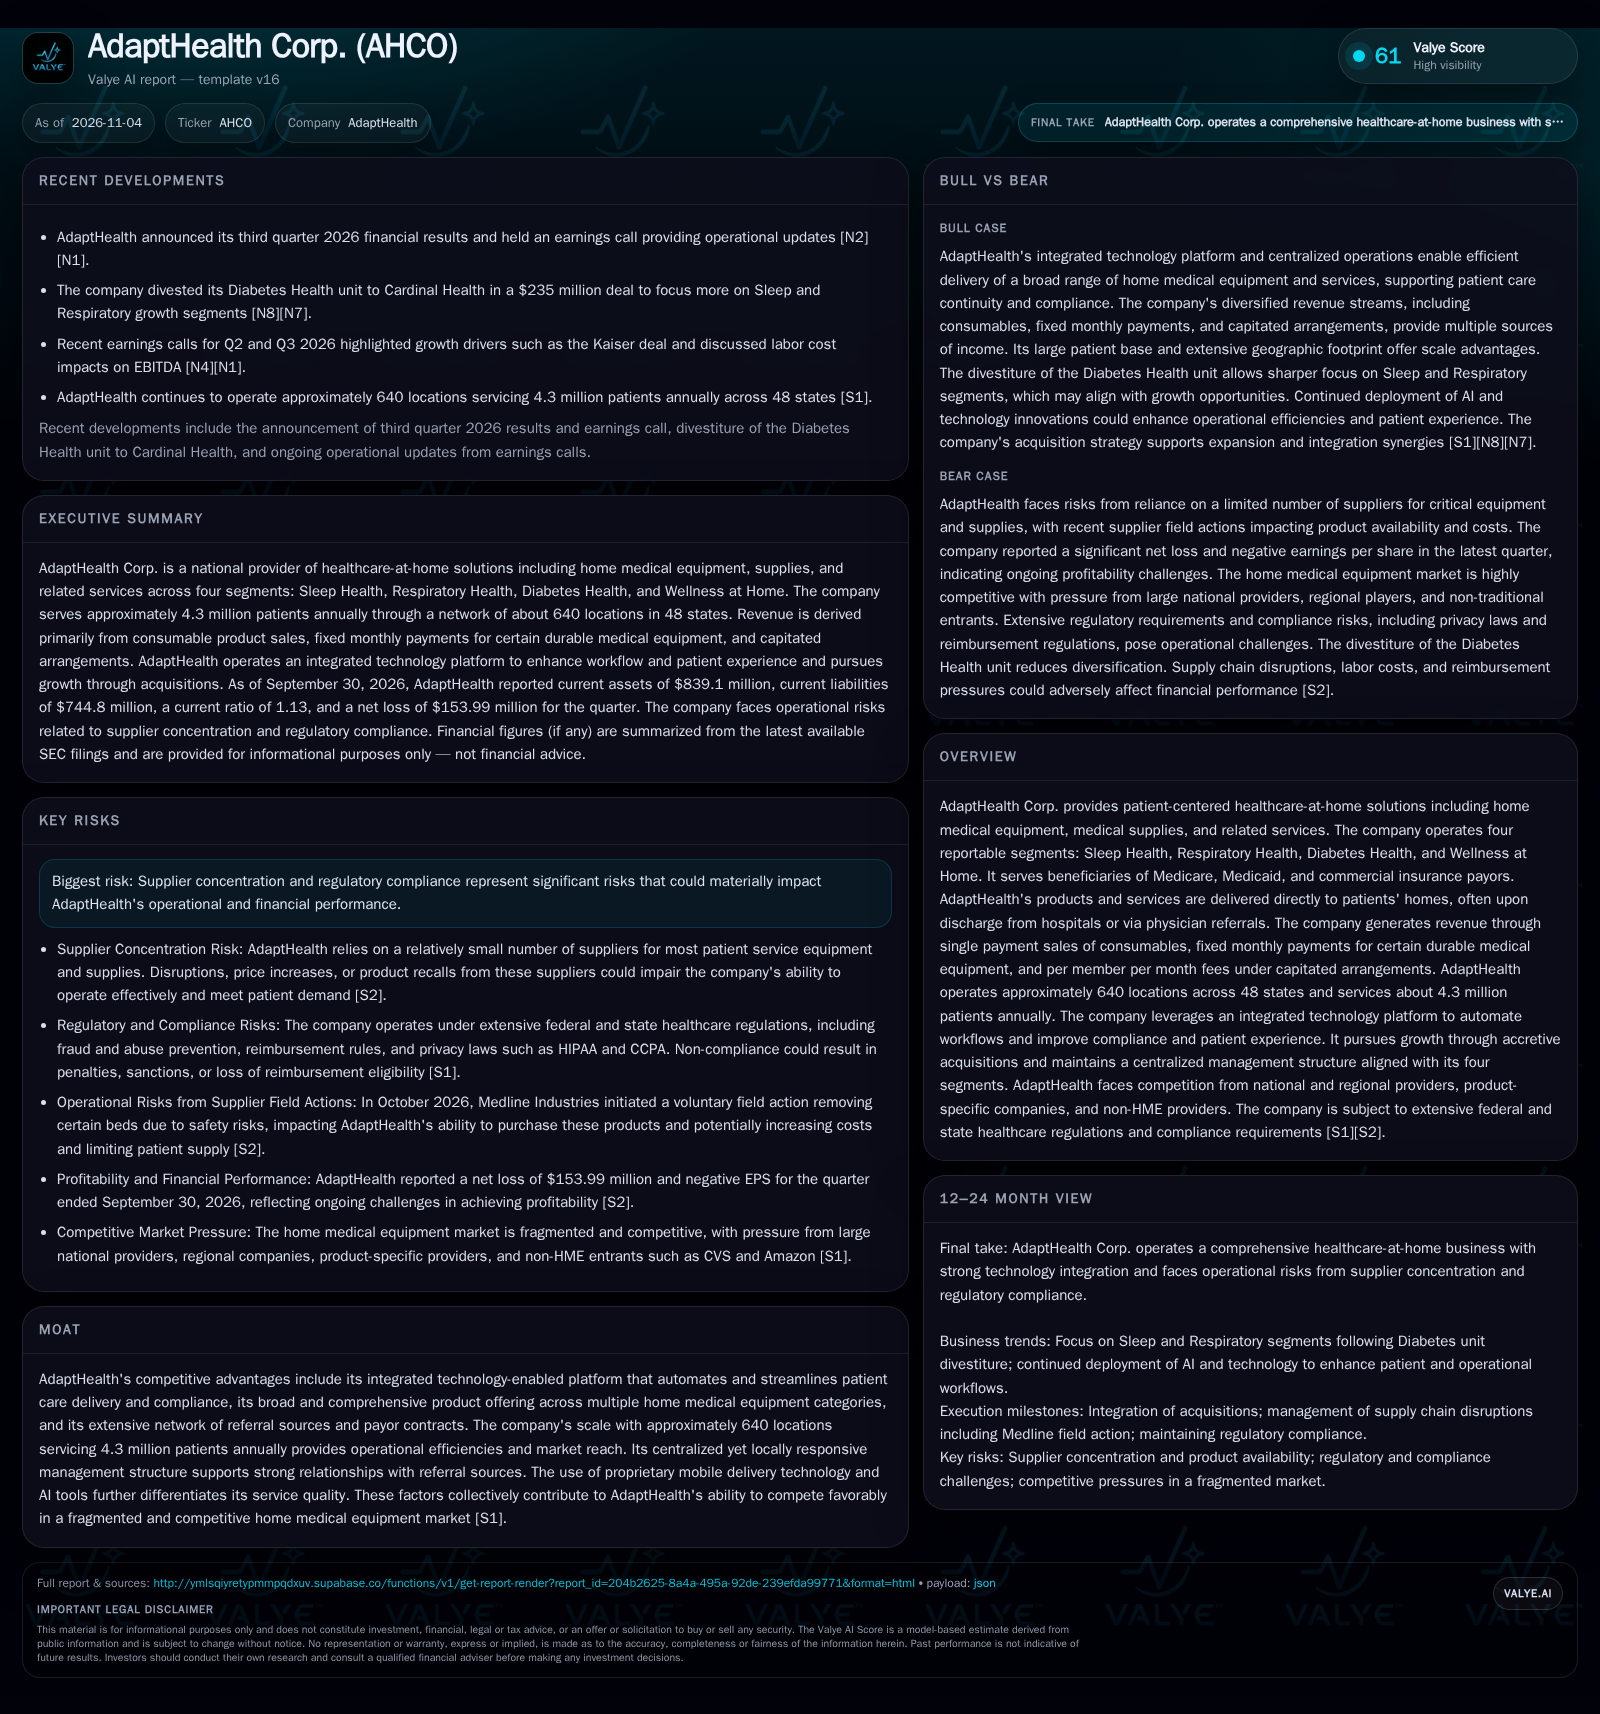
AdaptHealth has divested its Diabetes Health unit for $235 million to sharpen its focus on Sleep and Respiratory Health. Despite serving 4.3 million patients through 640 locations, the company reported a $153.99 million net loss for Q3 2026. Supplier disruptions and compliance demands remain significant risks, while the strategy now hinges on operational discipline, acquisition integration, and leveraging its technology platform for efficiency and growth [S2] [N8].
AdaptHealth Corp. is at a strategic crossroads following the divestiture of its Diabetes Health unit, which netted $235 million and positions the company to concentrate on Sleep and Respiratory Health—segments with potentially higher complexity and reimbursement upside. However, the company’s Q3 2026 net loss of $153.99 million underscores persistent profitability challenges. With a vast national footprint and an integrated technology platform, AdaptHealth aims to drive workflow automation and compliance, but faces significant risks from supplier concentration, regulatory complexity, and a fiercely competitive home medical equipment market. The question is whether increased focus and operational discipline can produce sustainable margin improvement in the face of these structural headwinds.
Pivot to Sleep and Respiratory: Recent Moves and Their Strategic Implications
The most consequential recent action by AdaptHealth is the divestiture of its Diabetes Health unit to Cardinal Health for $235 million, a move that allows management to redeploy attention and resources toward the Sleep and Respiratory Health segments [N8]. This strategic narrowing follows a period of ongoing net losses, including a $153.99 million net loss in Q3 2026 [S2]. The company continues to operate about 640 locations, servicing 4.3 million patients annually, but now with a more concentrated portfolio [S1]. Meanwhile, supplier disruptions—such as Medline’s October 2026 recall of certain beds—have impacted product availability and may increase costs [S2]. These facts highlight both the scale of AdaptHealth’s operations and the immediate operational and financial pressures it faces.
How AdaptHealth’s Revenue Mix and Cost Structure Shape Its Margin Potential
AdaptHealth’s business model is built on a mix of single-payment consumable sales, fixed monthly payments for durable medical equipment (DME), and capitated per-member-per-month arrangements. Consumables typically offer stable, repeatable revenue but with lower margins, while DME and capitated contracts can provide steadier cash flow and potentially higher margins if managed efficiently. The company’s large patient base enables some purchasing leverage and operating scale, yet the highly regulated nature of reimbursement—especially from Medicare and Medicaid—limits pricing flexibility.
Labor, logistics, and regulatory compliance are substantial fixed costs. The integrated technology platform is designed to automate workflows, streamline billing, and improve patient compliance, which could drive operating leverage if volumes grow faster than costs. However, recent net losses suggest that fixed costs and margin pressures—possibly from labor inflation, supply chain disruptions, and reimbursement headwinds—are currently outpacing any efficiency gains. The divestiture of the Diabetes Health unit removes a source of revenue diversification, increasing exposure to the idiosyncratic risks of the remaining segments.
Scale, Tech Integration, and the Limits of Advantage in a Fragmented HME Market
AdaptHealth’s competitive position is underpinned by its scale (servicing 4.3 million patients annually across 640 locations) and its integrated technology platform, which supports workflow automation and compliance tracking [S1]. This infrastructure theoretically allows for more efficient service delivery and better patient outcomes compared to smaller, less technologically enabled rivals.
However, the home medical equipment (HME) market remains highly fragmented, with competition from large national players, regional providers, product-specific companies, and increasingly, non-traditional entrants like CVS and Amazon. Scale can confer purchasing power and referral relationships, but payor contracts and reimbursement schedules are often set externally. Supplier concentration is a double-edged sword: it can yield better terms but exposes the company to disruption, as seen with Medline’s recent field action [S2]. Unless AdaptHealth can consistently translate its operational advantages into lower costs or superior service, sustainable differentiation will remain challenging.
If Operational Discipline and Technology Drive Margin Expansion
In a favorable scenario, AdaptHealth successfully leverages its streamlined focus on Sleep and Respiratory Health to deepen relationships with referral sources and payors, while its technology platform delivers measurable workflow automation and compliance gains. The company could realize improved patient retention, better reimbursement rates, and lower administrative costs.
Acquisition integration proceeds smoothly, and the company is able to navigate supplier disruptions—such as the Medline recall—without materially impacting patient supply or cost structure. Early evidence would include sequential improvement in EBITDA margins, stabilization or growth in net income, and reduced working capital intensity. Sustained organic growth in the remaining core segments, coupled with positive feedback from payors and patients on service quality and compliance, would further confirm this thesis.
What Steady-State Looks Like After the Diabetes Health Divestiture
The most plausible near-term trajectory for AdaptHealth is a period of operational adjustment following the Diabetes Health divestiture. The company continues to service millions of patients and maintains its national presence, but faces ongoing pressure from labor costs, supplier disruptions, and reimbursement constraints. Scale and technology investments help mitigate some cost pressures, but not enough to fully offset margin compression or drive a rapid return to profitability.
Financial results fluctuate with external shocks—such as supplier field actions and regulatory changes—but AdaptHealth remains a leading player in its core segments. Evidence for this scenario includes persistent but narrowing net losses, limited margin improvement, and continued discussion of operational headwinds in earnings calls. The company’s strategic focus may allow for targeted growth, but structural industry challenges keep returns modest.
How Supplier Disruptions and Regulatory Pressure Could Compound Losses
On the downside, AdaptHealth’s supplier concentration leaves it vulnerable to further field actions, recalls, or price hikes—compromising its ability to deliver critical products on time and at reasonable cost. If such disruptions coincide with reimbursement cuts, regulatory penalties, or persistent labor inflation, the company could see net losses deepen and cash flow deteriorate.
The reduced diversification following the Diabetes Health sale amplifies segment-specific risks; a major operational or compliance failure in Sleep or Respiratory Health could have outsized impact. Evidence would include continued or widening net losses, negative operating cash flow, patient attrition, or loss of key supplier/payor relationships. In this scenario, the company may be forced to restructure, seek external financing, or pursue further asset sales.
Milestones and Metrics That Will Reveal If AdaptHealth’s Refocus Is Working
Sequential changes in EBITDA margin and operating cash flow, especially post-Diabetes Health divestiture, would help test whether operational discipline is improving profitability.
Volume trends in Sleep and Respiratory Health—such as new patient adds, referral growth, and retention rates—would indicate the effectiveness of the company’s strategic focus (if disclosed).
Updates on supplier relationships and procurement costs, particularly regarding Medline and other major vendors, will reveal the extent of supply chain risk mitigation.
Regulatory or reimbursement developments affecting Medicare, Medicaid, or major commercial payors could materially shift the company’s revenue outlook.
Integration milestones and synergy realization from recent acquisitions would signal the company’s ability to deliver on its scale and efficiency thesis.
Disclosures around technology adoption rates and workflow automation outcomes (e.g., reduction in administrative FTEs or billing cycle times) would clarify the ROI on platform investments.
Patient satisfaction and compliance rates, as measured by internal or external surveys, would help assess whether technology integration is translating into better outcomes.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments