
AITX: Autonomous Security Platform Poised at a Pivotal Funding Juncture
Artificial Intelligence Technology Solutions Inc.
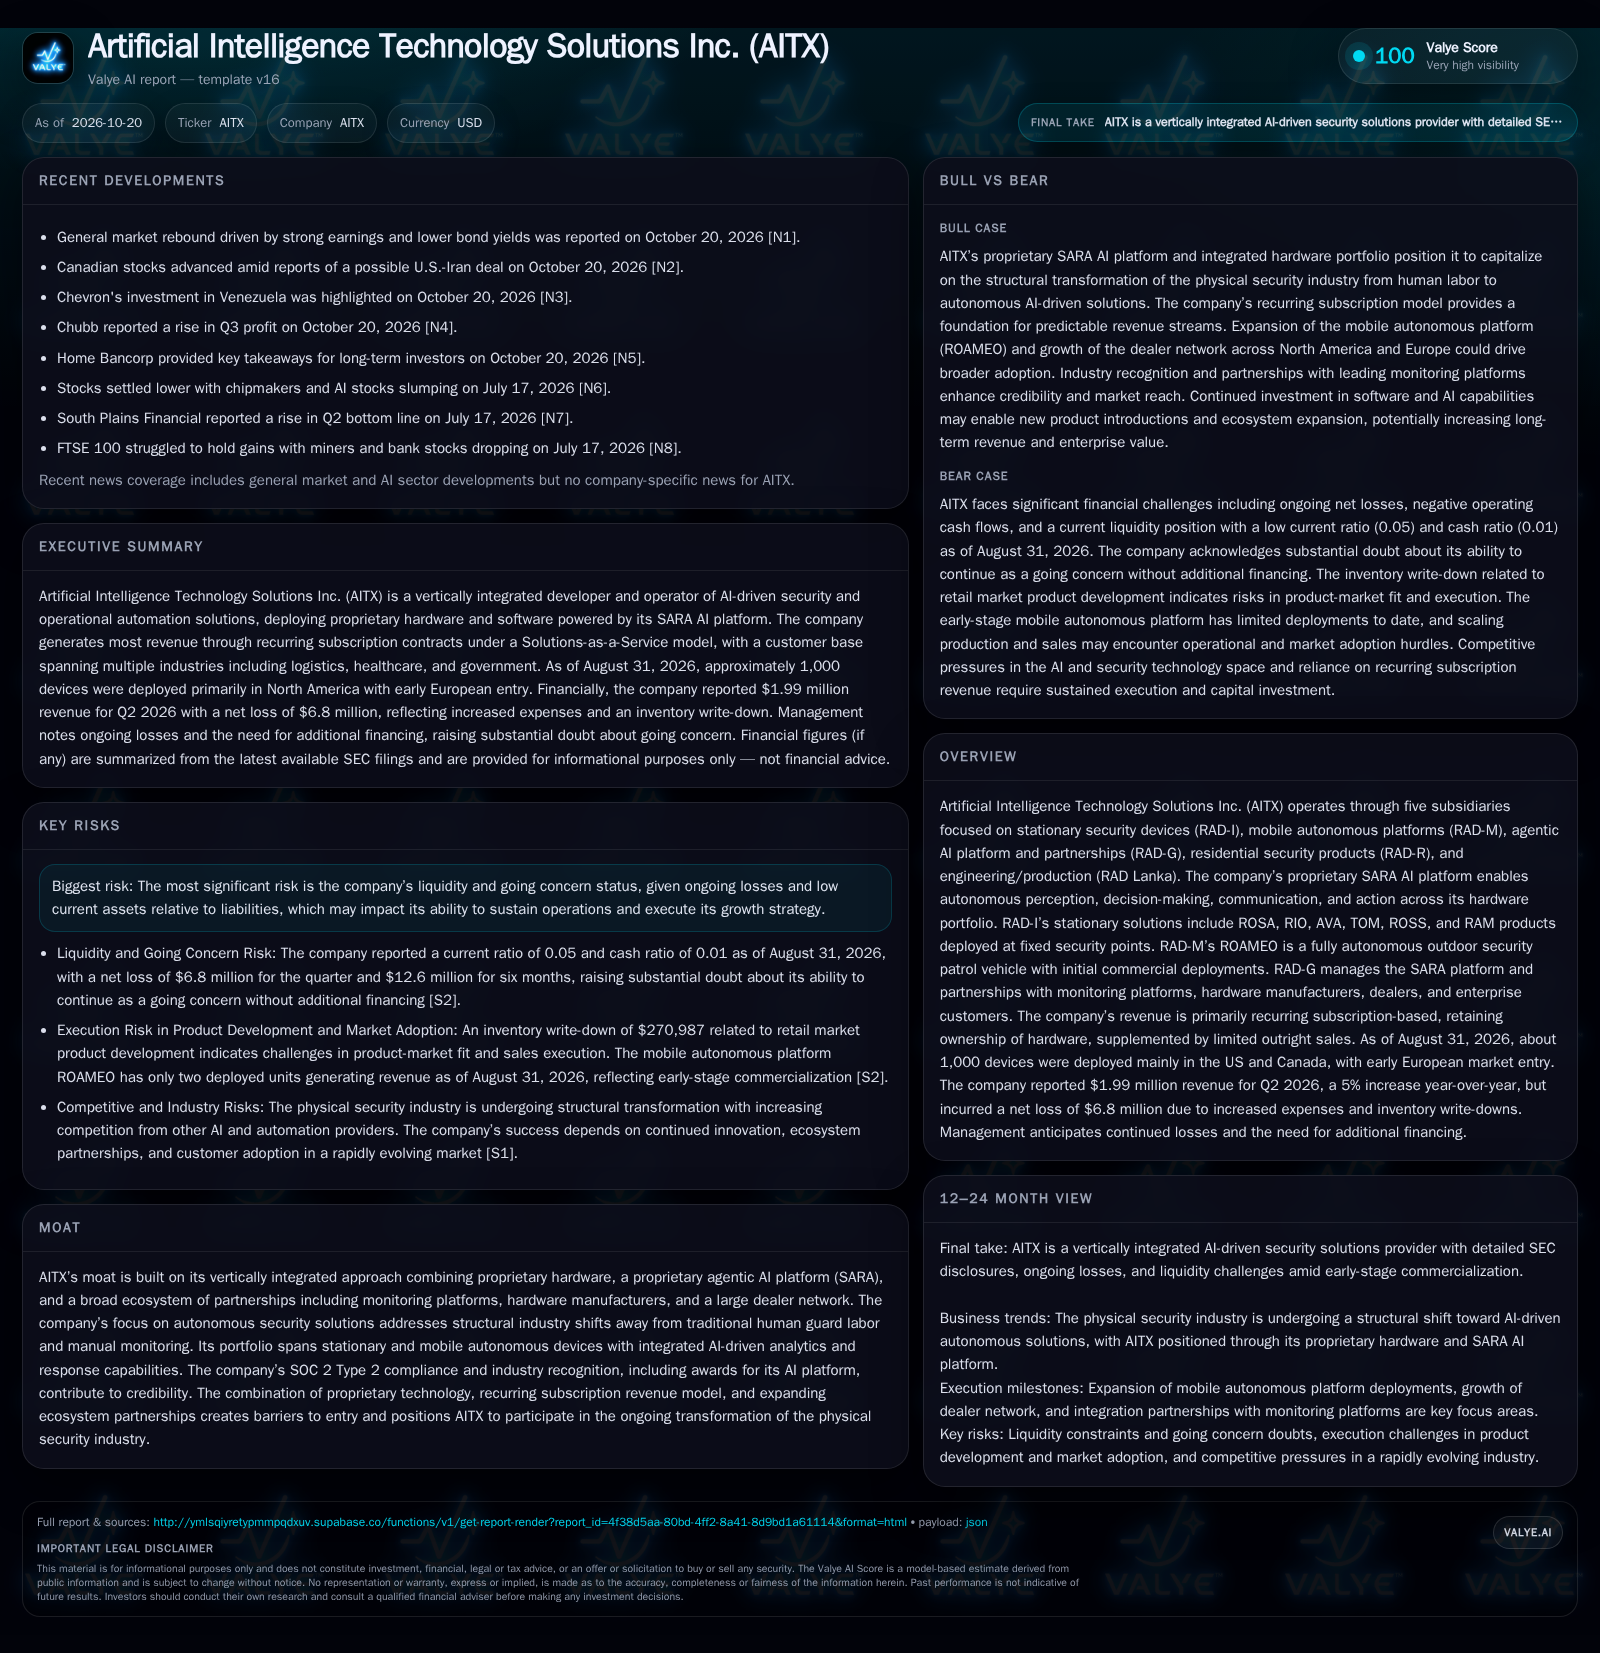
AITX is pushing the boundaries of AI-powered security automation with a recurring subscription model and a portfolio spanning stationary and mobile devices. While device deployments approach 1,000 and revenue is growing modestly, continued net losses, a severe current ratio shortfall, and management’s warnings about going concern cast doubt on the company’s ability to fund its roadmap or withstand competitive pressures without imminent new financing. Execution on mobile platform scale-up and broader adoption will be critical inflection points.
Artificial Intelligence Technology Solutions Inc. (AITX) is betting on the transformation of physical security through autonomous devices and AI-driven platforms. Leveraging its proprietary SARA AI and a hardware-software stack, AITX aims to replace or augment traditional guard services with automated, subscription-based solutions. However, while the company has built a diverse customer base and expanded its portfolio to include both stationary and mobile platforms, deeply negative cash flows and a deteriorating liquidity position now threaten its ability to execute. The coming quarters will be a test of whether AITX can turn early deployments and industry partnerships into sustainable growth before capital constraints force a strategic pivot or retrenchment.
Scaling Ambitions Evident Amid Financial Pressures in Recent Results
As of August 31, 2026, AITX had deployed roughly 1,000 AI-enhanced security devices, with commercial installations concentrated in the United States and Canada and early steps into Europe [S1] [S2]. The bulk of revenue—$1.77 million of $1.99 million in Q2 2026—came from recurring device rentals under a Solutions-as-a-Service model, reflecting traction in subscription adoption [S2]. However, a one-time retail product inventory write-down reduced gross profit by 21% year-over-year, and operating expenses remained high, leading to a $6.8 million net loss for the quarter [S2].
Most critically, the company ended the quarter with only $220,275 in cash and a current ratio of 0.05, while management explicitly raised substantial doubt about the company’s ability to continue as a going concern without immediate new funding [S2]. This liquidity crunch now overshadows operational milestones and raises existential questions about AITX’s roadmap.
Subscription Model Drives Revenue Predictability Alongside Heightened Capital Needs
AITX’s core business model is built around a Solutions-as-a-Service approach: the company retains ownership of its stationary and mobile security hardware, deploying it at client sites and charging monthly subscription fees for ongoing AI-driven monitoring and support [S1] [S2]. This recurring revenue model, now accounting for nearly 90% of revenue, provides a foundation for predictable cash flow—if scale can be achieved. Outright sales to legacy customers offer only modest supplemental income.
The economics of this approach hinge on high upfront costs (hardware design, manufacturing, installation) followed by low marginal delivery costs for additional software-driven monitoring, creating operating leverage if device deployments grow rapidly. However, these upfront capital and R&D needs mean that slow customer adoption or product missteps (such as the recent inventory write-down) can quickly erode gross margins and cash reserves.
With a current device base of 1,000 and only two commercial deployments of the flagship ROAMEO mobile platform, AITX is still in the early innings of achieving the scale required to turn fixed costs into sustainable profitability. The company’s operating expense profile—driven by R&D and ongoing support—remains high relative to revenue, making continued access to external capital a prerequisite for execution.
AITX’s AI Platform Navigates a Competitive Security and Automation Market
AITX positions itself as a vertically integrated provider, combining proprietary hardware, its agentic SARA AI platform, and a growing dealer and partner network [S1]. This enables control over the end-to-end solution, potentially allowing for rapid iteration and integration of new features in response to customer needs.
However, the physical security and automation sector is intensely competitive. Entrants range from traditional guarding firms adding AI overlays, to large security integrators and tech-native startups leveraging cloud video, computer vision, and robotics. The rapid commoditization of core AI capabilities and the growing presence of larger, better-capitalized rivals add pressure—especially as AITX’s ability to invest in R&D and scale production may be hampered by funding constraints.
AITX’s SOC 2 Type 2 compliance and partnerships with monitoring platforms are valuable credibility markers, but the company’s ability to defend its niche will likely depend on continued innovation, ecosystem integration, and the ability to demonstrate clear ROI to cost-sensitive enterprise buyers.
Margin Growth Potential Emerges if Autonomous Security Adoption Accelerates
The most favorable path for AITX is one where customer adoption of autonomous, AI-driven security solutions accelerates—driven by rising labor costs, security staffing shortages, and increasing acceptance of robotics in commercial and industrial settings. In this scenario, the company’s recurring subscription model delivers compounding revenue growth as new deployments layer onto a sticky installed base.
Commercial success of the ROAMEO mobile platform, evidenced by a rapid ramp in unit deployments and recurring billing, would be a key signal that AITX’s next-generation products are resonating with customers. Expansion of the dealer and partner network, especially into new verticals and geographies, would further amplify reach without proportional increases in direct sales expense.
Evidence confirming this scenario would include a sustained acceleration in device deployments (especially ROAMEO), improving gross margins as scale is achieved, and successful closure of new funding rounds or strategic partnerships that extend runway and validate the platform’s value proposition.
Ongoing Losses and Funding Gaps May Lead to Strategic Retrenchment or Equity Dilution
The most plausible near-term outcome is that AITX continues to grow deployments and revenue incrementally, but not at a pace sufficient to cover ongoing operating losses or to materially improve its liquidity profile. The persistent gap between gross profit and high fixed costs, combined with acute current liabilities, places the company in a precarious financial position.
In this environment, AITX will likely be forced to pursue dilutive equity raises, seek bridge loans, or explore strategic alternatives such as asset sales or partnerships to avoid insolvency. Product development and expansion efforts may be slowed or curtailed to conserve cash, increasing the risk of losing momentum to better-funded competitors.
Confirmation of this scenario would be little or no improvement in current ratio, continued net losses, and announcements of emergency financings or restructuring actions. A meaningful reduction in R&D or sales investment would also signal retrenchment.
Liquidity Challenges Could Cause Disruptions, Customer Losses, or Asset Divestiture
In a more adverse scenario, AITX is unable to secure sufficient new capital on acceptable terms, leading to near-term liquidity exhaustion. This could force abrupt operational cutbacks, missed payroll or vendor payments, and the risk of default or bankruptcy proceedings.
Such disruption would likely erode customer and dealer confidence, potentially triggering contract cancellations or non-renewals that further undermine revenue. Competitors could seize this opportunity to poach clients and talent, materially weakening AITX’s market position.
Evidence for this scenario would include failure to announce new financing within the next quarter, public disclosure of missed obligations, or sudden reductions in device support and field operations.
Critical Milestones Will Shape AITX’s Path from Innovation to Market Success
The number of new device deployments per quarter—especially ROAMEO mobile units—will be the clearest indicator of commercial momentum and market fit.
Gross margin trends: Sustained improvement would suggest leverage from scale and better product economics; further compression may signal pricing or cost challenges.
Disclosure of new funding rounds, credit facilities, or strategic investment is critical for assessing runway and whether the company can continue as a going concern.
Dealer and partner network growth across North America and Europe—if disclosed—would help gauge channel expansion and indirect sales leverage.
Churn or renewal rates on existing subscription contracts—if disclosed—would provide insight into product stickiness and customer satisfaction.
Progress on inventory management and avoidance of further write-downs is essential for demonstrating improved execution and capital discipline.
Any material reduction in research and development or sales and marketing spend could signal retrenchment or distress.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments