
Avidbank Holdings: Lending to Tech Firms, Adapting Credit Risk Models, and Capital Strategy in a Volatile Market
Avidbank Holdings, Inc. reported Q3 2026 net income of $10.2 million, with SaaS borrowers comprising 8% of its loan book, and maintains significant liquidity. The bank’s future hinges on managing technology-driven credit risks, especially as advances in AI reshape borrower profiles and sector stability.
The company’s risk management and capital return decisions will be critical as technology trends and market volatility test its lending strategy and portfolio resilience.
As the financial sector’s exposure to tech-enabled business models deepens, Avidbank’s fortunes will depend on its ability to anticipate credit shifts, maintain prudent underwriting, and deploy capital judiciously in a market where both borrower performance and lender strategy are in flux.
Earnings Trends, Liquidity Status, and Tech Exposure Set the Stage
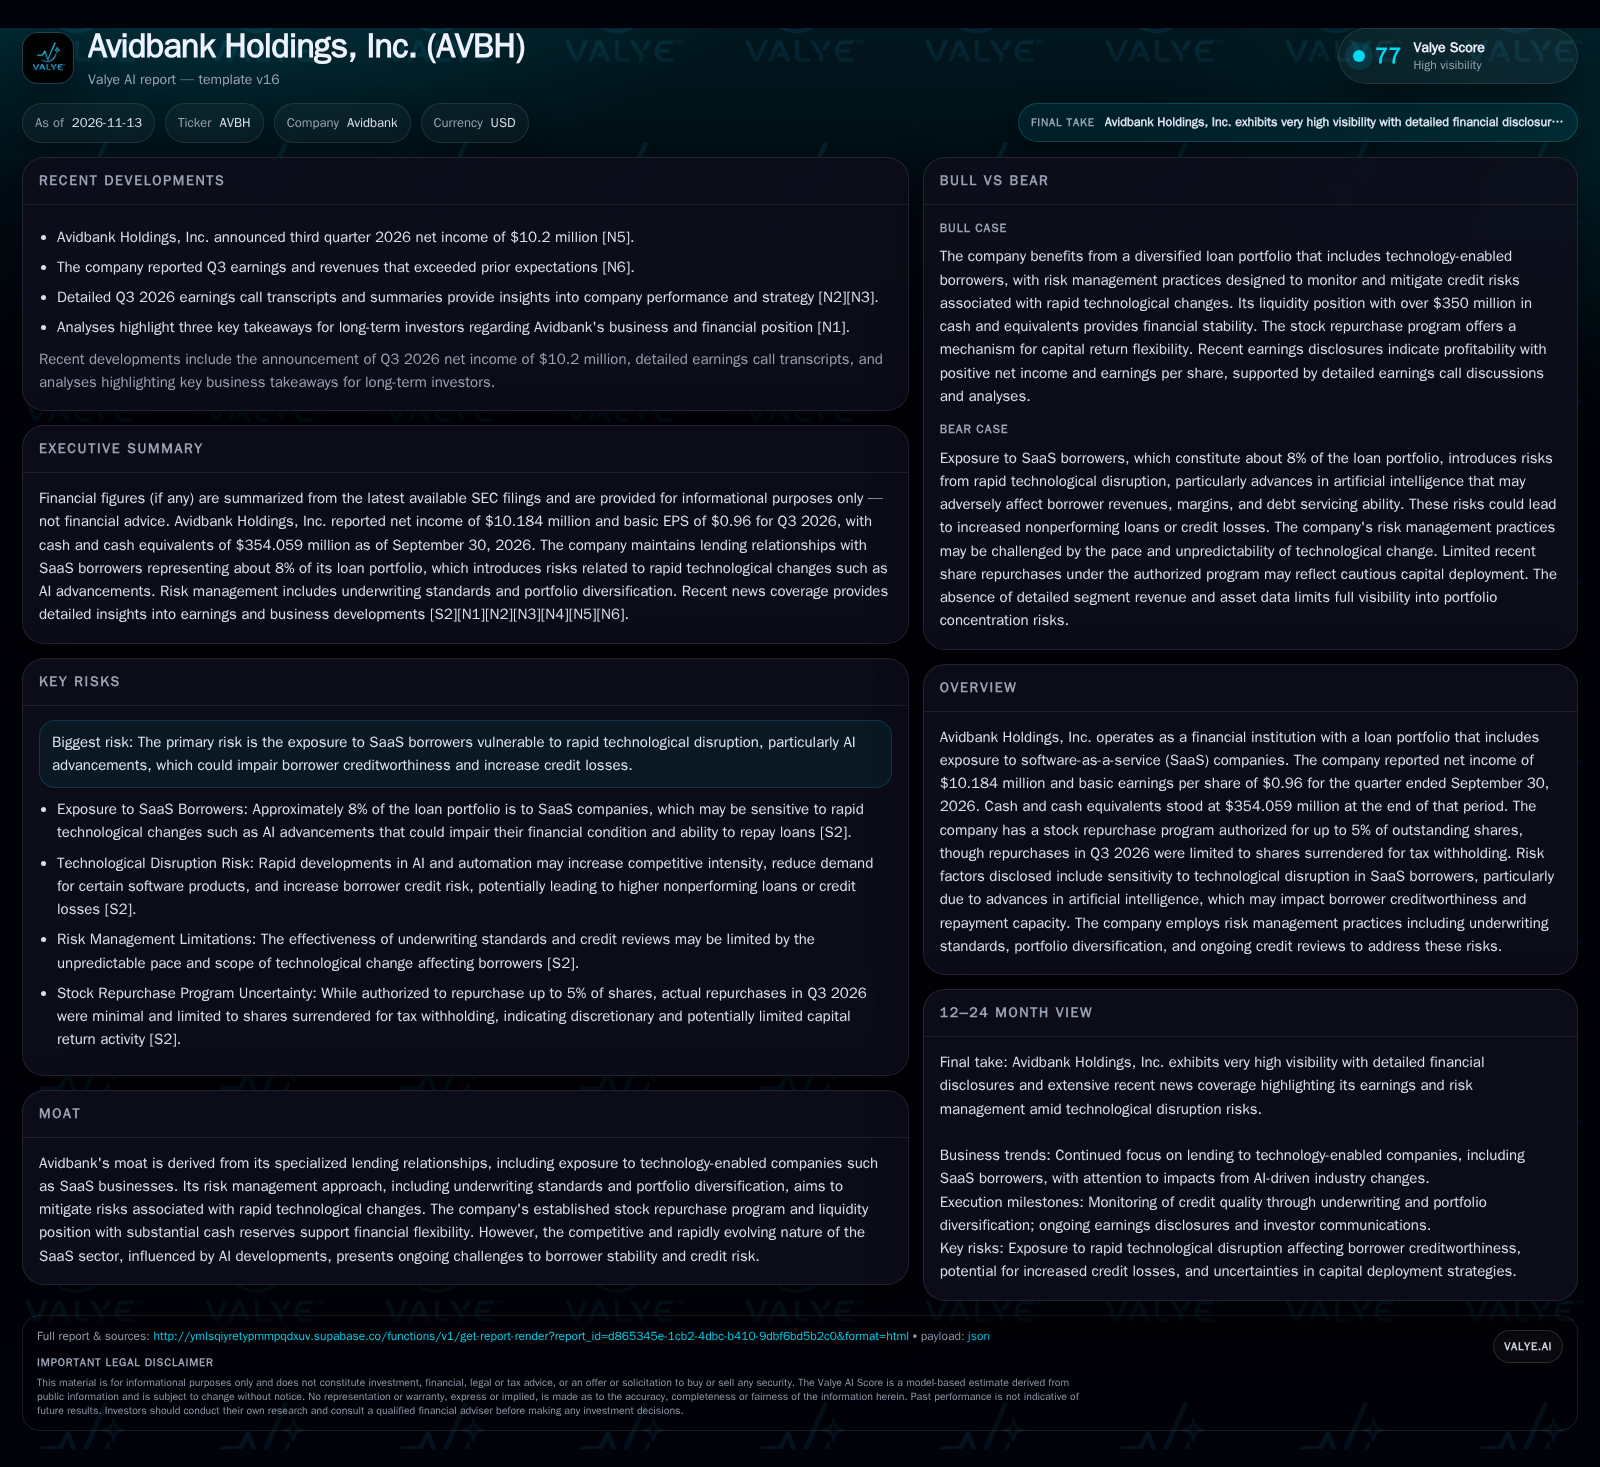
Avidbank reported $10.184 million in net income for Q3 2026, translating to basic EPS of $0.96 and diluted EPS of $0.94 [S2]. This result came alongside cash and cash equivalents totaling $354.059 million as of September 30, 2026 [S2], positioning the bank with notable liquidity. The company’s loan portfolio features exposure to software-as-a-service (SaaS) borrowers, accounting for approximately 8% of total loans—an important detail, as these clients are particularly sensitive to technological shifts, especially advances in artificial intelligence that could alter their creditworthiness [S2]. While Avidbank has an authorized stock repurchase program for up to 5% of shares, actual repurchases in Q3 2026 were limited to shares surrendered for tax withholding related to restricted stock vesting [S2]. These facts frame a narrative of stable profitability, reported liquidity position, and targeted but potentially volatile sector exposure.
Tech-Driven Lending’s Impact on Profitability and Risk at Avidbank
Avidbank’s core business model is traditional commercial banking—earning interest income from loans and deploying customer deposits—but with a distinctive tilt toward technology-enabled borrowers such as SaaS companies. While the precise breakdown of interest margins, loan yields, or fee income is not disclosed, banks lending to SaaS and similar firms often pursue higher yields to compensate for perceived sector volatility, but may also face greater credit risk and potentially lower collateral recoveries in the event of default.
The economics of lending to SaaS-centric borrowers differ from those of asset-heavy industries. SaaS companies typically offer recurring revenue streams, but their business models can be disrupted rapidly by technological change, especially advances in AI. This dynamic presents a tradeoff: higher average yields but greater tail risk if sector disruption accelerates. Because SaaS loans may lack hard-asset collateral, loss severity can be higher in downturns.
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. Operating leverage may be moderate, as banking overhead includes both fixed costs (compliance, risk management) and variable costs tied to loan origination and servicing. Capital needs are less about growth financing and more about maintaining regulatory ratios and absorbing credit losses if tech sector volatility materializes.
Specialized Lending’s Role in a Competitive Financial Sector
Avidbank’s competitive positioning stems from its willingness to lend to technology-enabled sectors, particularly SaaS companies, where traditional banks may tread cautiously. This specialization can attract borrowers seeking lenders who understand sector idiosyncrasies and are willing to underwrite business models with intangible assets and recurring revenue streams.
However, the competitive landscape is dynamic: regional banks, fintech lenders, and niche venture banks all compete for similar clients, often with aggressive pricing or value-added services such as flexible credit lines or industry expertise. Larger banks may also move down-market as the sector matures. The key differentiator for Avidbank could be its underwriting discipline and risk monitoring capabilities, especially as technology cycles accelerate.
The threat of substitution is real: SaaS borrowers can seek funding from non-bank sources, including venture debt, private credit funds, or even direct equity financing—particularly in buoyant markets. If AI-driven disruption leads to higher default rates among SaaS clients, lenders with superior early-warning systems and adaptive risk management may preserve their position, while others could face rapid deterioration in credit quality.
Outperformance Potential Through Advanced Risk Controls and Stable Tech Clients
If Avidbank’s risk management practices—underwriting standards, portfolio diversification, and ongoing credit reviews—prove robust in the face of rapid AI-driven change, the bank could outperform peers with less specialized monitoring. In this scenario, SaaS borrowers weather technological disruption better than feared, maintaining strong operating performance and low default rates. This would allow Avidbank to realize higher net interest margins from its tech-focused lending without incurring outsized credit losses.
Confirmation for this scenario would come from continued low nonperforming loan ratios among SaaS borrowers, stable or improving credit metrics, and evidence of proactive risk mitigation (such as successful restructuring of challenged credits or early exits from deteriorating exposures). Additional upside could materialize if the bank capitalizes on its liquidity to expand tech sector lending prudently or to opportunistically repurchase shares at attractive valuations, signaling management’s confidence in credit quality and future earnings.
Navigating Market Fluctuations Amid Persistent Tech Sector Volatility
The most plausible path forward is one of cautious optimism: Avidbank continues to generate solid core earnings, benefits from its diversified portfolio, and manages its SaaS exposure through ongoing credit reviews and selective underwriting. Some credit stress emerges among SaaS borrowers as AI-driven disruption accelerates, but losses are manageable and offset by yields from disciplined lending.
This scenario would be confirmed by stable net interest income, moderate increases in credit loss provisions, and limited actual defaults among SaaS borrowers. Management commentary would emphasize vigilance and adaptability, with incremental adjustments to underwriting criteria as technology risks evolve. Failure to disclose rising nonperforming loans or sudden swings in provisioning would challenge this view.
AI Advances Prompt SaaS Borrower Challenges and Heightened Credit Risk
In a negative scenario, the pace of AI-enabled technological change materially undermines the business models of SaaS borrowers, leading to revenue declines, margin compression, and a sharp increase in loan defaults. Avidbank’s 8% portfolio exposure to this segment becomes a source of outsized credit losses, overwhelming the benefits of higher yield and eroding earnings.
This scenario would be evidenced by a spike in nonperforming loans and charge-offs linked to SaaS or tech borrowers, a marked increase in credit loss provisions, and management disclosures of stress or restructuring activity in the loan book. Liquidity could be pressured if deposit outflows accelerate or if the bank must absorb losses faster than anticipated. In this context, the stock repurchase program would likely remain dormant, and investor confidence could weaken as visibility into future earnings deteriorates.
Indicators of Avidbank’s Credit Health and Strategic Strength
Trends in nonperforming loans and charge-offs among SaaS borrowers, if disclosed, will be critical to assessing the impact of AI-driven sector disruption on credit quality.
Quarterly changes in credit loss provisions—particularly those attributed to technology-enabled borrowers—would help test the robustness of Avidbank’s risk management.
Loan growth rates in the tech/SaaS segment versus other portfolio categories would indicate management’s appetite for sector exposure and risk-taking.
Disclosure of any new underwriting criteria, portfolio rebalancing, or early warning systems for tech sector loans would signal proactive risk mitigation.
Actual activity under the stock repurchase program (beyond tax withholding) would provide insight into capital allocation discipline and management’s view of intrinsic value.
Deposit growth or outflows, especially if correlated with tech sector volatility, would help gauge franchise stability and funding risk.
Any commentary or disclosure on secondary market sales of troubled loans or loan restructuring activity would be informative for stress-testing scenarios.
A useful metric would be segment-level yield on loans to SaaS/tech borrowers versus the broader portfolio, if disclosed, to understand risk-adjusted return dynamics.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments