
Jefferson Capital’s Post-IPO Expansion: Portfolio Growth, Concentration Risks, and the Economics of Debt Recovery
Jefferson Capital’s strong Q3 2026 results highlight its proprietary approach to debt portfolio acquisition and recovery across geographies. Yet, client concentration, regulatory complexity, and competitive pressures shape both opportunity and risk as the company scales its post-IPO platform.
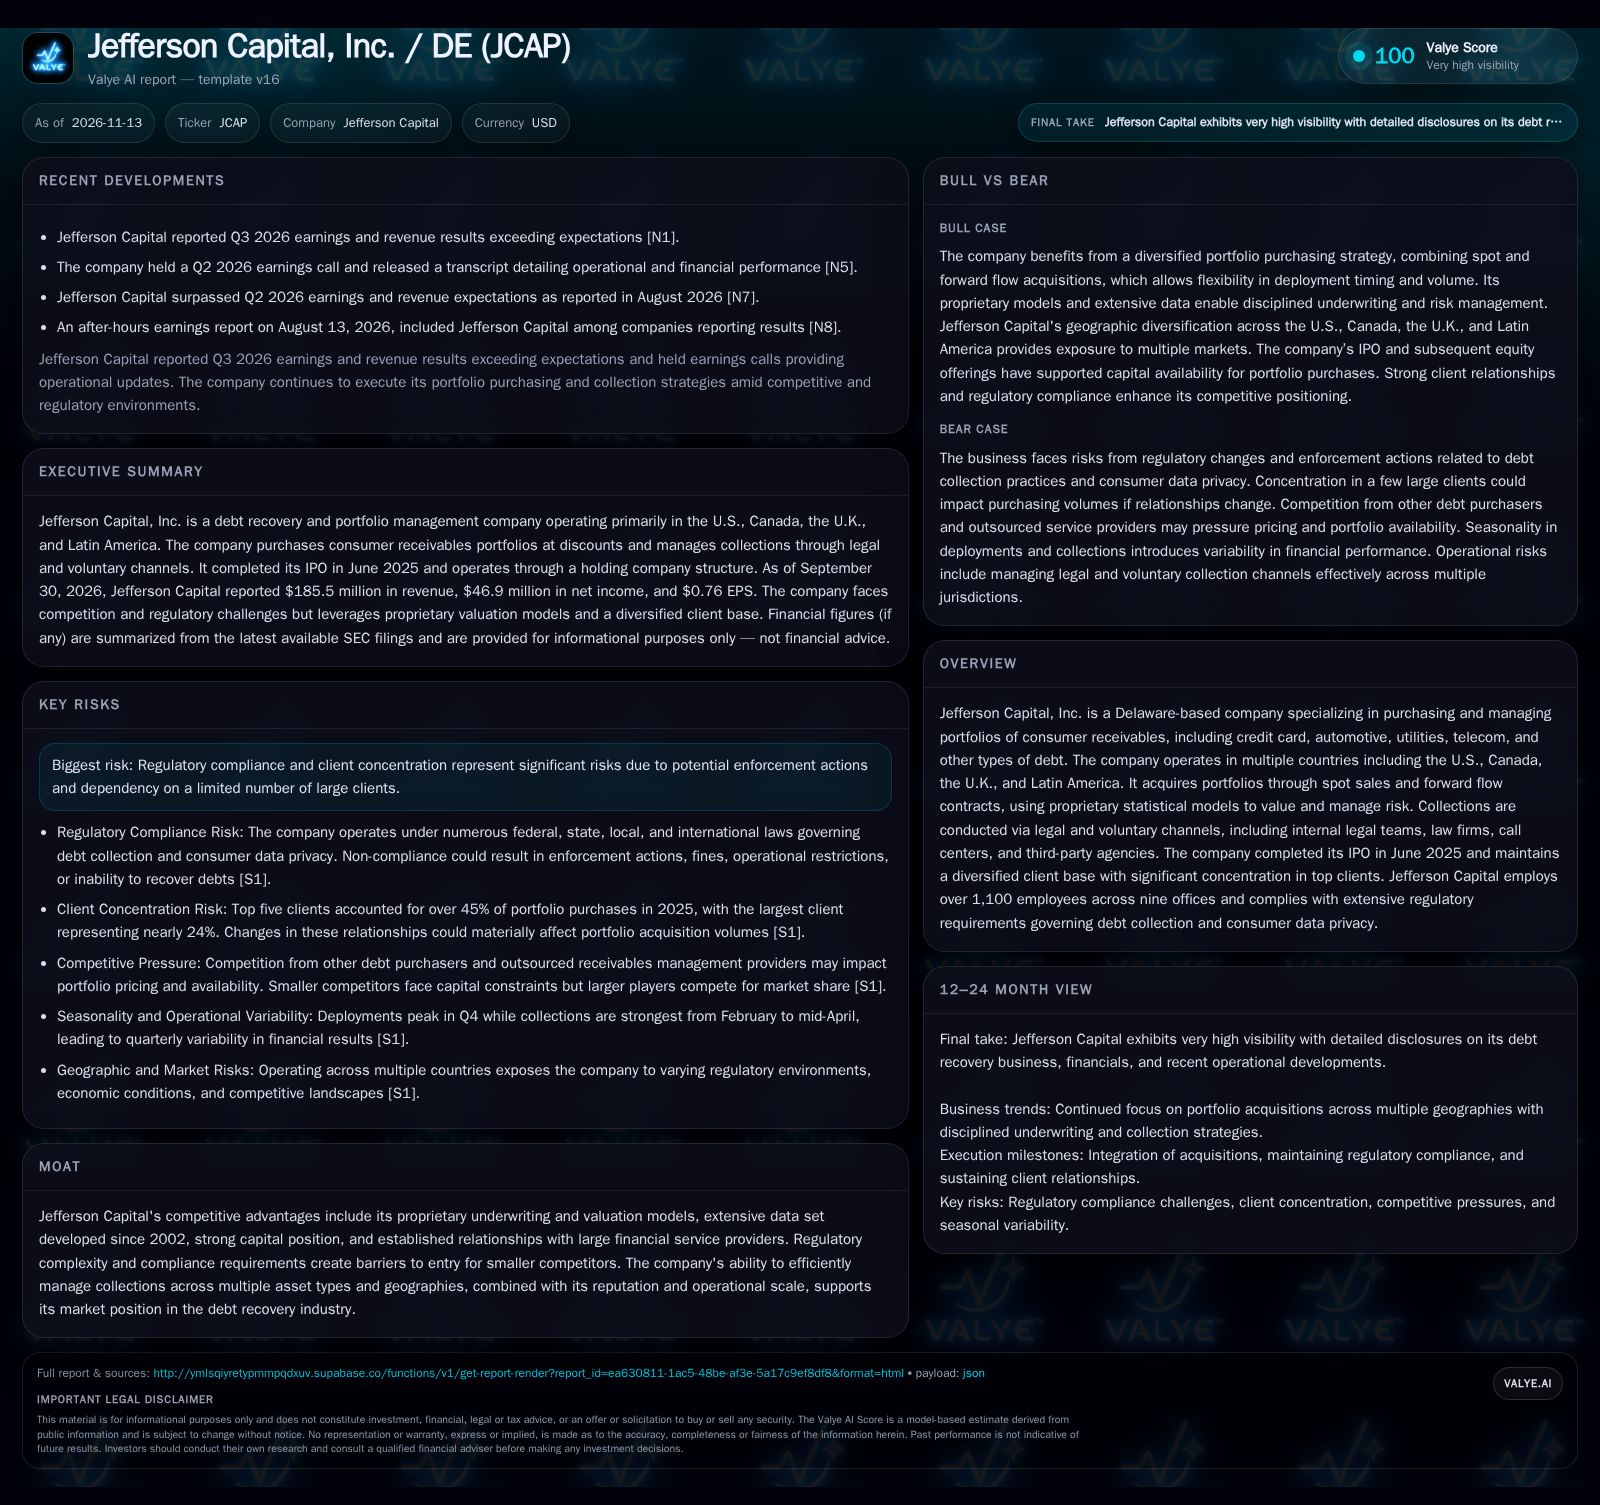
Jefferson Capital reported $185.5 million in revenue and $46.9 million in net income for Q3 2026, exceeding expectations and reflecting disciplined portfolio growth and collection execution. The company’s business model—buying distressed consumer receivables at discounts and recovering value via legal and voluntary channels—relies on proprietary analytics and operational scale. However, high client concentration and regulatory exposure remain structural vulnerabilities. Future performance will depend on sustaining disciplined underwriting, diversifying originator relationships, and navigating evolving compliance demands. [S2] [N1]
Jefferson Capital, Inc. has built a cross-border platform specializing in the acquisition and recovery of distressed consumer receivables, leveraging proprietary behavioral analytics and a multi-channel collections infrastructure. Its Q3 2026 outperformance reflects success in deploying capital into attractively priced portfolios and executing disciplined recoveries. However, the company’s growth trajectory also magnifies exposure to client concentration and regulatory scrutiny—two levers that could sharply alter future economics. Understanding how Jefferson Capital monetizes risk, manages operational leverage, and balances originator relationships is key to evaluating the sustainability of its post-IPO value creation.
Recent Results Underscore Growth and Client Concentration Dynamics
As of September 30, 2026, Jefferson Capital reported $185.5 million in revenue and $46.9 million in net income, with basic and diluted earnings per share of $0.76. These results exceeded market expectations and followed a period of sustained operational execution post-IPO, with the company having raised $4.5 million in net proceeds in June 2025 at $15.00 per share [S2] [N1].
The company’s top five clients represented 45.2% of portfolio purchases in 2025, with the largest single client accounting for 23.6%. This high concentration, despite a broad client base that includes Fortune 500 creditors and fintechs, introduces a material dependency on a handful of relationships [S1].
Portfolio purchases are sourced via both spot sales and forward flow contracts, with terms typically spanning six to twelve months. This mix provides flexibility in deployment but also requires ongoing origination pipeline management to maintain volume and discipline [S1].
How Jefferson Capital Extracts Value from Distressed Receivables
Jefferson Capital’s core economic engine is the acquisition of nonperforming consumer receivables at substantial discounts to face value, followed by recovery efforts that aim to exceed purchase price and direct recovery costs. Pricing is determined by proprietary statistical and behavioral models that estimate collection probability, timing, and cost—the critical variables for profitable deployment.
Revenue is realized through a combination of direct collections (voluntary, legal, and digital channels) and servicing fees on portfolios managed for third parties. The company’s capital is tied up upfront in portfolio purchases, with cash flow returning over a multi-year curve as collections are realized. This creates a lag between deployment and income, but also the potential for significant operating leverage if portfolio pricing and collections efficiency are optimized.
Fixed costs include underwriting, analytics, compliance infrastructure, and the maintenance of a multi-jurisdictional collections platform. Variable costs scale with collection activity—legal expenses, call center staffing, agency commissions, and technology spend. Margins are highly sensitive to both the quality of purchased portfolios and the efficiency of collections execution. In periods of aggressive competition, portfolio pricing can be bid up, compressing returns. Conversely, disciplined sourcing and superior analytics can generate outsized returns on deployed capital.
Barriers, Counterforces, and the Shifting Landscape of Debt Recovery
Jefferson Capital operates in a fragmented but competitive industry, facing direct competition from other large debt purchasers, specialized servicers, and outsourced receivables management providers. Its principal advantages stem from proprietary data and modeling capabilities developed over decades, capital access post-IPO, and a multi-country operational footprint [S1].
However, barriers to entry—regulatory licensing, compliance, and capital requirements—can also become barriers to scale. Larger competitors may exert pressure on portfolio pricing, while smaller players may be unable to compete on analytics or compliance. The rise of fintech originators and digital debt collections platforms is introducing new competitors and could erode traditional sourcing relationships over time.
Switching costs for originators are moderate, as debt sales processes are often competitive and portfolio performance is closely tracked. However, Jefferson Capital’s ability to offer forward flow agreements and compliance assurance may help retain and grow key relationships. The risk remains that adverse regulatory changes or reputational issues could quickly shift portfolio availability or pricing power.
When Analytics and Originator Diversification Drive Durable Returns
A favorable scenario emerges if Jefferson Capital continues to leverage its proprietary models to selectively acquire portfolios with above-average collection potential at attractive prices, while expanding its originator base to reduce client concentration. Consistent outperformance in collections—especially through digital and legal channels—could drive margin expansion and reinforce competitive advantages.
If regulatory environments remain stable and the company demonstrates further geographic or asset-class diversification, it could increase deployment velocity and smooth seasonality. Confirmation of this scenario would include sustained revenue and net income growth above industry averages, a declining share of purchases from the top five clients, and evidence of successful expansion into new creditor verticals or geographies.
Evidence that would falsify this scenario includes a spike in regulatory costs, portfolio pricing compression, or persistent client concentration that limits growth or negotiating leverage.
Disciplined Sourcing Balances Growth with Operational and Regulatory Headwinds
The most plausible trajectory is that Jefferson Capital maintains disciplined portfolio acquisition practices, gradually diversifies its originator mix, and manages stable to modestly improving collection efficiency. Revenue and profit growth would track the broader market for charged-off consumer receivables, with results fluctuating due to seasonality and macroeconomic cycles.
Regulatory compliance costs are likely to remain elevated, especially as the company expands in the U.K., Canada, and Latin America, but not to the extent of derailing the overall business model. The company may continue to report quarter-to-quarter revenue and profit volatility, but with a long-term trend toward moderate growth and incremental margin improvement as scale and analytics deliver operational leverage.
This scenario would be confirmed by stable or gradually improving revenue per dollar of deployed capital, a steady or slightly declining client concentration ratio, and ongoing investment in compliance and analytics infrastructure. Evidence to the contrary would include sudden revenue declines tied to regulatory actions or client losses, or a sharp increase in portfolio acquisition costs.
How Regulatory Shocks or Relationship Losses Could Disrupt the Model
Downside risk is concentrated in two areas: regulatory changes that materially raise compliance costs or restrict collection practices, and the potential loss or reduction of business from one or more of the top five originators. Either could compress margins, reduce available inventory, or force Jefferson Capital to take outsized risks to maintain volume.
An adverse regulatory event—such as a new restriction on legal recoveries, heightened consumer data privacy requirements, or a significant enforcement action—could increase costs and slow collections, especially in the U.S. and U.K. Loss of a key client could create a sudden shortfall in portfolio supply, limiting revenue growth and increasing competition for remaining portfolios.
This scenario would be confirmed by a sharp rise in compliance expenses, legal settlements, or fines, declining portfolio purchases, or a reported drop in originator relationships. Falsification would require evidence of resilient client relationships and successful navigation of new regulatory regimes without margin compression.
Metrics and External Factors That Will Shape Jefferson Capital’s Value Creation
The percentage of portfolio purchases represented by the top five clients—declining concentration would indicate improved risk diversification.
Average purchase price as a percentage of face value for new portfolios—if disclosed, this would reveal competitive intensity and sourcing discipline.
Collections efficiency (collections as a percentage of portfolio cost) by channel and geography—a useful metric for assessing operational leverage and analytics effectiveness.
Regulatory and compliance expense as a percentage of revenue—rising costs here could signal mounting headwinds or regulatory shocks.
Revenue per dollar of deployed capital—a rising trend would suggest improving underwriting and collections or favorable market conditions.
Share of portfolio purchases under forward flow versus spot contracts—shifts may indicate changes in originator preferences or negotiating leverage.
Number of unique originator relationships and their share of total purchases—growth would suggest successful diversification initiatives.
Geographic mix of revenue and portfolio purchases, particularly expansion into new markets—would help test the thesis of geographic diversification as a risk mitigant.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments