
Axogen’s Next Act: Biologic Approval, Market Expansion, and the Economics of Nerve Repair Leadership
With FDA approval for Avance as a biologic and a raised 2026 revenue outlook, Axogen is at a strategic inflection point. The company’s clinical track record and broad product suite position it to capitalize on a large, underpenetrated market, but regulatory follow-through and adoption hurdles remain pivotal.
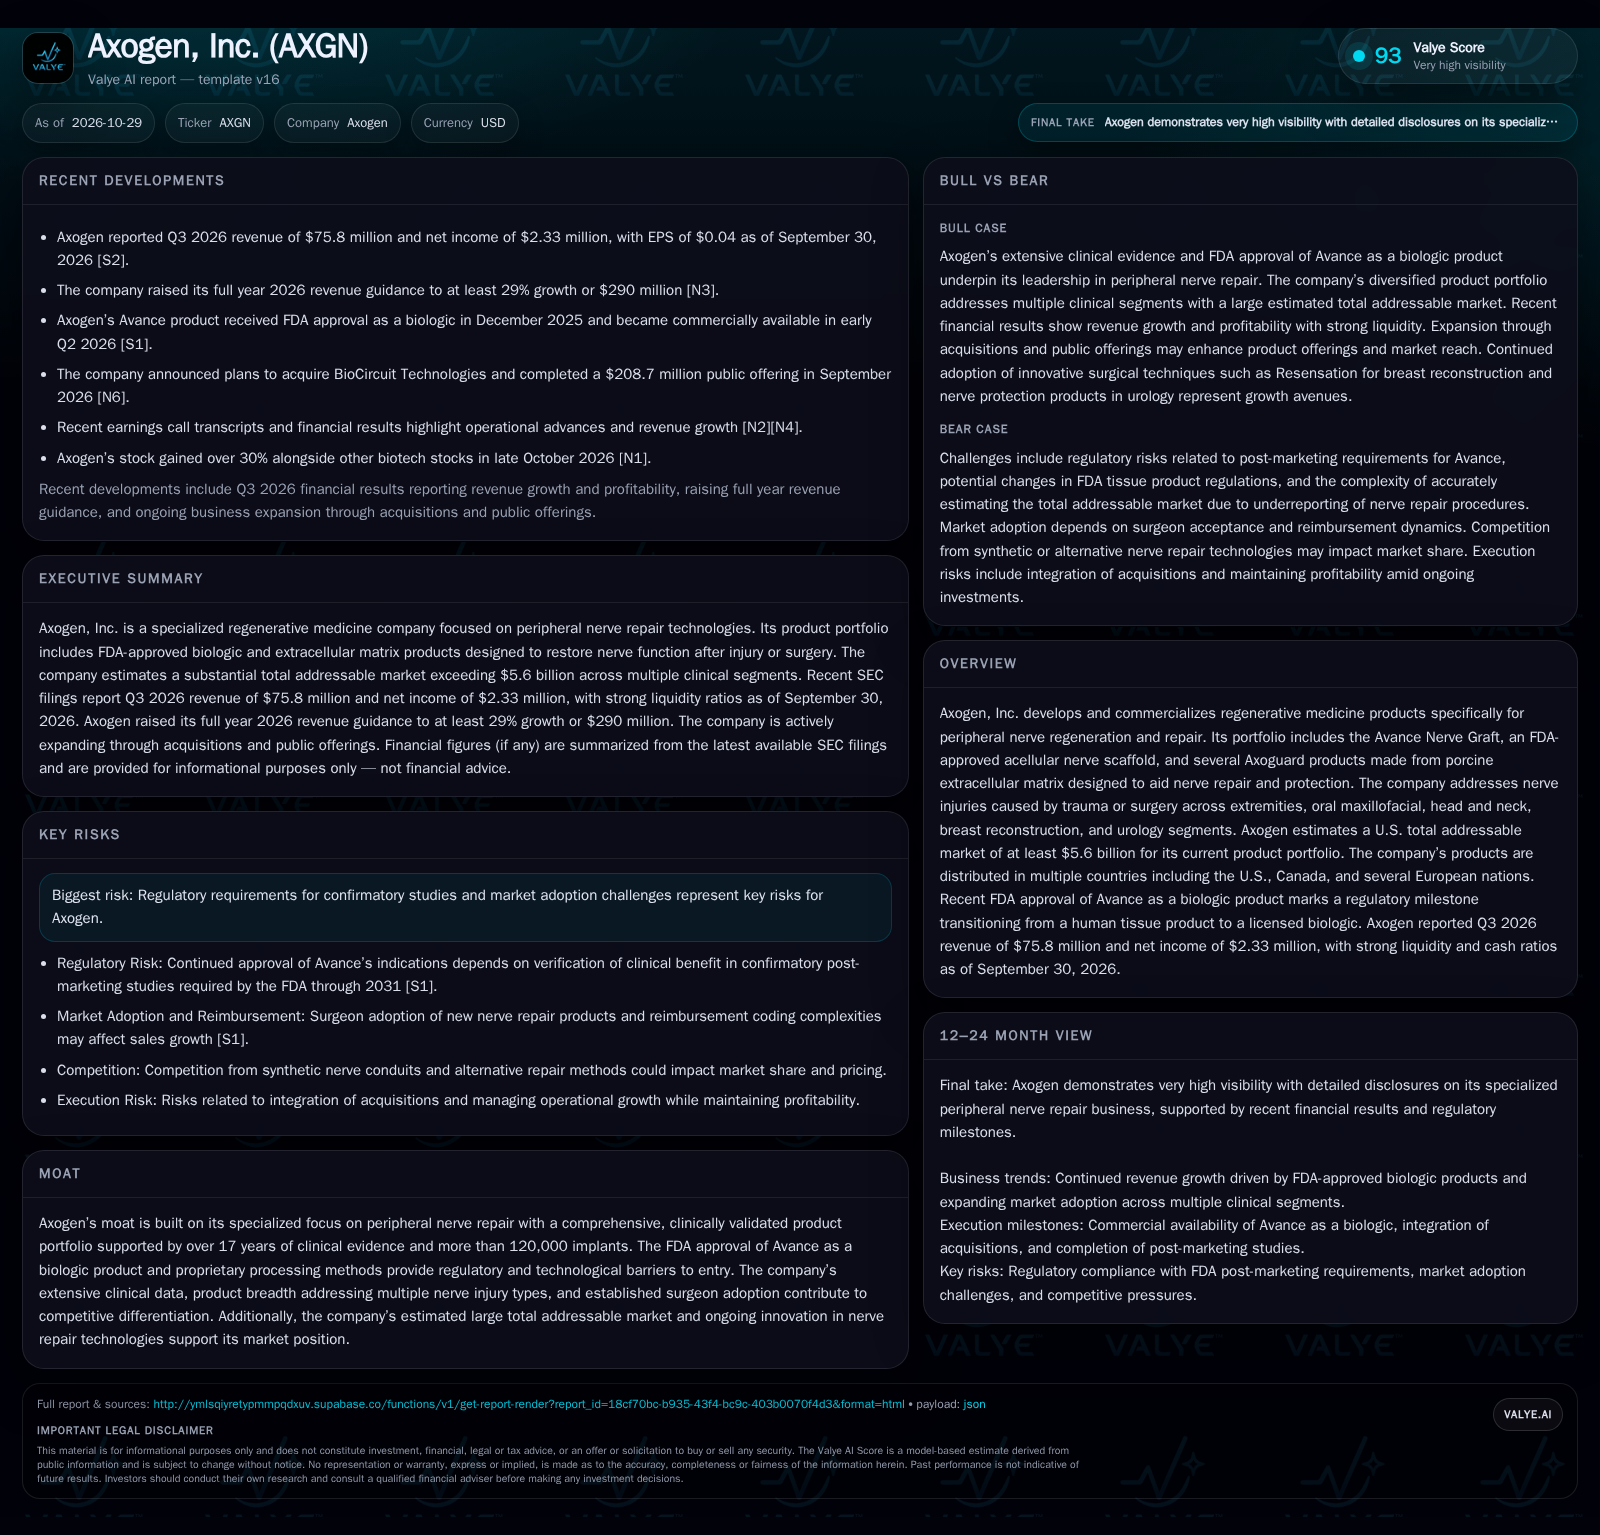
Axogen’s Q3 2026 results show profitability and accelerated revenue growth, underpinned by the FDA’s biologic approval of Avance and a raised full-year outlook. The company faces a substantial U.S. nerve repair market, but regulatory, adoption, and competitive forces will determine the durability of its recent momentum. Watch for post-approval study progress, surgeon uptake, and evolving competitive dynamics as the next phase unfolds.
Axogen’s 2026 narrative is defined by the convergence of regulatory achievement and commercial execution. The FDA’s biologic approval of Avance, now commercially available, has catalyzed both a financial inflection—evidenced by double-digit revenue growth and profitability—and a strategic one, as the company seeks to deepen its penetration into a multibillion-dollar U.S. nerve repair market. Yet, as Axogen transitions from regulatory win to market expansion, the company’s future will hinge on sustained surgeon adoption, successful navigation of post-marketing regulatory requirements, and the evolving landscape of nerve repair technologies.
Regulatory Milestone and Commercial Traction Define 2026 Momentum
The FDA’s biologic approval of Avance in December 2025 marks a watershed moment for Axogen, transitioning its flagship nerve graft from a human tissue product to a licensed biologic under Section 351 of the PHS Act. This regulatory upgrade not only affirms clinical credibility but also potentially enhances reimbursement and market access, particularly in more complex or risk-averse surgical settings [S1].
Commercially, Axogen’s Q3 2026 performance reflects the tailwinds of Avance’s launch, with revenue reaching $75.8 million and net income of $2.33 million [S2]. The company responded by raising its 2026 revenue guidance to at least $290 million, targeting 29% year-over-year growth [N3].
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2]
How Axogen’s Model Converts Clinical Differentiation into Revenue
Axogen’s economics depend on converting clinical leadership in peripheral nerve repair into sustained, high-value product sales. The company’s portfolio—anchored by Avance Nerve Graft and complemented by Axoguard extracellular matrix products—addresses a wide range of nerve injuries and surgical indications. These products are typically used in high-acuity cases where the cost of nerve dysfunction is substantial, supporting premium pricing relative to synthetic alternatives or basic suturing.
The transition of Avance to a biologic product may enable improved reimbursement rates, especially in hospital settings, and could make the product eligible for broader indications or bundled payment coverage. However, the economics are sensitive to surgeon adoption, procedure volumes, and payer acceptance. Axogen’s reported profitability in Q3 2026 suggests a degree of operating leverage as revenue scales, but gross margins and profitability will depend on manufacturing yields, product mix, and the balance of fixed R&D or post-marketing regulatory costs.
Capital intensity is moderate relative to traditional device companies but higher than pure software or digital health models, due to the need for clinical studies, manufacturing, and regulatory compliance. Axogen’s reported liquidity as of September 30, 2026, includes $328.9 million in cash and equivalents and $19.18 million in short-term investments [S2]. This financial position may allow the company to pursue commercial expansion, further clinical validation, or targeted acquisitions, but does not itself guarantee future operating capacity or investment capability.
Barriers, Substitutes, and the Realities of the Nerve Repair Battlefield
Axogen’s competitive position is underpinned by several durable advantages: proprietary processing methods, a comprehensive product suite, and over 17 years of clinical data with more than 120,000 Avance implants [S1]. The recent FDA biologic approval provides a regulatory moat, as competitors must clear substantial hurdles to achieve similar clinical and regulatory validation.
However, market share is not assured. Synthetic nerve conduits, allografts, autografts, and emerging bioengineered alternatives represent credible substitutes, each with distinct tradeoffs in efficacy, cost, and surgeon familiarity. The pace of adoption for new biologics depends on both clinical perception and hospital reimbursement dynamics—surgeons and payers may be slow to shift entrenched practices unless the advantages are clear and supported by robust outcomes data.
Competition may also intensify if larger medtech firms target the same market or if innovation in synthetic or cell-based repair reduces the perceived gap between alternatives. Axogen’s global distribution and clinical education efforts help build mindshare, but the company must continuously invest to defend its position as the standard of care.
From Regulatory Win to Market Standard: A Path to Durable Leadership
The most favorable scenario for Axogen involves rapid, sustained adoption of Avance as the preferred solution for peripheral nerve repair, driven by its biologic status and extensive clinical validation. If reimbursement improves and surgeons increasingly view Avance as clinically superior to both autograft and synthetic options, Axogen could capture a disproportionate share of the estimated $5.6 billion U.S. market [S1].
Confirmation of this scenario would require evidence of accelerating procedure volume growth, positive feedback from key opinion leaders, and expansion into adjacent indications—such as breast reconstruction and urology—beyond the core trauma and extremities segments. Successful completion of post-marketing studies, leading to further label expansion or guideline inclusion, would reinforce Axogen’s leadership.
Falsification would come from plateauing sales growth, slow procedure adoption, or negative data from post-marketing studies that undermine Avance’s clinical edge.
Incremental Expansion Amid Adoption and Regulatory Uncertainties
The most plausible path forward is one of steady but uneven growth: Axogen leverages its regulatory and clinical advantages to expand gradually into new hospitals, surgical specialties, and geographies, but faces pockets of resistance due to surgeon inertia, reimbursement complexity, or competing technologies.
Revenue grows in line with the raised 2026 guidance, but the company must invest in clinical education, post-marketing regulatory work, and market development—dampening margin expansion in the near term. The large addressable market remains only partially penetrated, as underreporting and variability in nerve repair practices limit immediate upside.
This scenario is confirmed by continued revenue and procedure growth at or slightly above market rates, successful completion of regulatory obligations, and modest but improving profitability. It would be challenged by any sign of market share loss to emerging substitutes, reimbursement setbacks, or regulatory delays.
Regulatory and Adoption Friction Stalls Momentum
In a less favorable trajectory, Axogen’s momentum falters due to regulatory setbacks or insufficient surgeon adoption. If post-marketing studies required by the FDA reveal limitations in Avance’s clinical benefit, or if new safety signals emerge, the company could face label restrictions, reimbursement challenges, or even product withdrawal requirements.
Alternatively, if payers resist higher reimbursement for biologic products or surgeons revert to autograft or synthetic alternatives due to cost or familiarity, Axogen’s market share could stagnate or decline. Competitive encroachment from novel synthetic or cell-based solutions could further compress pricing and erode differentiation.
This scenario would be confirmed by regulatory warnings, missed revenue targets, negative trends in surgeon feedback, or increased market share for substitutes.
What Could Shift the Axogen Thesis in 2027 and Beyond
Progress and outcomes from FDA-mandated post-marketing studies for Avance—positive interim data or study completion would reduce regulatory risk; negative results could threaten the product’s label or reimbursement.
Quarterly tracking of procedure volume growth and product adoption rates across major surgical indications—if disclosed.
Changes in reimbursement policy or coding for biologic nerve repair products, including any CMS decisions or major private payer updates.
Gross margin trends and cost structure evolution as biologic manufacturing scales and product mix shifts.
Competitive product launches or regulatory approvals for alternative nerve repair solutions—monitor for new synthetic, cell-based, or biologic entrants.
Surgeon feedback and published comparative outcomes data, especially from key opinion leaders and high-volume centers.
Geographic expansion progress, particularly in Europe and other developed markets—watch for regulatory approvals and revenue contribution from outside the U.S.
Any significant acquisition, partnership, or capital allocation event that could reshape Axogen’s scale or strategic direction.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments