
Bluerock Homes Trust: Portfolio Diversification, Profitability Hurdles, and the Path to Cash Flow Stability
With a portfolio spanning over 4,400 residential units and nearly $1 billion in assets, Bluerock Homes Trust faces a pivotal period where occupancy rates, development execution, and rent optimization will define its ability to convert scale into sustainable earnings and reliable dividends.
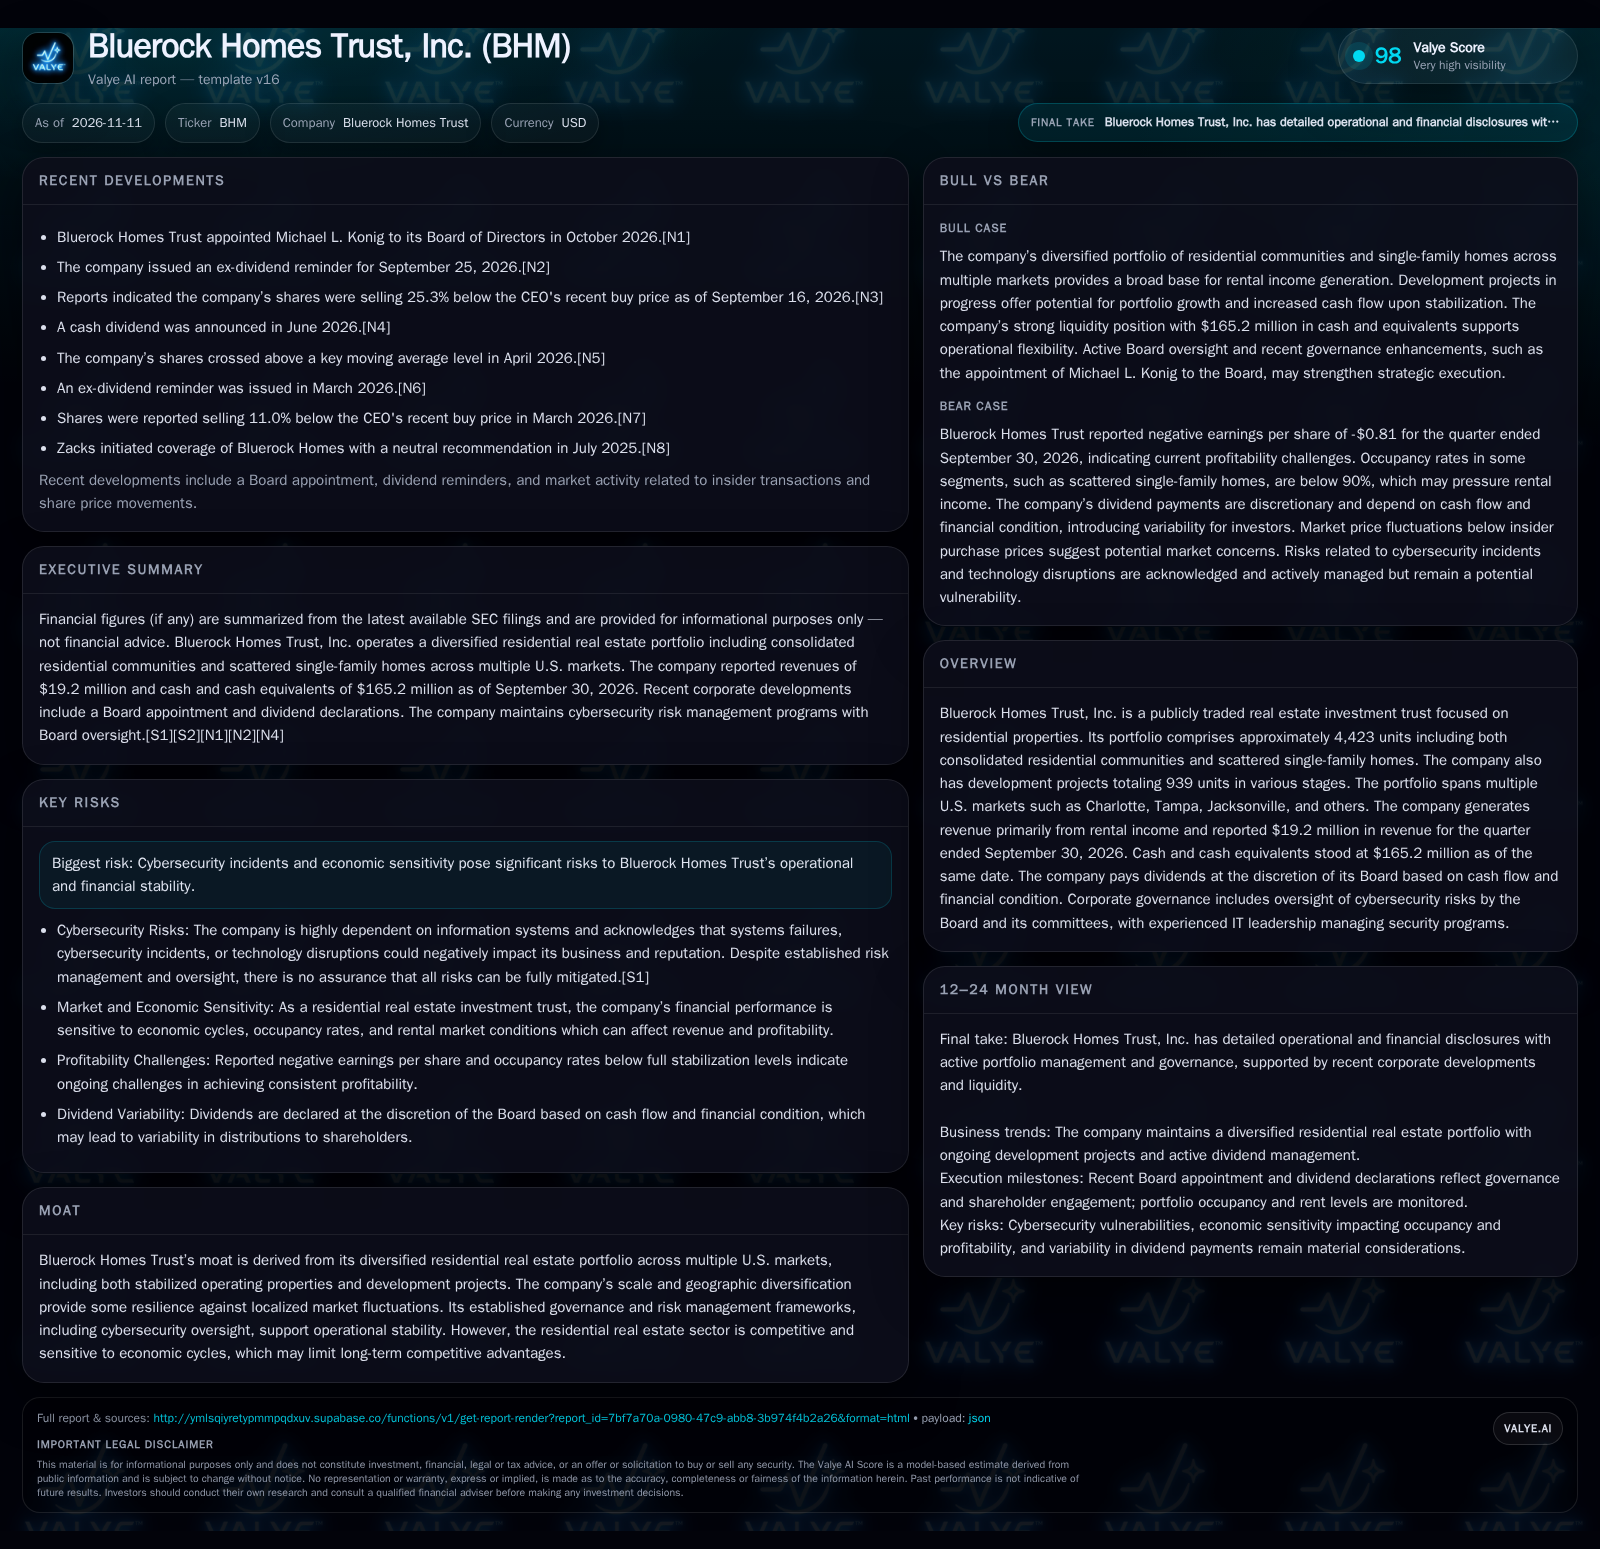
Bluerock Homes Trust operates a geographically diversified residential real estate portfolio, generating $19.2 million in quarterly revenue and managing 4,423 units. However, profitability is challenged by negative EPS and sub-90% occupancy in single-family homes. The company retains significant liquidity ($165.2 million in cash) and is advancing nearly 1,000 development units. The critical questions are whether Bluerock can lift occupancy and rents to stabilize cash flow, and how effectively it can deploy capital into accretive growth versus defending distributions amid market pressures.[S2] [N1] [N2] [N3]
Bluerock Homes Trust, Inc. stands at a crossroads typical of mid-sized residential REITs: it commands a sizable and diversified portfolio across U.S. growth markets, yet faces the reality of negative earnings, occupancy drag in its single-family segment, and a share price that has fallen below insider buy levels. Investors and analysts alike are focused on whether Bluerock can convert its geographic reach and development pipeline into durable, distributable cash flow—and whether its governance and risk controls are sufficient to weather sectoral and macroeconomic volatility.
Recent Financials, Occupancy Gaps, and Strategic Developments Shape Investment Debate
The cited source reports dividend-related activity; that disclosure alone does not establish dividend-policy continuity, management confidence, or a material constraint on capital flexibility. [S2] [N1] [N2] [N4]
How Bluerock’s Revenue Streams and Cost Structure Influence Margin Potential
Bluerock’s primary revenue engine is rental income from its diversified portfolio. The residential community segment, with higher occupancy and slightly higher rents, likely delivers more predictable cash flow and operating leverage, as fixed property management and maintenance costs are spread across more units. The scattered single-family homes segment, while offering exposure to a popular asset class, suffers from lower occupancy and may face higher per-unit operating costs due to geographic dispersion and individualized management requirements.
Development projects—nearly 1,000 units in the pipeline—are a double-edged sword: they offer upside through future rent growth and asset appreciation, but also tie up capital and can pressure cash flow during construction and lease-up phases. The company’s negative EPS suggests that either operating expenses, interest costs, or depreciation/amortization are currently outpacing rental revenue, a common challenge for REITs scaling up or integrating new assets.
The company reported profitability for the period.
A deeper examination of Bluerock’s cost structure reveals that fixed versus variable cost dynamics critically influence margin expansion potential. Fixed costs such as property taxes, insurance, and certain maintenance contracts do not scale down with occupancy declines, thereby amplifying profitability pressure when units remain vacant. Conversely, variable costs tied to utilities, turnover repairs, and leasing commissions fluctuate more directly with occupancy changes. Understanding the proportion and behavior of these costs across Bluerock’s portfolio segments would help clarify the operating leverage embedded in the business model. For instance, higher fixed cost intensity in scattered single-family homes could exacerbate losses when occupancy dips below critical thresholds.
Assessing Bluerock’s Edge in a Crowded and Cyclical Residential Real Estate Market
Bluerock’s competitive position is anchored in its geographic diversification across growth markets like Charlotte, Tampa, and Houston, which can buffer against region-specific cycles. The mix of multi-family communities and single-family homes allows the company to capture a broad tenant base and potentially shift capital between segments as market dynamics evolve.
However, the residential REIT sector is structurally competitive, with barriers to entry relatively low aside from capital requirements and local market knowledge. Institutional investors, private equity funds, and other REITs compete aggressively for both stabilized assets and development opportunities, often compressing acquisition yields and driving up land/construction costs. Occupancy rates below 90% in the single-family segment suggest that either property locations, management efficiency, or local demand may be lagging, giving better-capitalized or more operationally nimble peers a potential edge.
Cybersecurity and technology risk management, while increasingly important, are unlikely to be meaningful differentiators unless Bluerock can demonstrate superior tenant experience, cost efficiency, or risk mitigation compared to sector peers.
Unlocking Value Through Occupancy Gains and Successful Development Lease-Up
A bullish scenario for Bluerock hinges on two main levers: raising occupancy in the scattered single-family home segment and executing on the development pipeline to bring new units online at attractive rents. If the company can close the occupancy gap—lifting single-family rates toward the mid-90% range seen in its community portfolio—incremental rental income would flow through with high operating leverage, improving margins and turning net losses into positive earnings.
Successful lease-up and stabilization of the 939 development units could further grow recurring cash flow, while geographic diversification would help absorb localized shocks. The company’s ample cash reserves could be deployed for targeted acquisitions, property enhancements, or opportunistic buybacks if market pricing remains dislocated.
Confirmation would come from reported improvements in single-family occupancy, positive EPS trends, and consistent or growing dividends. Falsification would be evident if occupancy remains stagnant, development projects are delayed or over budget, or EPS fails to turn positive despite new units coming online.
Operational Progress Offset by Market Headwinds and Development Risk
The most plausible near-term outcome is incremental improvement: Bluerock gradually increases occupancy through targeted leasing and operational initiatives, but faces ongoing margin pressure from competitive rental markets, rising property taxes, and potential interest rate volatility. Revenue growth from stabilized developments helps offset softness in legacy portfolios, but the company’s ability to consistently generate positive earnings remains challenged until occupancy and rent levels reach critical mass.
Dividend payments may fluctuate in line with cash flow, and share price may continue to trade at a discount to book value or insider buy levels if the market perceives execution risk or sector headwinds.
Sustained Occupancy Weakness and Delayed Developments Erode Cash Flow
In a negative scenario, Bluerock fails to improve occupancy in the single-family segment, perhaps due to macroeconomic slowdown, over-supply in targeted markets, or ineffective property management. Development projects encounter delays or cost overruns, meaning cash is tied up longer than anticipated and rent growth is deferred. As a result, negative earnings persist and cash burn accelerates, forcing the company to curtail dividends, delay new investments, or potentially raise capital at dilutive terms.
This outcome would be confirmed by declining or flat occupancy rates, mounting losses, reduced or suspended dividends, and a shrinking cash balance. Share price could fall further below insider buy levels, increasing pressure from investors and limiting strategic flexibility.
Milestones and Metrics That Will Define Bluerock’s Ability to Deliver Sustainable Value
Quarterly occupancy rates by segment—particularly in scattered single-family homes—will indicate whether leasing initiatives are gaining traction or if structural challenges persist.
Average rent per unit and rent growth trends, if disclosed, will show whether Bluerock is capturing pricing power or facing competitive pressure in its markets.
Progress on development pipeline—units delivered, leased, and stabilized each quarter—will clarify the timing and magnitude of future cash flow.
Trends in basic and diluted EPS will reveal whether operational improvements are translating into sustainable profitability.
Quarterly cash balance and sources/uses of cash, especially in relation to development expenditures and debt service, will frame capital adequacy.
Updates on Board and management strategy, including commentary on portfolio allocation, risk management, and capital deployment priorities, would help test the thesis.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments