
BK Technologies: Specialized Public Safety Communications Confronts Market Maturity and Innovation Stakes
BK Technologies, a longstanding supplier of P25-compliant radios and SaaS-based interoperability solutions for first responders, posts solid profits and maintains reported liquidity position, but faces a maturing land mobile radio market and intensifying competition. The company’s ability to extend its technology moat, drive adoption of SaaS solutions, and hedge against government budget cyclicality will shape its next phase of value creation.
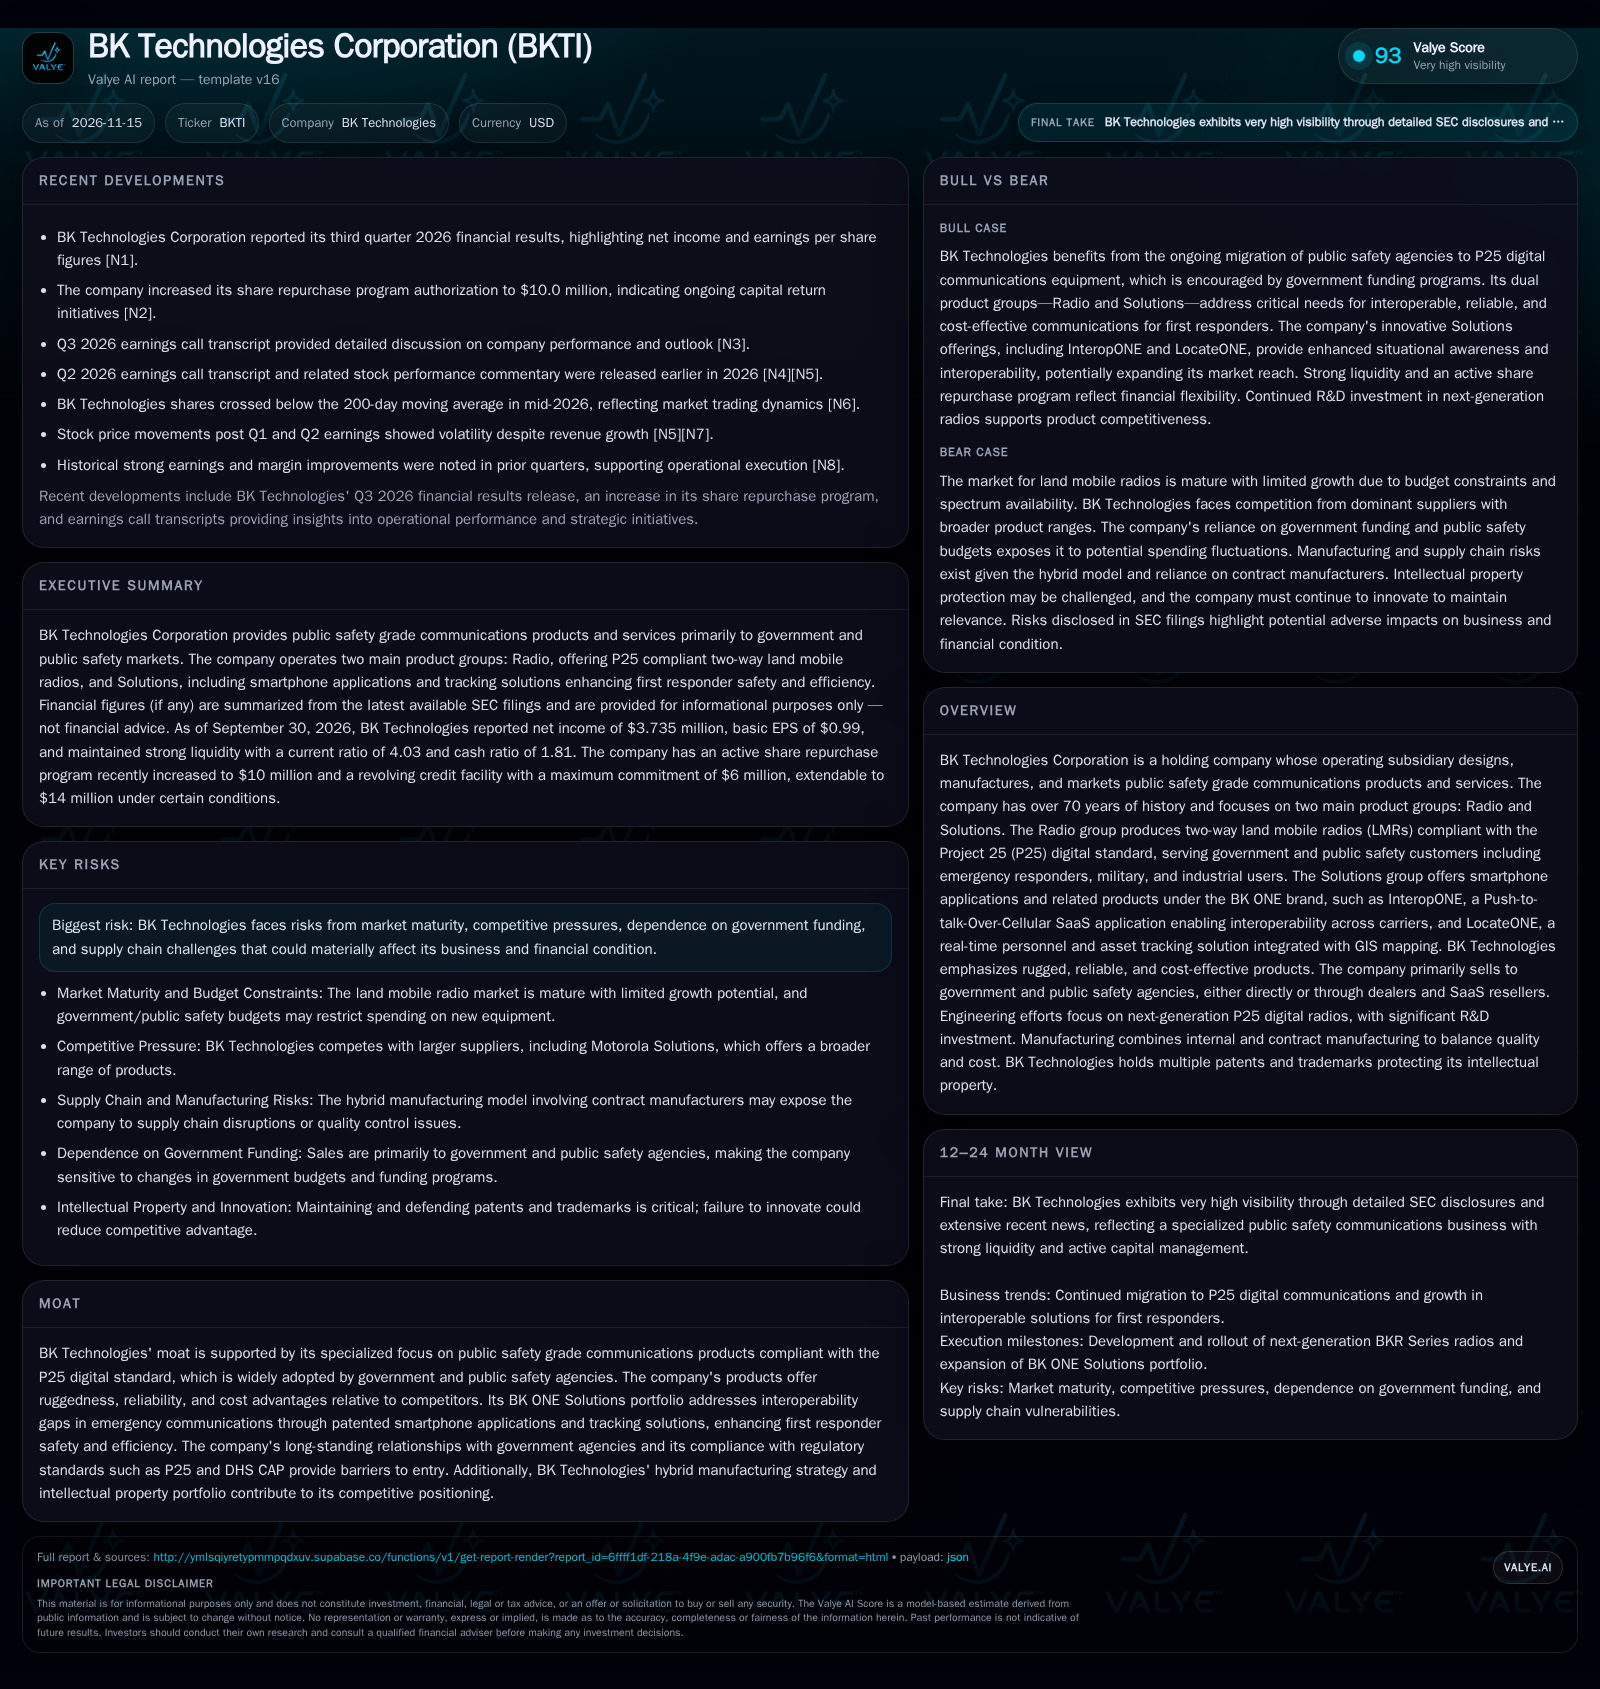
BK Technologies has reported a profitable Q3 2026 and displays a reported liquidity position, underpinned by its dual focus on rugged, cost-effective P25 radios and emerging SaaS solutions for public safety agencies. While its core radio business benefits from entrenched relationships and compliance standards, long-term growth depends on the adoption of innovative BK ONE applications and the company’s ability to out-innovate larger rivals in a mature, budget-constrained market. Monitoring uptake of new solutions, R&D productivity, and government spending trends will be critical to understanding future trajectory. [S1] [S2]
BK Technologies stands at a crossroads as it delivers strong profitability and liquidity in late 2026, supported by a legacy radio business and a growing portfolio of software-driven interoperability tools for first responders. While the company’s entrenched position in public safety communications and P25 compliance offer competitive insulation, the broader land mobile radio market is increasingly mature, with limited organic growth and budget headwinds among key government customers. BK Technologies’ future value creation will hinge on its capacity to commercialize next-generation SaaS solutions, maintain technological relevance, and navigate the risks posed by larger, better-resourced competitors.
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financ
BK Technologies reported net income of $3.735 million for Q3 2026, with basic EPS of $0.99 and diluted EPS of $0.93, reflecting ongoing profitability. The company also increased its share repurchase program authorization to $10 million in 2026, signaling a willingness to return capital to shareholders. These financial outcomes grant BK Technologies operational flexibility to invest in R&D and pursue strategic product launches without immediate financing pressure. However, the company’s performance remains closely tied to government contract cycles and the pace of adoption for its newer solutions. [S2] [N1] [N2]
Revenue Mix and Margin Dynamics in a Dual-Product Model
BK Technologies generates revenue through two primary channels: hardware sales of P25-compliant land mobile radios (LMRs) and the Solutions segment, which includes SaaS-based interoperability applications and asset tracking tools. The Radio business is typically characterized by lumpy, contract-driven sales cycles, high customer concentration (often tied to government agencies), and moderate gross margins due to hardware cost structure and competitive pricing. The Solutions segment, by contrast, has the potential for higher recurring margins via subscription-based software and data services, but currently represents a less mature revenue stream.
The company’s hybrid manufacturing model—combining internal Florida-based production with contract manufacturers—provides some cost flexibility but could expose margins to supply chain shocks and scale inefficiencies if volumes fluctuate. R&D and engineering costs are capitalized in part, reflecting ongoing investment in next-generation digital radios and software applications. As the product mix shifts toward SaaS, operating leverage could improve if adoption accelerates and fixed engineering costs are spread over a larger subscriber base. However, the pace and scale of this transition remain uncertain, as BK must overcome entrenched purchasing patterns and conservative procurement cycles in the public sector.
Specialization and Compliance as Moat—But Scale and Ecosystem Gaps Remain
BK Technologies’ core differentiation stems from its focus on rugged, P25-compliant radios tailored to the unique requirements of first responders, alongside patented solutions targeting interoperability and real-time situational awareness gaps. Long-standing relationships with government agencies and compliance with regulatory standards (such as P25 and DHS CAP) act as significant barriers to entry for new challengers. The company’s intellectual property portfolio, which includes five U.S. patents in force and several pending, further supports its Solutions franchise.
Despite these advantages, BK operates in a highly competitive landscape dominated by much larger vendors—most notably Motorola Solutions and other multinational suppliers with broader product suites, greater integration capabilities, and more extensive service networks. While BK’s cost positioning and software innovation may appeal to budget-conscious agencies, it faces persistent risk of displacement if larger incumbents bundle hardware, software, and managed services at scale. Moreover, the land mobile radio market is mature, with slow replacement cycles and high switching costs, making it difficult for smaller players to rapidly expand share without a disruptive value proposition.
SaaS Adoption and Interoperability Mandates Could Catalyze Growth
The most optimistic scenario for BK Technologies involves accelerated adoption of its BK ONE suite—particularly InteropONE and LocateONE—by public safety agencies seeking to modernize communications and meet new interoperability mandates. As government funding programs continue to incentivize migration to P25 digital platforms, agencies may also be compelled to adopt SaaS-based coordination and tracking tools to bridge communication across legacy and next-gen systems.
Evidence supporting this scenario would include a marked increase in Solutions segment revenue, growing SaaS subscriber counts (if disclosed), and announcements of multi-agency contracts or statewide deployments. Additional confirmation would come from product roadmap execution, such as expanded features, successful integration with third-party platforms (e.g., Esri ArcGIS), and new patents granted. If the Solutions portfolio gains traction, BK could see an improvement in gross margins, stronger recurring revenue streams, and a higher multiple from investors seeking exposure to software-driven public safety transformation.
Incremental Progress Amid Market Maturity and Funding Cyclicality
The most plausible outcome is a continuation of modest growth, with hardware sales remaining the primary revenue driver and Solutions contributing incrementally. In this scenario, BK Technologies sustains its profitability and liquidity, supported by ongoing replacement cycles for P25 radios and selective uptake of SaaS offerings among early-adopter agencies. The company’s focus on R&D and new product development helps maintain relevance, but the overall pace of market expansion remains constrained by public sector budget cycles and lengthy procurement processes.
Confirmation of this trajectory would include stable or gradually rising revenues from the Radio segment, periodic contract wins from state and local governments, and incremental Solutions revenue growth without a step-change in adoption rates. The company’s margin profile would remain steady, with improvements tied to operational efficiencies or successful cost management in manufacturing. Any acceleration in SaaS adoption or entry into new adjacent markets would provide upside to this scenario, but is not assumed as the base case absent clear evidence.
Government Budget Retrenchment and Competitive Displacement Threaten Core Revenue
A negative turn for BK Technologies could materialize if government spending on communications equipment contracts sharply, whether due to fiscal austerity, shifting procurement priorities, or macroeconomic shocks. In such a scenario, the company’s lumpy hardware sales would be acutely exposed, with limited ability to offset volume declines through its still-nascent Solutions business. A further risk is competitive displacement—if larger incumbents aggressively bundle hardware, software, and managed services, or if agencies consolidate purchasing with preferred vendors, BK’s share could erode.
Downside confirmation would include a sequential decline in Radio segment revenue, shrinking order backlog (if disclosed), margin compression from price-based competition, and stagnant or declining Solutions uptake. Supply chain disruptions or cost overruns in the hybrid manufacturing model could further pressure profitability.
Benchmarks for BK Technologies’ Public Safety Transformation Ambitions
Quarterly Solutions segment revenue growth, as a proxy for SaaS adoption and product-market fit.
Number of active SaaS subscribers or agency deployments for InteropONE and LocateONE, if disclosed.
Gross margin trends, particularly as product mix shifts between hardware and software-driven revenue.
Updates on patent grants or new product launches in the BK ONE portfolio that signal ongoing innovation.
Visibility of multi-agency or statewide contract wins, indicating traction beyond single-customer sales.
Trends in government funding programs for P25 migration and emergency communications modernization.
Manufacturing cost variability and supply chain stability, especially as contract manufacturing relationships expand.
Utilization or expansion of the $6 million (extendable to $14 million) revolving credit facility, which could signal shifts in working capital needs or financial stress.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments