
Bright Mountain Media: Debt Deadlines, Customer Reliance, and the Search for Digital Advertising Viability
Its ability to refinance, diversify revenue, and adapt to a rapidly changing adtech landscape will determine whether it survives the coming year or succumbs to its structural vulnerabilities.
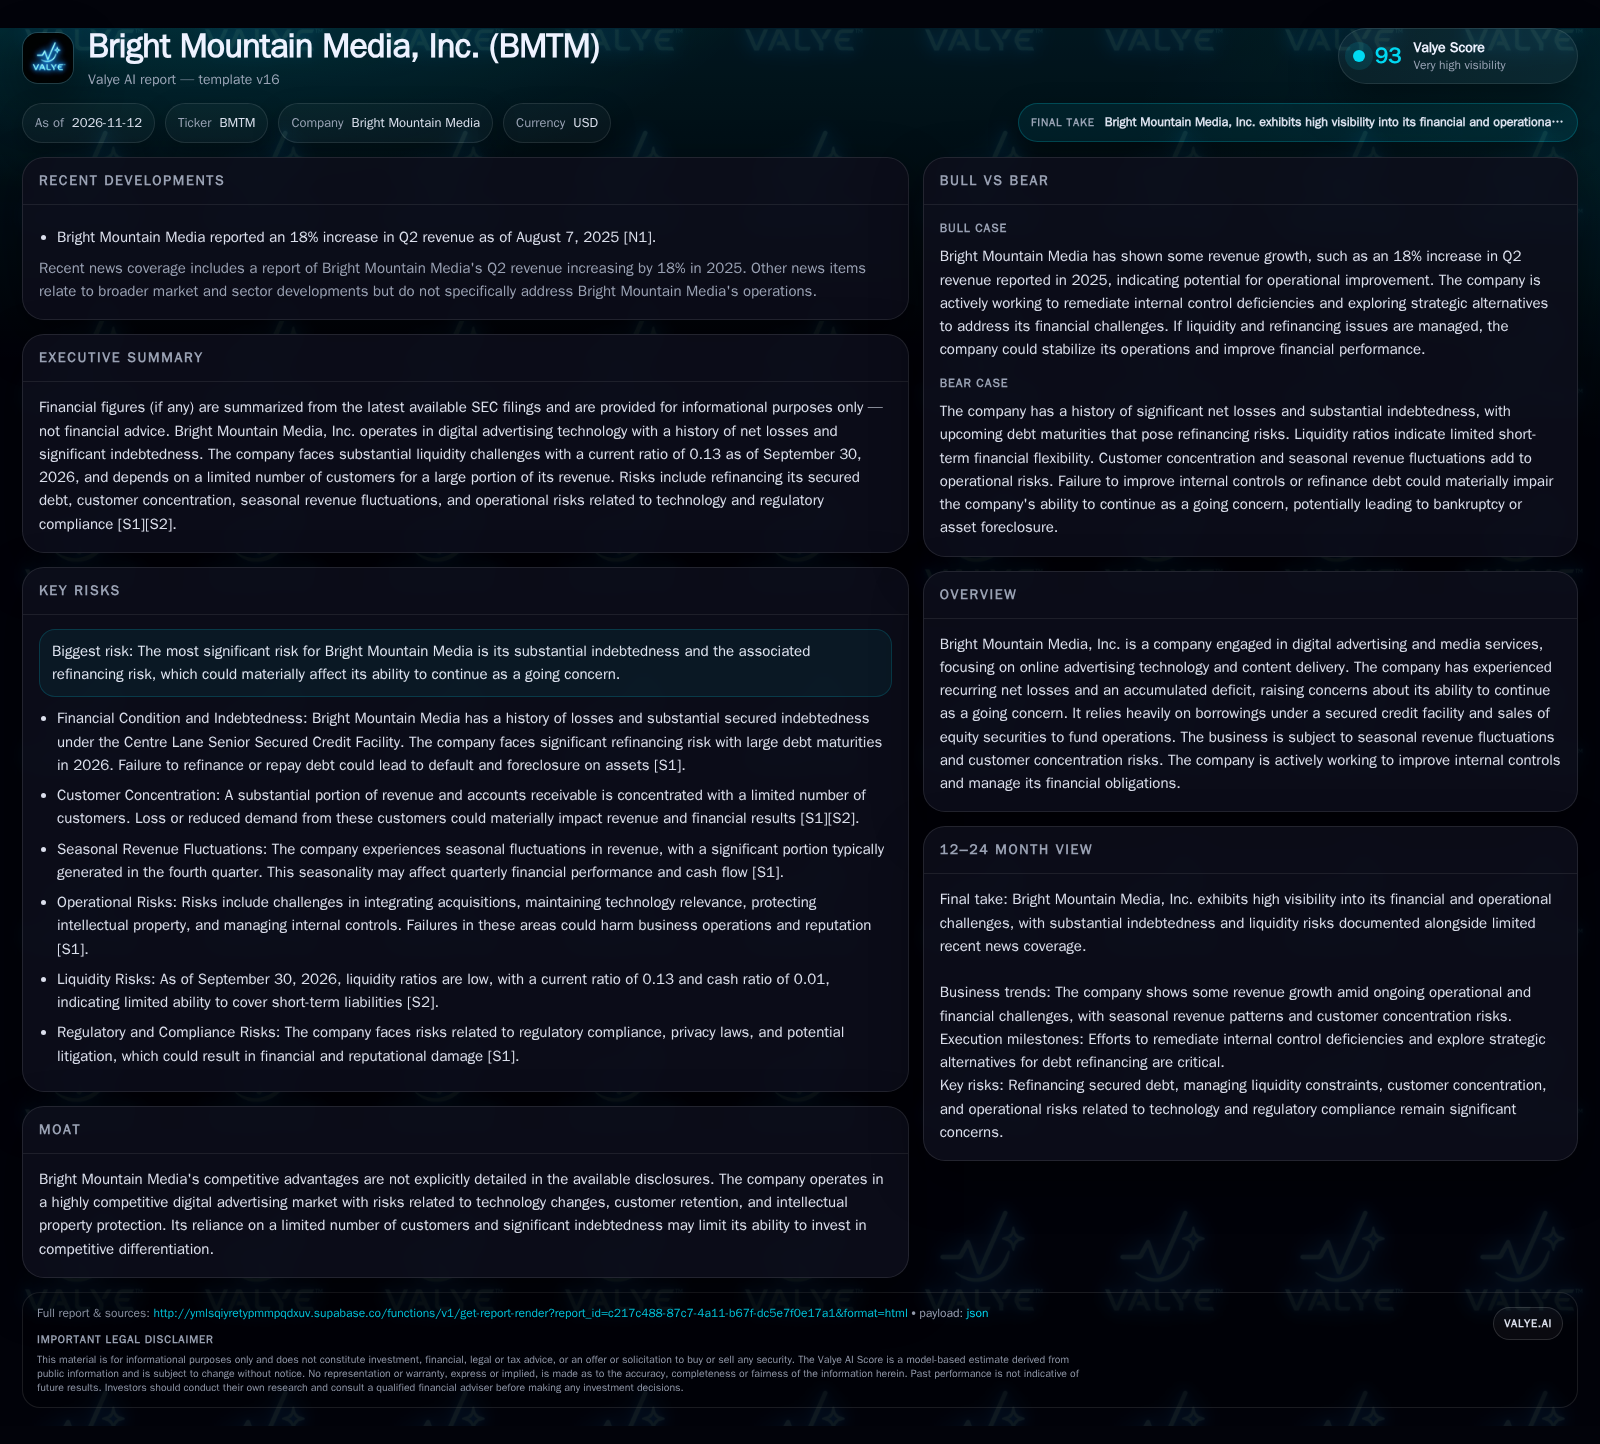
The company’s reliance on two major customers for much of its revenue, coupled with seasonal volatility and operational control issues, amplifies the risk. The next 12 months will hinge on refinancing, customer retention, and the ability to adapt in a competitive digital ad market. [S1] [S2]
The company’s digital advertising platform depends on just two major customers for much of its revenue, magnifying risk in an already volatile, seasonal business. As management scrambles to improve internal controls and seek refinancing, the next year will determine whether Bright Mountain can stabilize—or whether its structural weaknesses will force a reckoning.
Debt Maturity, Liquidity Crunch, and Customer Concentration Define the Near-Term Outlook
Bright Mountain Media’s most urgent reality is its capital structure: as of December 31, 2025, the company had $86.1 million outstanding under a senior secured credit facility, with major maturities due in 2026 [S1]. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2]
Operationally, the business remains heavily reliant on a small customer base, with two customers representing significant shares of both revenue and receivables [S1] [S2]. This amplifies the risk that even modest customer churn or delayed payments could have outsized impacts on cash flow and reported results.
Seasonality compounds these pressures: the company typically sees higher advertising revenues in the fourth quarter, making the timing of cash inflows and customer renewals even more critical [S1].
Finally, Bright Mountain is still in the process of addressing material weaknesses in its internal controls, raising questions about both the reliability and timeliness of its financial reporting [S1].
Adtech Revenue Mechanics and the Weight of Fixed Financial Obligations
Bright Mountain Media operates as an intermediary in digital advertising, likely generating revenue by connecting advertisers and publishers through its technology platform. In this model, gross profit is typically a function of ad volume, effective pricing (CPM or CPC), and the company’s take rate on transactions. However, industry economics are increasingly challenging: programmatic ad rates have faced downward pressure, while competition for publisher inventory and advertiser budgets has intensified.
Given the company’s history of net losses and insufficient gross profit to cover operating expenses, fixed costs—particularly debt service—are a significant drag. The $86.1 million in secured debt not only generates substantial interest expense but also constrains the company’s ability to invest in technology, sales, or product development. This high leverage means any revenue shortfall or customer loss could quickly erode remaining equity.
Seasonal revenue spikes offer periodic relief but also create cash flow volatility. The company’s reliance on external financing—both equity sales and borrowings—underscores its inability to self-fund growth or even sustain operations without outside capital [S1].
If Bright Mountain can improve its take rate, increase direct relationships with advertisers, or develop proprietary technology that attracts premium inventory, it could theoretically achieve higher margins. However, such investments require capital and executional bandwidth that are currently in short supply.
Navigating the Crowded Digital Ad Ecosystem: Where Bright Mountain Stands
Bright Mountain Media competes in a fragmented and highly competitive adtech sector, populated by large integrated platforms, niche technology providers, and publisher networks. Barriers to entry are modest for basic ad-serving technology, but scaling a differentiated, sticky platform requires either unique data, exclusive publisher relationships, or proprietary demand-generation tools.
The company’s lack of disclosed, durable competitive advantages—such as superior targeting algorithms, exclusive partnerships, or proprietary data—suggests its position is vulnerable to both price and technology substitution. Customer concentration further weakens its bargaining power: if a major customer defects to a rival platform or negotiates more favorable terms, revenue could decline rapidly.
Moreover, the broader adtech market is subject to ongoing disruption from changes in privacy regulation (such as GDPR and CCPA), browser restrictions on tracking, and shifts in advertiser preferences toward walled gardens or direct publisher deals. Companies with limited scale and potential financial flexibility are especially exposed to these secular shifts.
If Bright Mountain can carve out a niche—for example, by specializing in underserved verticals, leveraging unique content, or integrating value-added analytics—it might slow share loss. But without evidence of such differentiation, its competitive position appears tenuous.
How a Successful Refinancing and Customer Expansion Could Reverse Fortunes
The most optimistic scenario hinges on Bright Mountain securing a refinancing or restructuring of its $86 million debt, buying time to improve operations. If management can also remediate internal controls, restore confidence with customers, and diversify the revenue base, the company could stabilize cash flows and invest in platform enhancements.
A successful refinancing might involve extending maturities, lowering interest rates, or converting debt to equity, reducing near-term cash outflows. If Bright Mountain can concurrently win new customers—especially direct advertisers or premium publishers—it could reduce reliance on its top two accounts and smooth out seasonal volatility.
Confirmation of this scenario would come from announcements of new or renewed credit facilities, evidence of new customer contracts or partnerships, improved gross margin, and a reduced proportion of revenue from the top two customers. Conversely, a failure to secure refinancing or continued customer concentration would quickly falsify the upside case.
Most Likely Outcome: Debt Overhang Leads to Restructuring or Asset Sales
Given the scale of its debt versus cash position, the most plausible outcome is a period of financial distress culminating in a negotiated restructuring, asset sale, or bankruptcy filing. Absent a dramatic improvement in operating results or a third-party capital injection, Bright Mountain is unlikely to generate sufficient cash to repay or refinance its secured obligations.
Seasonal revenue may provide temporary relief, but continued customer concentration and legacy internal control issues suggest operational risks remain high. The company could seek to sell non-core assets, divest business lines, or pursue a merger with a better-capitalized peer.
Evidence supporting this scenario would include disclosures of covenant breaches, asset sale initiatives, or engagement with financial advisors. A stabilization of customer concentration or a meaningful increase in cash flow from operations would challenge the base case, but such developments appear unlikely given current facts.
Default Cascade: What Happens If Refinancing Fails and Customers Flee
The most severe risk is a rapid deterioration in liquidity if Bright Mountain cannot refinance or restructure its debt in time. In this scenario, even a modest delay or loss from one of its two major customers could trigger a cash crisis, leading to payment defaults, creditor action, or forced asset sales at distressed prices.
This could be compounded by continued weaknesses in internal controls, resulting in delayed or inaccurate financial reporting and loss of customer confidence. Regulatory fines, litigation, or technology outages could further erode value.
Confirmation would come in the form of missed debt payments, disclosure of creditor negotiations, or legal actions from lenders. Accelerating customer attrition, negative working capital trends, or auditor going concern warnings would further validate the downside.
Milestones That Will Decide Bright Mountain Media’s Survival or Restructuring
Any public disclosure of refinancing, extension, or restructuring of the Centre Lane Senior Secured Credit Facility.
Quarterly updates on customer concentration—specifically, the percentage of revenue and receivables from the top two customers (if disclosed).
Evidence of new customer wins or expansions outside the existing top-tier accounts.
Resolution of material weaknesses in internal controls, as indicated by auditor or management statements.
Trends in gross profit margin, especially any improvement that narrows the gap with operating expenses.
Changes in current and cash ratios, particularly any improvement in short-term liquidity (if disclosed).
Announcements of asset sales, divestitures, or engagement with restructuring advisors.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments