
Benitec Biopharma: Clinical Progress in Gene Therapy, but Commercialization Remains a Distant Prospect
Benitec Biopharma’s positive BB-301 clinical data and substantial cash reserves position it as a visible player in rare disease gene therapy. Yet, with no revenue and ongoing losses, the company’s future depends on translating trial milestones into regulatory and commercial success—a process fraught with uncertainty.
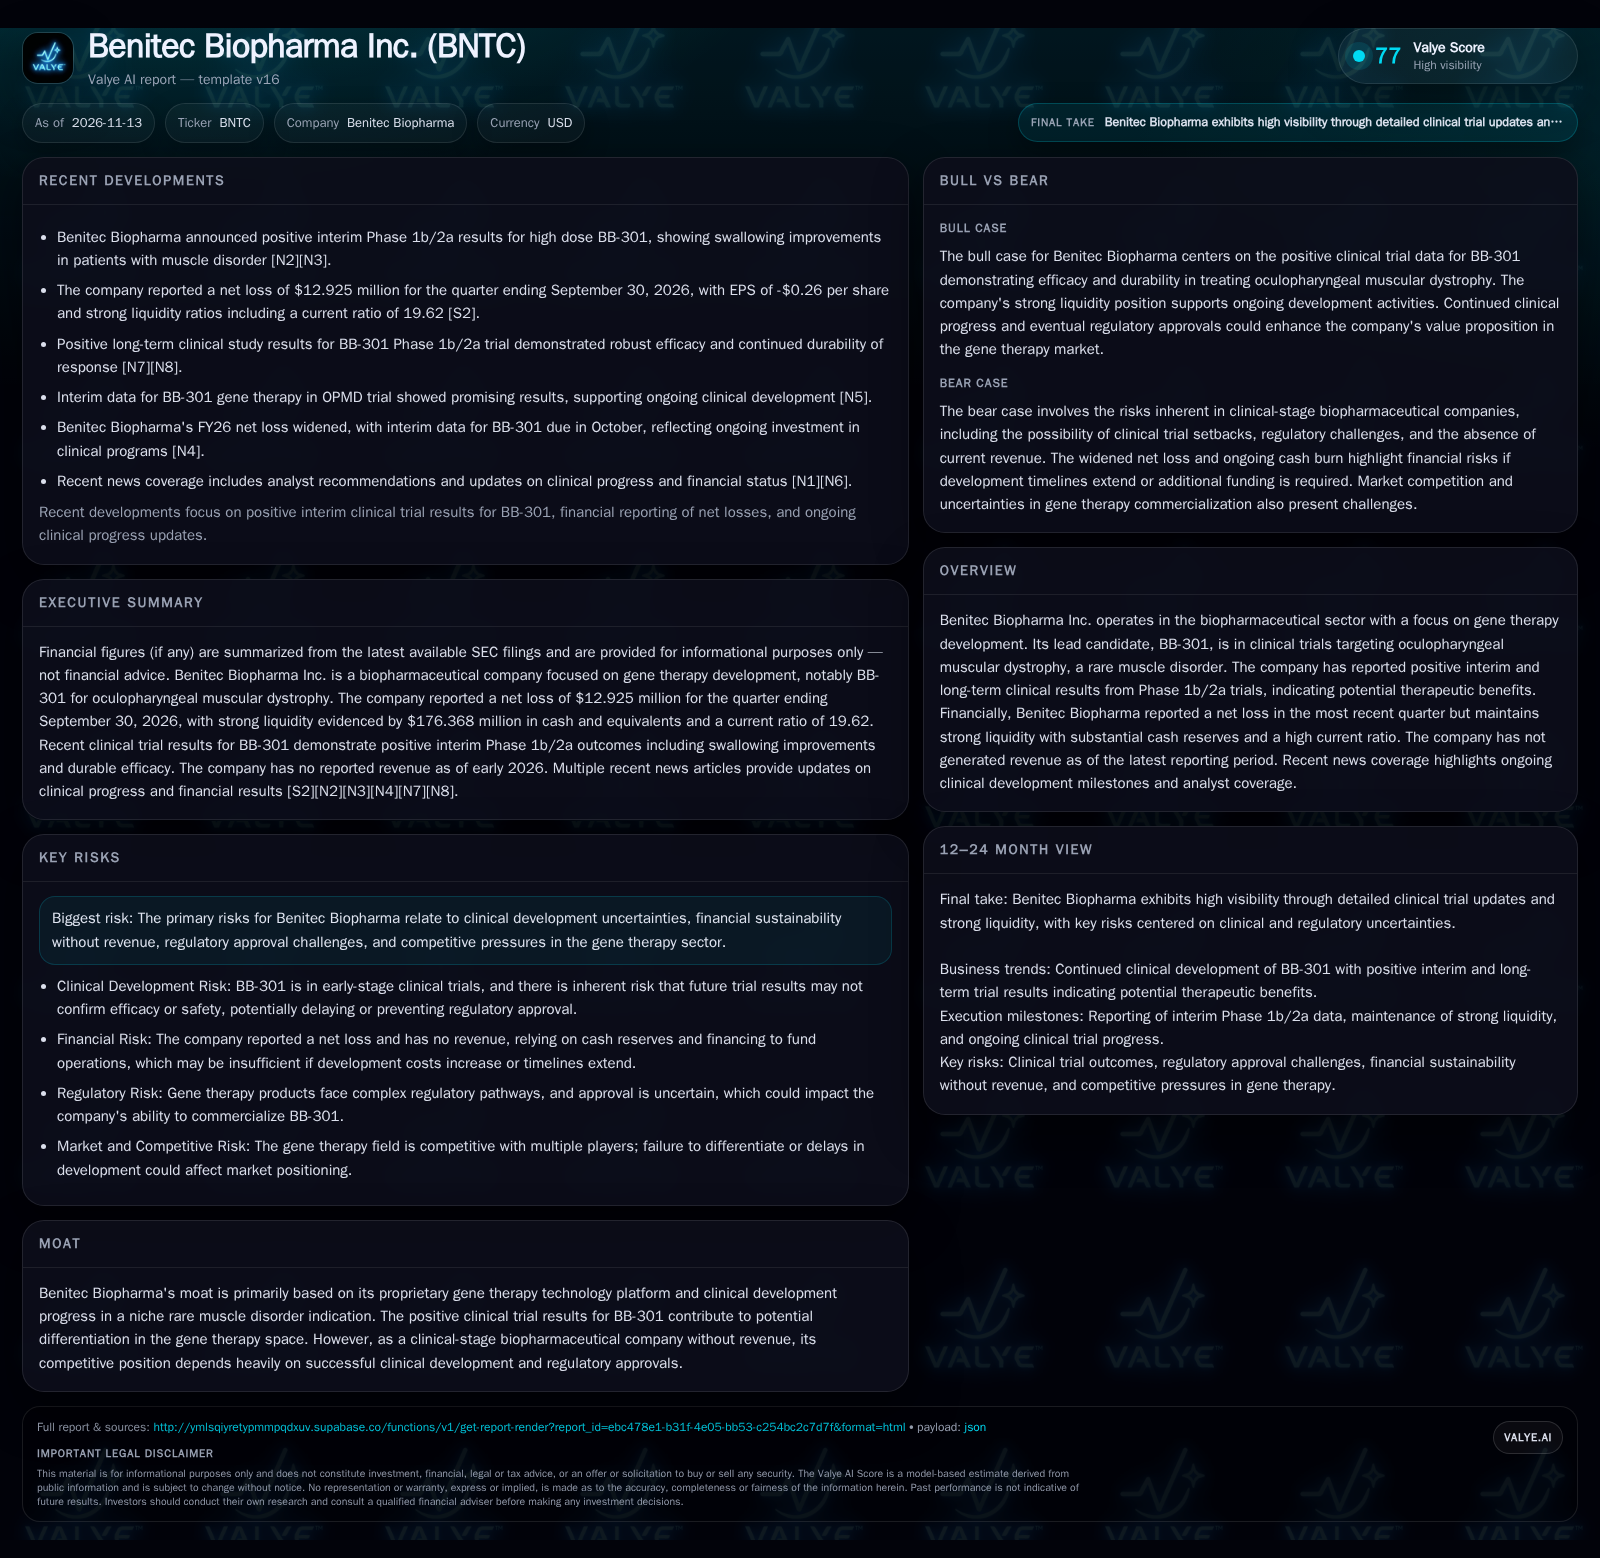
Benitec Biopharma has reported encouraging interim and long-term clinical data for BB-301, its lead gene therapy candidate for oculopharyngeal muscular dystrophy, and maintains a reported liquidity position with $176 million in cash as of September 2026. However, the company remains pre-revenue, with a widening net loss and all value contingent on successful clinical, regulatory, and eventual commercial outcomes. The next 12-24 months will test whether BB-301’s promise can be converted into a viable business.
Benitec Biopharma sits at a critical juncture in the gene therapy landscape, buoyed by promising clinical results for its lead asset, BB-301, targeting the rare disorder oculopharyngeal muscular dystrophy. With $176 million in cash and no revenue as of late 2026, Benitec’s future hinges on whether its positive clinical signals can be translated into regulatory approval and commercial traction. Investors and stakeholders must weigh the potential for BB-301 to break through against the realities of a long, capital-intensive path to market.
Recent Clinical Milestones and Financial Position Define Benitec’s Outlook
Benitec Biopharma’s most material recent developments center on its lead gene therapy candidate, BB-301, for oculopharyngeal muscular dystrophy (OPMD). Interim and long-term Phase 1b/2a clinical trial results have shown swallowing improvements and robust durability of response, suggesting potential efficacy in a condition with few therapeutic options [N2] [N3] [N7] [N8]. These clinical signals have increased Benitec’s visibility in the rare disease gene therapy field.
Financially, Benitec reported a net loss of $12.925 million for the quarter ending September 30, 2026, with no revenue recognized as of March 31, 2026. [S2]
The confluence of positive clinical readouts and ample cash reserves defines the company’s near-term outlook. However, Benitec is still a pre-commercial entity, and its ability to convert clinical success into a sustainable business remains unproven.
Beyond the immediate clinical and financial metrics, understanding Benitec's operational efficiency and strategic resource allocation is critical. The company's ability to manage clinical trial timelines, patient recruitment, and manufacturing scale-up within budget constraints will influence its capacity to sustain development activities. Additionally, the interplay between clinical milestones and financing strategies, including potential dilution or capital raises, will affect shareholder value and operational continuity. Monitoring how Benitec balances these factors amid evolving trial data can provide insight into its resilience and adaptability in a highly uncertain development environment.
Gene Therapy Economics: High Upfront Investment, Uncertain Future Revenue Streams
Benitec’s business model is typical of clinical-stage gene therapy companies: high upfront R&D spending, multi-year development timelines, and no revenue until regulatory approval and product launch. The company’s quarterly net loss reflects these dynamics, with cash burn primarily funding clinical trials, manufacturing scale-up, and regulatory activities.
Should BB-301 reach approval, the economics of gene therapy commercialization are marked by high initial pricing per patient—often justified by the potential for single-administration cures in rare diseases. However, revenue realization depends on market access, payer acceptance, and the size of the treatable patient population. For OPMD, a rare indication, the addressable market may be limited, constraining long-term revenue potential even in a successful launch scenario.
Operating leverage could be significant if fixed R&D and manufacturing investments are amortized over a substantial patient base, but in practice, rare disease therapies often face slow adoption curves and require ongoing commercial support.
Furthermore, the reimbursement landscape for gene therapies remains complex and evolving, particularly for ultra-rare diseases like OPMD. Payers may demand robust evidence of long-term efficacy and cost-effectiveness before approving high upfront prices. Conditional reimbursement models, outcomes-based agreements, or annuity payment structures could emerge as necessary adaptations to align stakeholder incentives. Benitec's ability to engage early with payers and health technology assessment bodies, and to design clinical programs that generate relevant real-world evidence, will be pivotal in shaping commercial viability. Failure to anticipate or adapt to these economic realities could constrain revenue generation despite regulatory approval.
Niche Indication Offers Differentiation, but Competitive and Regulatory Hurdles Persist
Benitec’s focus on OPMD gives it a degree of differentiation in the gene therapy landscape, as few companies are targeting this ultra-rare muscle disorder. The positive clinical data for BB-301 enhances the company’s profile among potential partners and investors.
However, the broader gene therapy sector is highly competitive, with multiple platforms and modalities under development for various rare and genetic diseases. Large pharmaceutical and biotech players, as well as other clinical-stage companies, represent both direct and indirect competitive threats. Additionally, advances in RNA therapeutics, gene editing, and alternative modalities could alter the treatment paradigm over time.
Benitec’s moat is currently based on proprietary technology and early clinical results. This advantage is fragile and could erode if competitors achieve faster regulatory progress, demonstrate superior efficacy or safety, or secure commercial partnerships ahead of Benitec.
In addition to direct competitors, Benitec faces the strategic challenge of technological obsolescence inherent in rapidly advancing fields like gene therapy. The company's proprietary platform must demonstrate not only clinical efficacy but also scalability and manufacturability to maintain a competitive edge. Advances in vector design, delivery mechanisms, or gene editing technologies could render existing approaches less attractive. Hence, continuous innovation and potential platform diversification may be necessary to sustain differentiation. Strategic collaborations or licensing deals could facilitate access to complementary technologies, mitigating the risk of being outpaced by more agile or better-resourced competitors.
If BB-301 Achieves Regulatory Approval and Adoption, Value Creation Could Be Significant
The favorable scenario for Benitec is predicated on continued positive clinical results for BB-301, leading to successful completion of pivotal trials and eventual regulatory approval. If efficacy and durability are maintained in larger, later-stage studies, and if safety remains acceptable, BB-301 could become the first approved therapy for OPMD.
Demonstrable clinical benefit would support pricing power in a rare disease with high unmet need, and positive reimbursement decisions could drive uptake in eligible patients. Successful commercialization, even in a small patient population, would validate Benitec’s technology platform and potentially open up partnering or acquisition opportunities.
Confirmation of this scenario would include: clear pivotal trial design and enrollment progress, ongoing robust clinical outcomes, constructive regulatory feedback, and evidence of commercial or strategic partnerships.
Clinical Progress Continues, but Commercialization Remains Several Years Away
The most plausible path for Benitec involves incremental progress in BB-301’s clinical development, with additional interim data and ongoing engagement with regulators.
In this scenario, regulatory approval is not imminent, and revenue remains absent for several years. Benitec may seek to partner BB-301 or its platform with larger companies to share development risk and access commercialization infrastructure.
Falsification would come from either major clinical setbacks or an unexpected acceleration toward pivotal data and regulatory filings.
Setbacks in Clinical Development or Regulatory Review Could Force Strategic Retrenchment
The adverse scenario for Benitec centers on negative or equivocal clinical trial results for BB-301, which could halt development or trigger additional costly studies. Regulatory setbacks—such as requests for larger or longer trials, new safety signals, or manufacturing challenges—would extend timelines and increase cash burn.
Without revenue or near-term partnering deals, Benitec could face a funding shortfall if progress stalls, leading to down-round financings, asset sales, or pipeline reprioritization. The company’s position as a single-asset, pre-commercial biotech heightens its vulnerability to binary outcomes.
This scenario would be confirmed by negative clinical data, failure to advance to pivotal trials, regulatory delays, or a sharp increase in quarterly losses leading to going-concern warnings.
Milestones That Will Determine Whether Benitec Converts Promise into Value
Progression to pivotal clinical trials for BB-301, including trial design approval and patient enrollment updates.
Disclosure of additional interim or long-term efficacy and safety data from ongoing BB-301 studies.
Regulatory feedback or guidance from agencies such as the FDA or EMA regarding BB-301’s development path.
Cash burn rate and updates on runway projections relative to major clinical milestones.
Any announcements of partnering, licensing, or strategic collaboration agreements.
Evidence of commercial planning, including manufacturing scale-up, reimbursement strategy, or early market access initiatives.
If disclosed, updates on the competitive landscape for OPMD or similar gene therapy indications.
Potential pipeline expansion or new indications leveraging Benitec’s gene therapy platform, if announced.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments