
Jade Biosciences: Advancing Autoimmune and Kidney Disease Therapies Amid Capital-Intensive Clinical Milestones
Jade Biosciences is pushing forward with two lead therapeutic candidates—JADE301 for dermatomyositis and JADE101 for IgA nephropathy—while shoring up its balance sheet through a significant $150 million equity raise. The company now faces the dual challenge of converting clinical progress into value and managing the high costs and risks typical of biotech R&D.
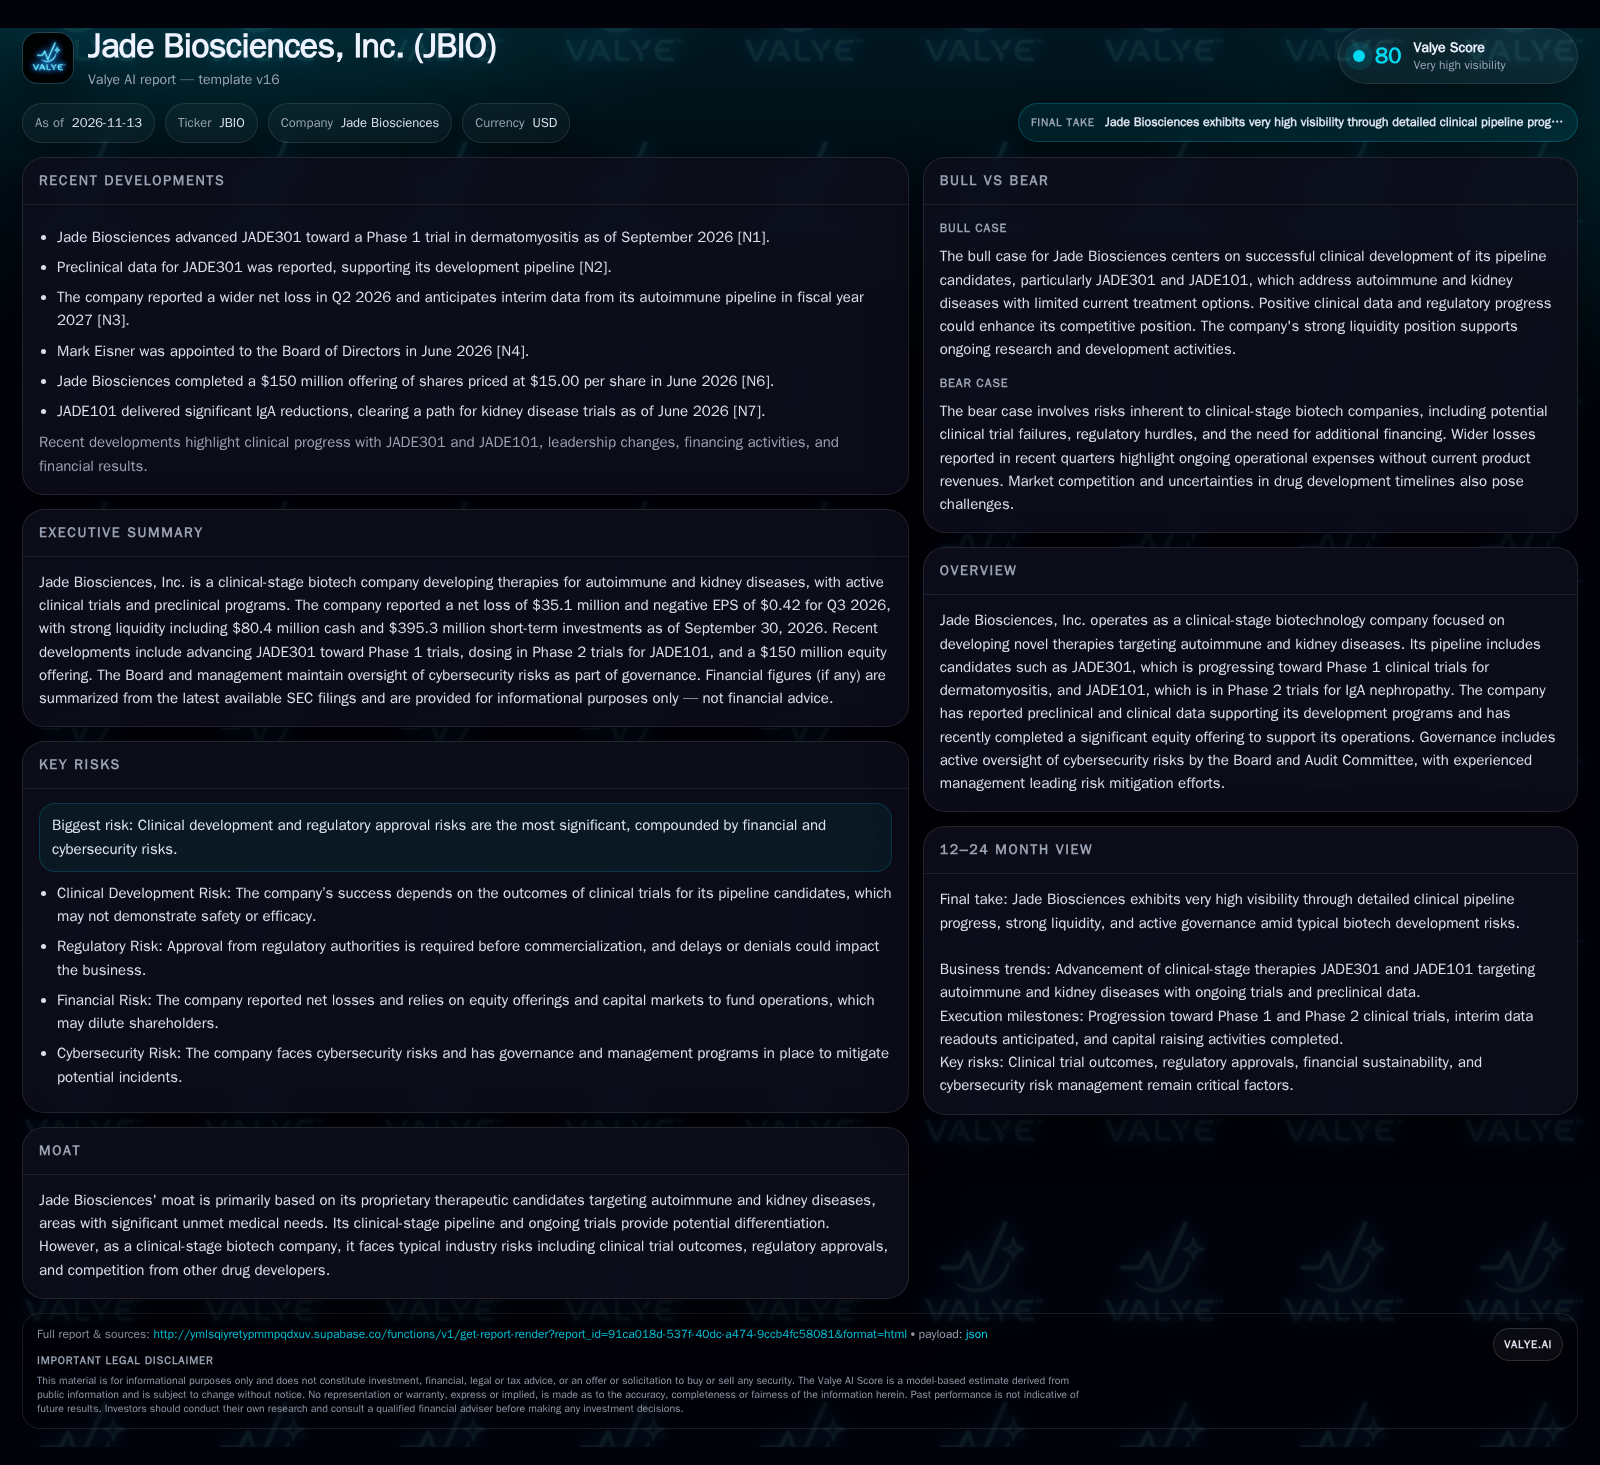
Jade Biosciences is a clinical-stage biotech with lead assets in autoimmune and kidney diseases. Recent pipeline advances include moving JADE301 toward Phase 1 trials and dosing the first patient in a Phase 2 trial for JADE101. The company raised $150 million in June 2026, resulting in $485.6 million in current assets against $30.3 million in current liabilities as of September 2026. With interim data from its autoimmune pipeline expected in FY27, Jade’s near-term fortunes hinge on clinical readouts and capital efficiency in a sector defined by binary outcomes and funding needs. [N1] [N6] [S2]
Jade Biosciences, Inc. stands at a familiar but crucial crossroads for clinical-stage biotech: flush with fresh capital and advancing lead programs, but still pre-revenue and exposed to the high-stakes uncertainties of drug development. Its two main assets—JADE301 (targeting dermatomyositis) and JADE101 (for IgA nephropathy)—are progressing through early and mid-stage trials, with interim data expected in fiscal 2027. Recent financial moves, including a $150 million equity raise, give Jade a substantial liquidity buffer, but the company’s ability to translate pipeline progress into commercial or partnership value remains untested. The next 12-18 months will clarify whether Jade’s scientific promise can withstand the realities of clinical, regulatory, and capital market pressures.
Recent Pipeline Progress and Capital Raise Shape Jade’s Short-Term Trajectory
Jade Biosciences is currently advancing two lead drug candidates: JADE301, which moved toward a Phase 1 clinical trial in dermatomyositis as of September 2026, and JADE101, which entered a Phase 2 trial for IgA nephropathy and has demonstrated significant IgA reductions in patients. These developments push the company's pipeline into more value-defining clinical stages, especially as interim data from autoimmune programs are anticipated in fiscal 2027—potentially setting up key inflection points for valuation and partnering interest. [N1] [N7] [N3]
On the financial side, Jade completed a $150 million equity offering in June 2026, significantly strengthening its cash position. As of September 30, 2026, Jade reported $80.4 million in cash and $395.3 million in short-term investments, totaling $485.6 million in current assets against $30.3 million in current liabilities. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [N6] [S2]
Pipeline Economics: R&D Burn, Funding Cycles, and the Quest for Commercialization
Jade Biosciences’ business model is typical of clinical-stage biotechnology: heavy front-loaded R&D spending in pursuit of high-value, high-risk pipeline milestones. The company currently generates no product revenue, and its economics are dominated by operating losses and periodic capital raises. With a net loss of $35.1 million in the most recent quarter and a large cash reserve from its $150 million offering, Jade’s operating leverage is entirely negative until a candidate reaches a licensing deal, partnership, or regulatory approval. [S2] [N6]
The core economic lever is successful clinical progression—each positive data readout or regulatory milestone has the potential to dramatically increase asset value, attract partnership capital, or enable premium licensing deals. Conversely, any clinical setback can erode value rapidly. Fixed costs are dominated by clinical trial expenses, G&A, and ongoing preclinical research, while variable costs (such as COGS) will only emerge post-approval. The company’s ability to stretch its cash runway hinges on careful trial design, milestone pacing, and the possibility of non-dilutive funding through grants or partnerships.
Capital needs are likely to remain substantial; even with $485.6 million in current assets, the pace of clinical development and potential expansion into additional indications could require further fundraising ahead of commercialization. The absence of recurring revenue or cash flow until late-stage success means Jade’s economics will remain binary and volatile in the near term.
Positioning in the Autoimmune and Kidney Disease Therapeutics Landscape
Jade Biosciences is targeting autoimmune and kidney diseases—markets with significant unmet medical need and limited effective therapies. In dermatomyositis, JADE301 enters a competitive field that includes both established immunosuppressants and a wave of novel biologics and small molecules under development by larger pharmaceutical and mid-cap biotech companies. Success will depend on demonstrating superior efficacy, safety, or convenience over both standard-of-care and emerging therapies.
In IgA nephropathy, JADE101’s reported significant IgA reductions are promising, but the asset must ultimately show clinical benefit on hard endpoints such as proteinuria reduction or kidney function preservation to stand out. The competitive set includes both approved drugs (such as SGLT2 inhibitors and corticosteroids) and multiple late-stage pipeline contenders. Larger competitors may have advantages in commercial infrastructure, regulatory experience, and access to trial sites, but Jade could carve out a niche if it achieves clear differentiation or partners with a commercial-stage pharma.
Switching frictions in these indications are often high due to chronic disease management and the risks associated with changing therapies, but payers and providers are increasingly demanding strong clinical and economic evidence. Network effects and ecosystem advantages are generally less relevant than in digital therapeutics or platform tech, so Jade’s moat is likely to come from IP protection, data exclusivity, and clinical differentiation.
Clinical Wins Drive Licensing Value and Strategic Interest
The most favorable scenario for Jade is a series of positive clinical readouts for JADE301 and JADE101, especially if interim data in fiscal 2027 demonstrate strong efficacy and safety signals. This could unlock partnership or licensing deals with large pharma companies seeking to bolster their autoimmune or nephrology pipelines, potentially providing non-dilutive capital and validation.
Such clinical success would likely drive a step-change in Jade’s valuation, allowing the company to raise additional capital on more attractive terms and possibly accelerate additional indications or pipeline assets. Confirmation would come from external validation—such as a partnership announcement, licensing deal, or a significant uptick in institutional investment following data releases. Conversely, a lack of partnering interest or muted market reaction to positive data would challenge the upside thesis.
Incremental Pipeline Progress Amid Ongoing Cash Burn
The most plausible path is a measured progression of JADE301 and JADE101 through their respective clinical milestones, with interim data in fiscal 2027 providing mixed or moderately positive results.
In this scenario, the company avoids major clinical failures but does not achieve an outright breakthrough or lucrative partnership within the next 12-18 months. Jade may pursue additional capital raises if data are promising but not transformative, or if it chooses to expand the pipeline or enter new indications. Evidence to confirm this scenario would include steady but not dramatic changes in R&D spend, modest increases in headcount, and continued communications about trial milestones and cash runway. A falsification would be an abrupt halt in development or a major clinical setback.
Clinical Setbacks or Delays Force Strategic Retrenchment
The primary risk is negative or inconclusive clinical data from either JADE301 or JADE101, particularly if interim results in fiscal 2027 fail to demonstrate meaningful efficacy or reveal safety concerns. This could sharply reduce Jade’s valuation, limit access to new capital, and force the company to halt or shelve key programs.
In this scenario, Jade may be compelled to restructure, downsize, or seek strategic alternatives such as asset sales or mergers. Confirmation would come from public announcements of trial discontinuations, significant R&D cuts, or a sharp drop in cash reserves without corresponding pipeline progress. A failed or heavily discounted capital raise would also signal the downside case, as would a lack of interest from potential partners or acquirers following negative data.
Milestones That Will Define Jade Biosciences’ Value Trajectory
Interim clinical data readouts for JADE301 in dermatomyositis and JADE101 in IgA nephropathy, expected in fiscal 2027, will be pivotal in shaping future pipeline value and capital strategy. [N3]
Updates on patient enrollment rates and trial progress for both lead programs—if disclosed—would clarify operational execution and burn rate.
Partnership, licensing, or collaboration announcements with larger pharmaceutical companies would provide external validation and potential non-dilutive funding.
Cash burn rate and changes in R&D expenditure, particularly in relation to clinical trial milestones, will test the sustainability of current liquidity. [S2]
Regulatory feedback, such as IND clearances or fast-track designations, would help assess the probability of successful advancement toward commercialization.
Board and management changes, especially those involving clinical or commercial leadership, could signal shifts in strategic direction or preparedness for late-stage development. [N4]
Any additional capital raises or debt financings—especially if terms are unfavorable—would indicate pressure on the existing runway and potential dilution risk.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments