
Milestone Scientific: Commercializing Medical Innovation While Navigating Listing and Adoption Hurdles
Milestone Scientific is leveraging regulatory clearances to expand its medical device footprint beyond its core dental franchise, but faces slow clinical adoption, equity compliance pressures, and capital needs that could shape its next phase.
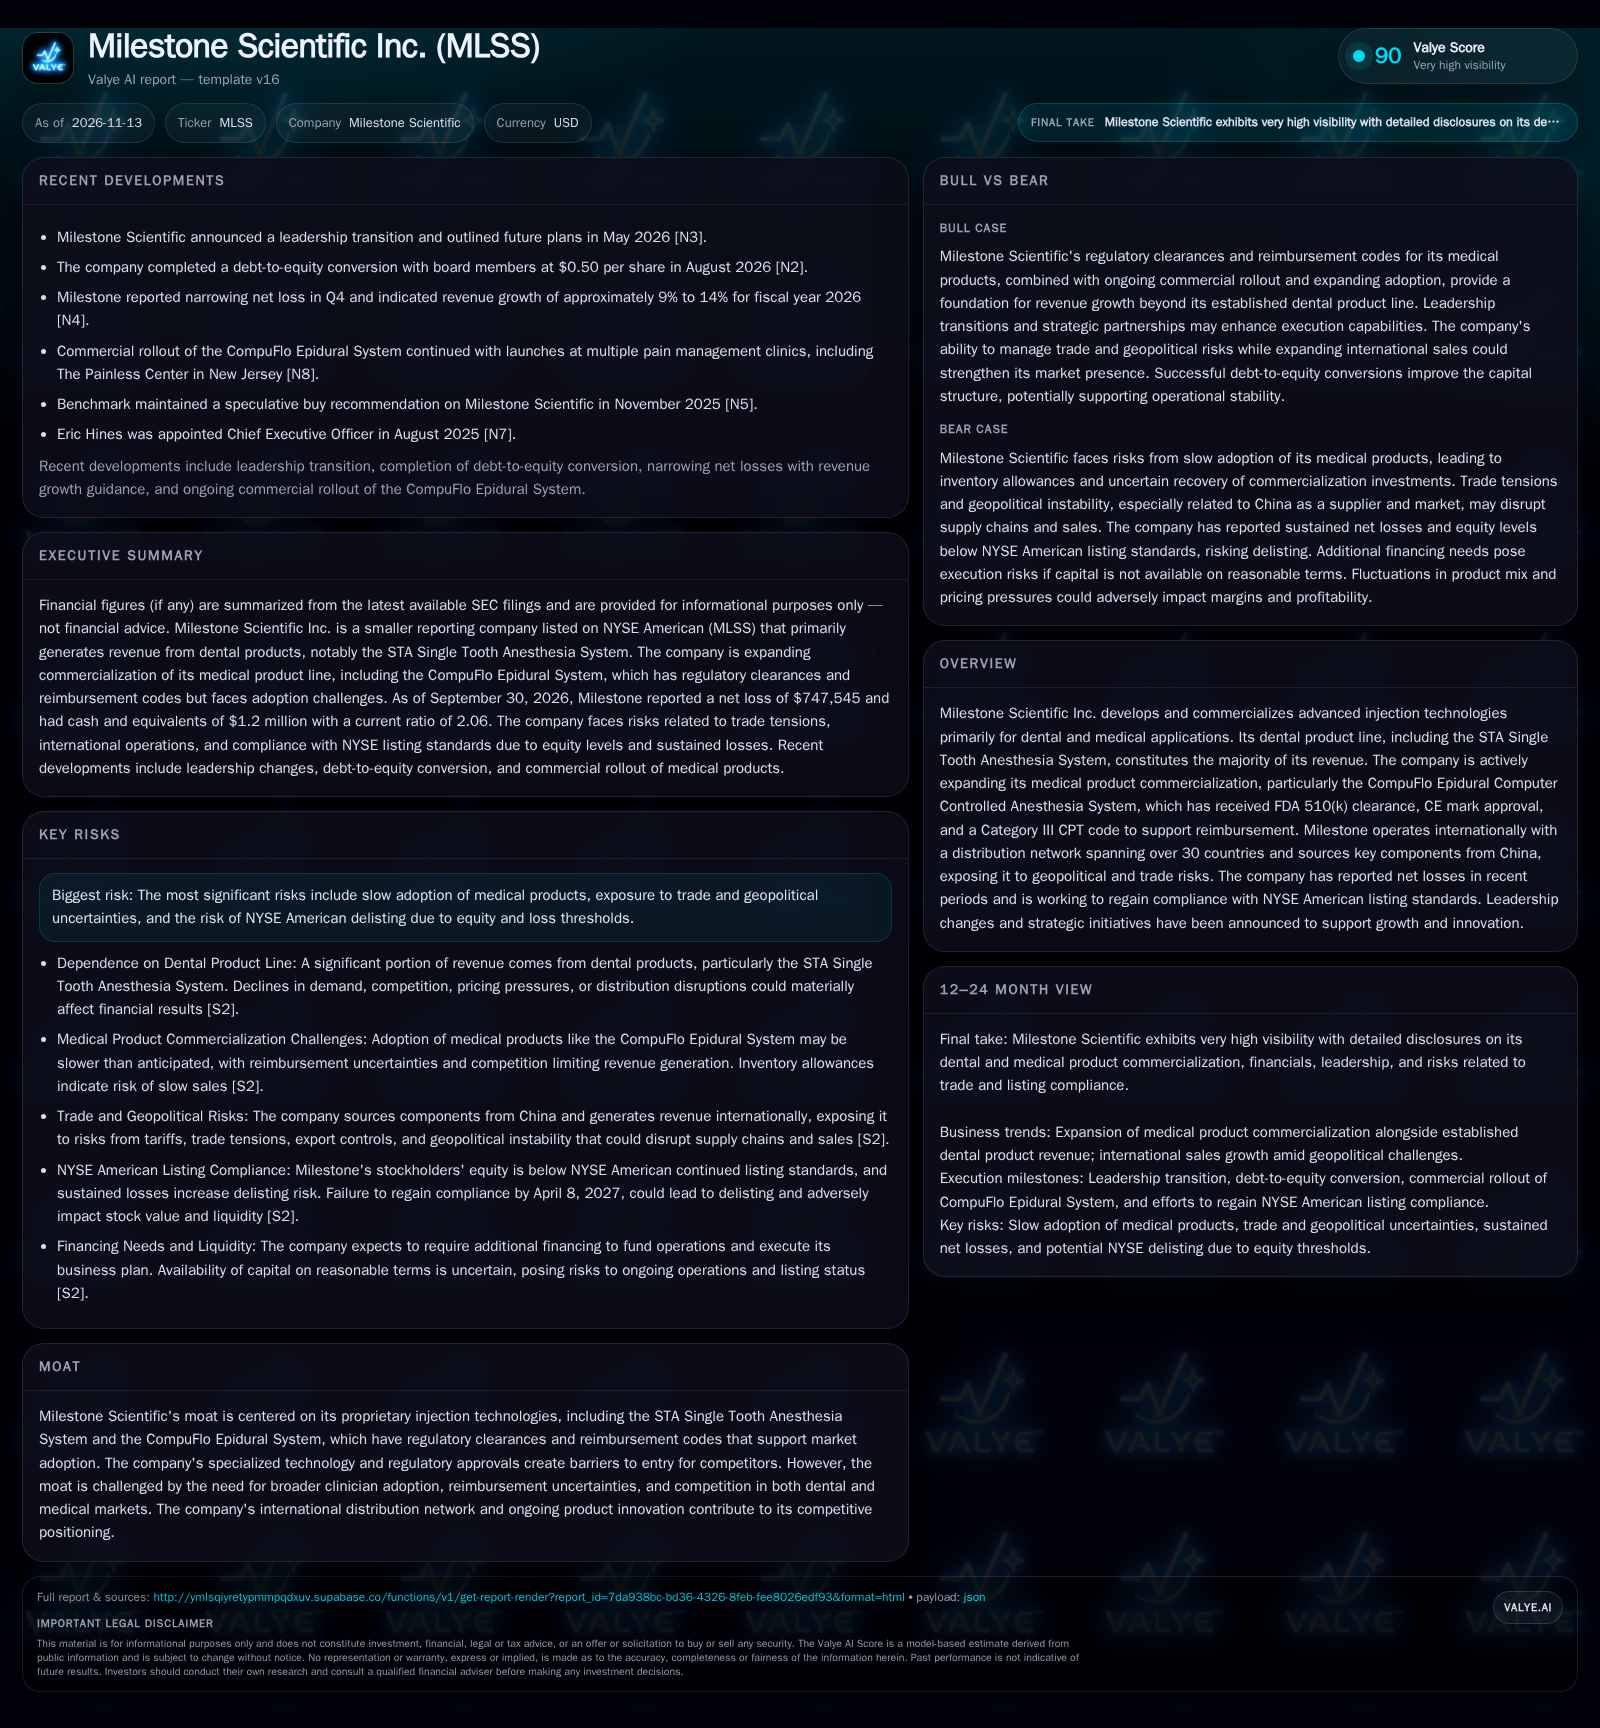
Milestone Scientific’s core dental business continues to anchor revenue, while the company pursues growth in medical devices, notably with the CompuFlo Epidural System. Despite achieving regulatory milestones and early commercial launches, adoption in the medical segment remains slow, contributing to persistent losses and equity levels below NYSE American standards. Leadership changes, a debt-to-equity conversion, and a targeted commercialization push aim to reverse the trend, but execution and external risk factors—especially around financing and international supply chains—are likely to dictate near-term outcomes. [S2] [N2] [N4] [N8]
Milestone Scientific stands at a strategic crossroads: its established dental technology generates the bulk of revenue, but the company’s future hinges on successful commercialization of its medical device portfolio, especially the CompuFlo Epidural System. While regulatory and reimbursement milestones have been achieved, clinical adoption is lagging, and persistent net losses have pushed equity below NYSE American listing standards. With leadership changes, a recent debt-to-equity conversion, and targeted commercial launches, Milestone is actively attempting to reposition itself. The next 12-18 months will test whether innovation and execution can outpace mounting financial and operational risks. [S2] [N2] [N8]
Recent Developments Define Strategic Inflection
Milestone Scientific’s immediate context is shaped by four material developments. First, its dental franchise—anchored by the STA Single Tooth Anesthesia System—remains the primary revenue source, providing a cash-generating base as the company seeks to expand its medical device portfolio. Second, the CompuFlo Epidural System has achieved FDA 510(k) clearance, CE mark approval, and a CPT code, but real-world adoption has lagged these regulatory milestones, evidenced by a material allowance for slow-moving medical inventory. Third, the company’s total stockholders’ equity sits at $3.7 million, below NYSE American listing standards, triggering a compliance plan submission and the risk of delisting if not remedied by April 2027. Fourth, Milestone reported a Q3 2026 net loss of $747,545 and cash of $1.2 million, alongside a board-level debt-to-equity conversion at $0.50/share, reflecting both financial pressure and an attempt to shore up the capital structure. These facts collectively frame a company needing to convert innovation into commercial traction while stabilizing its financial footing. [S2] [N2] [N8]
How Milestone’s Commercial Model Could Drive—or Drain—Value
Milestone’s business model relies on the sale of proprietary injection systems and consumable handpieces, a structure that can support recurring revenue and attractive gross margins if utilization rates are high. The dental segment, led by the STA system, benefits from established distribution and a clear clinical use case, driving steady product pull-through. In contrast, the medical division, particularly the CompuFlo Epidural System, faces the typical hurdles of new device adoption: clinician training, workflow integration, and reimbursement realization. While regulatory clearances and a CPT code provide an entry point, actual payer coverage and hospital purchasing cycles often lag, leading to inventory build-up and working capital drag.
Operating leverage is plausible if medical device adoption accelerates, as incremental revenue would largely flow through a fixed-cost base post-commercialization. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. The company’s reliance on international sales and Chinese components introduces FX and supply chain volatility, which could affect both gross margin and cost structure. Without a step-change in medical product uptake, the economics risk being dominated by sunk costs, slow-moving inventory, and dilution from future capital raises.
Proprietary Technology Meets Adoption and Substitution Headwinds
Milestone’s core advantage lies in proprietary injection systems with regulatory and reimbursement credentials, creating technical and compliance barriers for new entrants. In dental, this has translated to defensible share in a niche segment. In medical, the CompuFlo system’s FDA clearance and CPT code theoretically position it ahead of many small device peers, but the practical moat is only as wide as clinician willingness to change established anesthesia protocols.
Key competitive counterforces include incumbent device vendors, alternative pain management modalities, and the inertia of existing clinical workflows. The capital and training required for hospitals to adopt new anesthesia systems are nontrivial, and reimbursement codes do not always equate to attractive payment rates or rapid payer uptake. Internationally, Milestone faces both local competitors and macro risks—such as tariffs and export controls—given its reliance on Chinese components and sales in China. The company’s competitive fate may ultimately depend less on technology and more on execution in commercial education, clinical evidence generation, and payer engagement.
Unlocking Medical Device Adoption Could Transform Economics
The most favorable scenario for Milestone is one in which the CompuFlo Epidural System achieves meaningful clinical adoption, driven by expanding Medicare and private payer reimbursement, successful launches at additional pain management and spine clinics, and growing clinician advocacy. This would accelerate consumable handpiece sales, reduce inventory allowances, and allow the company to leverage its fixed cost base for margin expansion.
Evidence that would confirm this scenario includes a sustained uptick in medical segment revenue, reductions in inventory write-downs, new customer wins at high-volume clinics or hospital systems, and positive physician testimonials or published clinical studies. If disclosed, metrics such as reorder rates for CompuFlo consumables, payer mix, and reimbursement realization would provide strong signals. A return to positive operating cash flow and compliance with NYSE equity standards would further validate a successful inflection.
Incremental Progress Anchored by Dental Stability, Medical Gradualism
The most plausible path is a gradual evolution: dental products continue to generate the majority of revenue, providing a stable—if modest—foundation. Medical device sales grow slowly, constrained by the pace of clinician adoption, payer uptake, and hospital purchasing bureaucracy. Inventory allowances may persist, and working capital remains tight, but not acutely stressed. The company manages to retain its NYSE American listing by incrementally rebuilding equity, possibly through small capital raises or cost controls.
This scenario would be confirmed by single-digit percentage growth in total revenue, continued net losses but with narrowing magnitude, and a slow but steady increase in the number of medical sites adopting the CompuFlo system. Watchpoints would include a lack of major new customer announcements, ongoing inventory build-up, and the absence of transformative reimbursement wins or clinical partnerships.
Prolonged Medical Adoption Lags and Capital Constraints Intensify Risk
In the adverse scenario, medical product adoption remains sluggish despite regulatory clearances and initial commercial launches. Inventory tied up in slow-moving medical SKUs weighs on cash conversion, while the dental base is insufficient to offset ongoing losses. If capital markets become less receptive or terms deteriorate, Milestone could struggle to raise the funds needed to sustain operations—especially with delisting risk looming due to persistent low equity.
Confirmation of this scenario would come from flat or declining medical product revenue, continued or growing inventory write-downs, worsening net losses, and adverse listing actions by the NYSE American. A major supply chain disruption or escalation in China trade tensions could further impair both cost structure and international sales, compounding financial stress.
Milestones That Will Clarify Commercial Traction and Financial Viability
Monthly or quarterly trends in CompuFlo Epidural System revenue—especially sequential growth rates—would help gauge adoption velocity. If disclosed, this metric would be a primary indicator of medical commercialization success.
The magnitude and trend of inventory allowances or write-downs for medical finished goods will signal whether adoption is accelerating or inventory risk is deepening.
Updates on the number and profile of new pain management and spine clinics adopting CompuFlo, including any expansion into large hospital systems, would test the breadth of market penetration.
Any announcement of new or expanded payer reimbursement agreements, especially with major private insurers, would materially improve the adoption outlook.
Disclosure of reorder rates for CompuFlo consumables (if provided) would clarify whether initial placements are converting to recurring usage.
Progress updates on the NYSE American compliance plan, including quarterly equity levels and any regulatory communications, will signal listing risk trajectory.
Reports of additional capital raises, debt financing, or strategic investments—along with their terms—would indicate both the cost and availability of funding.
Material changes in the geopolitical environment affecting Chinese supply chains or international sales would have immediate operational and financial implications.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments