
Brilliant Earth’s Omnichannel Expansion: Operational Leverage, Mission-Driven Differentiation, and the Stakes of Showroom Scale
Brilliant Earth is posting improved profitability and modest sales growth as it doubles down on its asset-light, omnichannel model blending technology with personalized retail. The ability to convert showroom momentum into sustainable margin expansion amid macro and competitive headwinds will determine whether its capital-efficient approach can scale beyond the engagement ring core.
Brilliant Earth’s Q3 2026 results show a return to profitability and improved EBITDA margins, underpinned by showroom expansion and a digital-first, asset-light business model. The company's unique positioning around ethical sourcing and technology-enabled customer experience offers a differentiated value proposition, but the challenge is to maintain growth and margin gains as it broadens its assortment and faces a fragmented, highly competitive jewelry market. Macroeconomic volatility, seasonality, and the risks of scaling physical retail remain central variables for the next phase.
Brilliant Earth Group, Inc. stands at a pivotal moment as it translates its digitally native, mission-driven brand into a growing network of U.S. showrooms. Recent results show the company regaining profitability and expanding EBITDA margins, signaling that its omnichannel, asset-light approach can generate operating leverage. However, as Brilliant Earth pushes further into the fragmented fine jewelry market and faces macroeconomic uncertainty, the question is whether its blend of technology, ethical sourcing, and targeted retail expansion can drive sustainable growth and defend margins against both legacy players and digital upstarts.
Recent Financials Signal Operational Improvement, But Growth Remains Measured
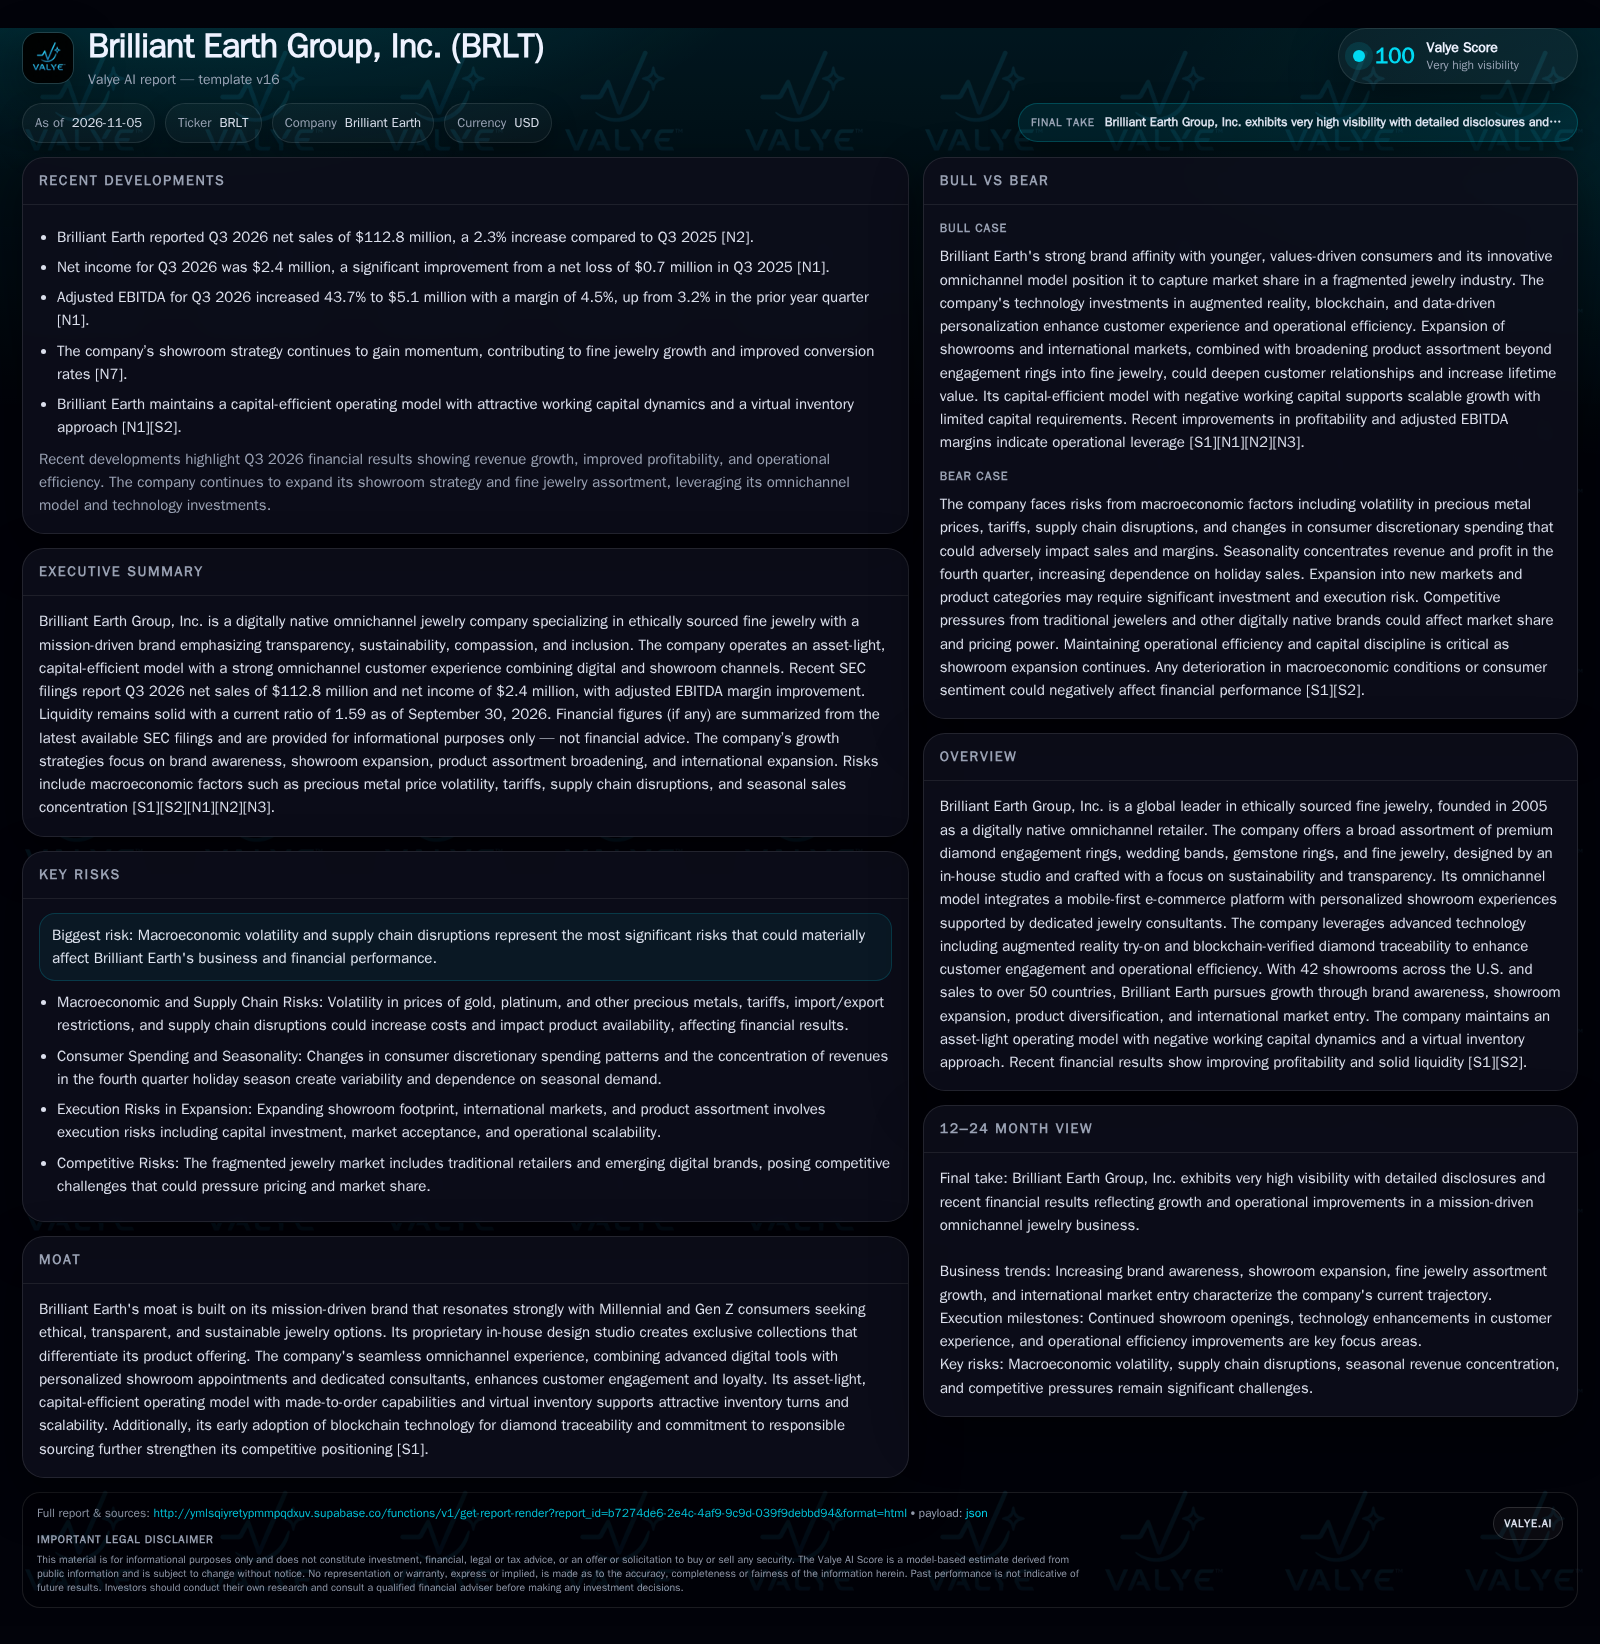
Brilliant Earth reported Q3 2026 net sales of $112.8 million, a 2.3% increase year-over-year, alongside a return to profitability with $2.4 million in net income after a loss in the prior year period [N2] [N1] [S2]. Adjusted EBITDA rose to $5.1 million (4.5% margin), up from $3.6 million (3.2% margin) a year ago, pointing to improved operational leverage [N1] [S2]. For the first nine months of 2026, revenue grew 4.6% to $327.4 million, though the company still posted a net loss of $5.2 million for that period [S2]. Liquidity as of September 30, 2026 stood at $76.2 million in cash, with a current ratio of 1.59 [S2].
The company’s ongoing showroom rollout is cited as a key driver of fine jewelry growth and improved conversion rates [N7]. However, macroeconomic risks, including consumer discretionary spending volatility, precious metal price swings, and continued supply chain uncertainty, remain material concerns [S1] [S2]. Seasonality is also a material factor, with a disproportionate share of sales and profit concentrated in the holiday-driven fourth quarter [S1].
How Brilliant Earth’s Asset-Light Model and Virtual Inventory Shape Profit Dynamics
Brilliant Earth’s business model is designed for capital efficiency: made-to-order jewelry, a virtual inventory system, and negative working capital dynamics reduce the need for large upfront inventory investments and enable rapid product customization [S1] [S2]. This structure supports higher inventory turns and limits capital at risk, which is especially valuable in a category where style, stone preference, and consumer trends can change quickly.
Gross margin structure in specialty jewelry typically reflects a mix of product mix, sourcing discipline, and pricing power. Brilliant Earth’s premium positioning around ethically sourced and lab-grown diamonds may support higher average selling prices and margins, but it also depends on the company’s ability to maintain perceived value and differentiation as it expands beyond engagement rings into fine jewelry.
Operating leverage is now beginning to show as fixed costs—such as technology investments and showroom leases—are spread over a growing revenue base. The company’s shift from net loss to net income in Q3 2026 and improvement in adjusted EBITDA margin suggest that scale benefits are materializing [N1] [S2]. However, each new showroom adds fixed costs and localized execution risk, so the pace and quality of expansion are central to margin trajectory.
Capital needs are relatively modest by retail standards due to the asset-light approach, but new market entry (both domestic and international) and technology upgrades can still require substantial investment. The degree to which incremental revenue from new showrooms and product categories outpaces these investments will determine whether recent margin gains are sustainable.
Mission-Driven Branding and Technology: Durable Differentiation or Easily Replicated?
Brilliant Earth’s competitive strategy rests on three pillars: ethical sourcing (emphasizing ‘Beyond Conflict Free Diamonds™’ and blockchain traceability), a premium yet accessible brand identity, and an integrated omnichannel approach combining digital tools with personalized showroom service [S1]. This positions the company to attract Millennials and Gen Z consumers who increasingly value transparency and sustainability in luxury purchases.
The jewelry market remains highly fragmented, with legacy brick-and-mortar chains, regional independents, and a growing cohort of digital-first brands all vying for share. While Brilliant Earth’s early adoption of blockchain traceability and augmented reality try-on tools provides a technological edge, these features are not impossible for larger or well-funded rivals to replicate. The question is whether Brilliant Earth’s brand equity and mission-driven positioning provide a lasting moat, or whether these differentiators will erode as competitors catch up.
Showroom expansion can deepen customer engagement but also exposes the company to direct competition with established luxury retailers and local independents. As the company expands internationally, it may encounter differing consumer preferences and regulatory environments, requiring further adaptation.
If Showroom Expansion and Product Diversification Unlock Repeat Purchases
The bullish scenario hinges on Brilliant Earth leveraging its omnichannel model to drive both new customer acquisition and higher lifetime value. If the company’s showrooms continue to lift conversion rates and foster repeat purchases—particularly in fine jewelry categories beyond engagement and wedding rings—then operating leverage could accelerate, with fixed costs spread over a broader revenue base.
Broader international expansion could further amplify growth if the brand’s ethical positioning resonates in new markets. Technology investments (such as augmented reality and blockchain) may also help sustain higher conversion and retention rates if they translate to tangible customer benefits.
Confirmation would come from sustained double-digit revenue growth, rising average order value, and increasing repeat purchase rates (if disclosed), along with further margin expansion as showroom productivity improves. Falsification would be evident if new showroom openings fail to drive incremental sales or if customer acquisition costs spike without a corresponding lift in order volume or value.
Incremental Margin Gains as Core Growth Moderates and Execution Risks Mount
The most plausible path is one of steady but moderate growth, with margin improvement primarily driven by operational efficiencies and selective showroom expansion. Engagement rings and wedding bands likely remain the revenue core, with fine jewelry and international markets contributing incremental growth but not fundamentally altering the company’s trajectory in the near term.
Showroom productivity may vary by location, and the risk of cannibalizing digital sales or overextending fixed costs is real. The company may also face pricing and margin pressure if macroeconomic headwinds persist or if competitive responses erode its premium positioning.
This scenario would be confirmed by mid-single-digit revenue growth, stable to slightly improving EBITDA margins, and disciplined capital allocation toward high-return showroom and technology investments. It would be challenged if net income reverts to losses, margin progress stalls, or if liquidity deteriorates despite ongoing expansion.
Macroeconomic Shock or Execution Missteps Undermine Scale Benefits
A negative scenario could unfold if consumer discretionary spending contracts—due to recession, inflation, or a sharp drop in engagement ring demand—leading to stalled or declining sales. In this environment, fixed costs from an expanded showroom base would weigh heavily on margins, and negative operating leverage could quickly erode profitability.
Execution risk around new showrooms or international launches could result in underperforming locations, inventory write-downs (despite a virtual model, custom orders can still create risk), or brand dilution. Additionally, if competitors successfully replicate Brilliant Earth’s technology and ethical sourcing claims, the company may lose its pricing power and differentiation.
This outcome would be confirmed by declining same-store sales, persistent net losses, or a need to slow or reverse showroom growth to preserve cash. Deteriorating liquidity or negative working capital trends would further signal strain.
Milestones That Will Determine Whether Brilliant Earth’s Model Can Scale
Showroom productivity: Revenue and contribution margin per showroom, especially for recently opened locations, would help test the scalability of the omnichannel strategy (if disclosed).
Repeat purchase rates: Growth in non-bridal and fine jewelry repeat transactions would indicate success in broadening customer relationships (if disclosed).
Gross margin trends: Sustained or improving gross margins would suggest pricing power and cost discipline as the product mix broadens.
SG&A leverage: The ratio of selling, general, and administrative expenses to revenue will show whether fixed costs are being absorbed efficiently as showrooms scale.
Average order value: Increases would support the case for successful premium positioning and upselling.
Competitor response: Evidence of traditional or digital competitors matching Brilliant Earth’s technology or ethical sourcing claims could erode the differentiation thesis.
International traction: Early results from new international markets would help validate or challenge the global scalability of the brand.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments