
Burford Capital in 2026: Legal Finance Scale, Valuation Frictions, and the Realities of Illiquid Asset Investing
Burford Capital remains the largest dedicated legal finance provider, leveraging balance sheet capital and third-party funds to back high-stakes legal claims. With a $7.5 billion portfolio and a client roster spanning nearly all major global law firms, Burford’s model capitalizes on a vast and growing market for litigation finance. Yet the company’s reliance on fair-value accounting for inherently illiquid and uncertain assets introduces persistent risks to earnings quality and reported returns.
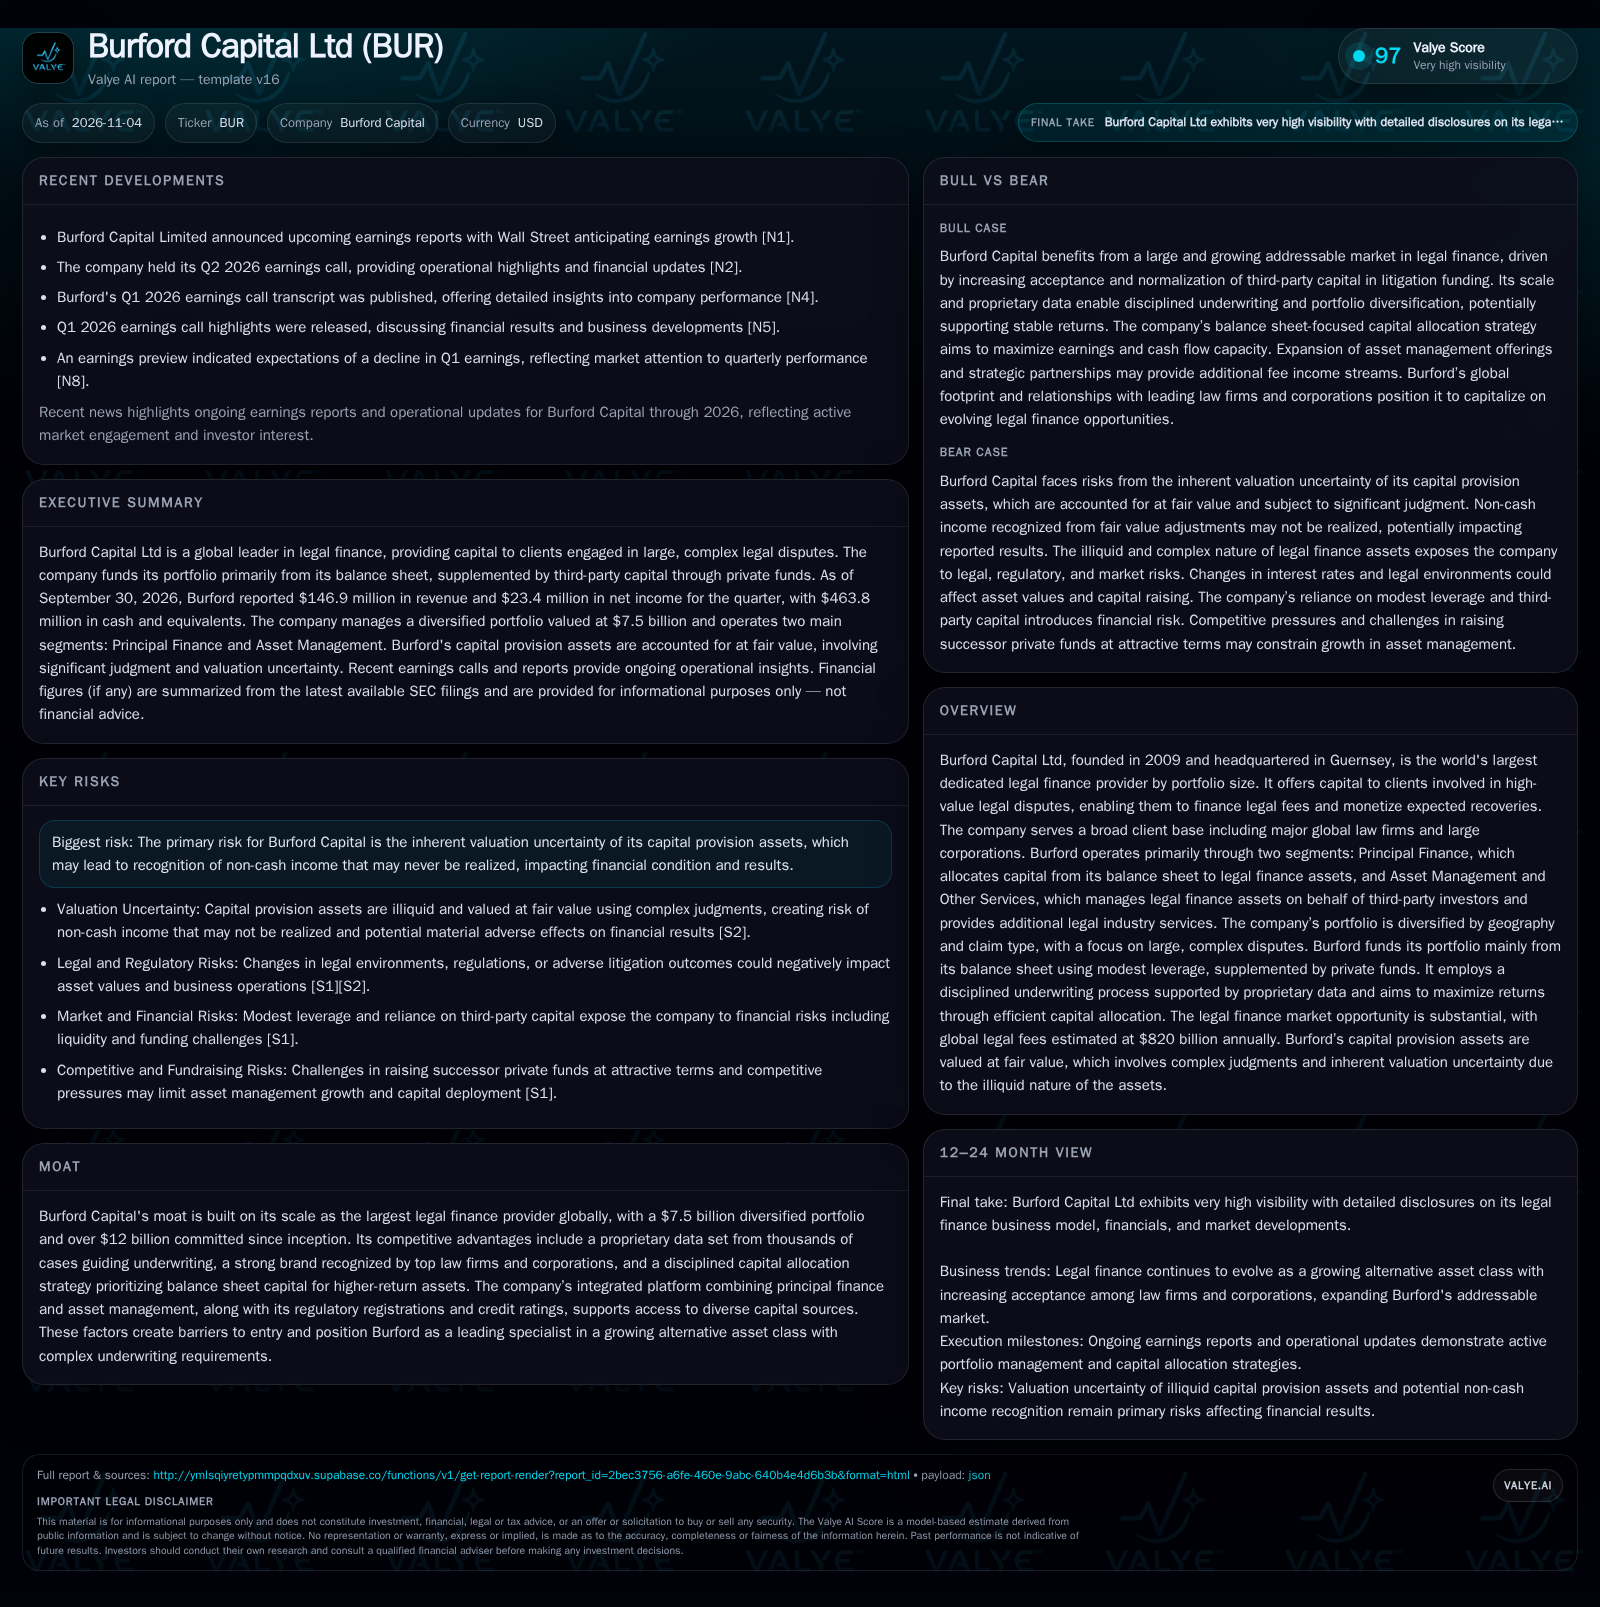
Burford Capital reported $146.9M in Q3 2026 revenue and manages a $7.5B diversified portfolio in legal finance, supported by $463.8M in cash and $377.1M in short-term investments. Its model deploys balance sheet and third-party capital to fund large legal disputes, emphasizing underwriting discipline and proprietary data. The company’s growth opportunity is substantial, but valuation uncertainty and the illiquidity of its assets remain central risks to realized returns and earnings reliability. [S1] [S2]
Burford Capital stands at the intersection of finance and law, providing capital to back large, complex legal disputes worldwide. As the world’s largest dedicated legal finance provider, its $7.5 billion portfolio and global reach reflect both the scale of the opportunity and the intricacies of deploying capital into an asset class where outcomes are uncertain, cash flows are lumpy, and asset values are inherently opaque. The company’s business model—leveraging balance sheet and third-party funds, disciplined underwriting, and proprietary data—positions it to capture a slice of the $820 billion global legal fee pool. Yet, the reliance on fair-value accounting for illiquid, hard-to-value assets exposes Burford to persistent risks around earnings quality, capital allocation, and the translation of paper gains into realized cash.
Burford’s Position: Scale, Liquidity, and Portfolio Mix at the Close of 2026
As of September 30, 2026, Burford Capital managed a $7.5 billion legal finance portfolio diversified by geography and claim type, with $3.2 billion in assets under management across private and sidecar funds. The company reported $146.9 million in revenue and $23.4 million in net income for the quarter, holding $463.8 million in cash and equivalents and $377.1 million in short-term investments. Its client base includes 95 of the 100 largest US law firms and 93 of the 100 largest global law firms by revenue, underscoring entrenched relationships in the upper tiers of the legal industry. [S1] [S2]
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. The company’s legal finance assets are marked to fair value, a process requiring significant judgment given the illiquidity and binary nature of litigation outcomes. [S1] [S2]
Revenue Generation: Fee Models, Principal Stakes, and Legal Outcome Leverage
Burford’s core economic engine blends two models: principal investing in legal claims using its balance sheet, and asset management for third-party capital. The former exposes Burford directly to the upside and downside of litigation outcomes—returns are realized when cases settle or judgments are paid, but timelines are highly variable and outcomes are binary. Asset management, by contrast, generates fees and performance-based incentives, offering a more stable (though lower margin) income stream.
Revenue recognition is complicated by the use of fair-value accounting for legal finance assets. Gains may be recognized before cash is received, leading to non-cash income that may never be realized if cases are lost or settlements are lower than anticipated. This dynamic creates a disconnect between reported results and operating cash flow, and can lead to volatility in earnings, especially as portfolio size and complexity grow. [S2]
Operating leverage is plausible as the business scales, given the fixed cost base relative to the incremental cost of underwriting and managing additional claims. [S1]
Competitive Advantages: Scale, Data Assets, and Brand Strength Against New Entrants
Burford’s position as the largest dedicated legal finance provider confers tangible advantages. Its proprietary data set, derived from thousands of funded cases, enables more informed underwriting and pricing than smaller or less experienced competitors. Deep relationships with nearly all major law firms and large corporations further reinforce its brand and deal flow. [S1]
Nevertheless, the legal finance industry is attracting new entrants—specialty funds, hedge funds, and insurance-linked investors—drawn by the promise of uncorrelated returns. While Burford’s integrated platform and regulatory credentials create barriers to entry, there is little structural protection against capital inflows that could compress returns, especially in commoditized or less complex funding opportunities. Substitution risk also exists: law firms may increasingly self-fund, or alternative forms of litigation insurance could evolve, reducing reliance on third-party capital for some cases.
A key differentiator remains Burford’s ability to underwrite larger, more complex, and bespoke transactions—areas where scale, reputation, and experience matter most, and where new entrants face the steepest learning curve.
Indicators of Success: Portfolio Payouts, Velocity, and Expanding Asset Management Fees
If Burford’s disciplined underwriting produces a string of successful case resolutions—particularly in large, high-profile matters—the company could see a step-change in realized cash returns and operating leverage. The compounding effect of positive outcomes would free up balance sheet capital for redeployment, accelerate fee income from asset management, and reinforce Burford’s reputation as the counterparty of choice for complex claims.
Confirmation would come from a sustained increase in realized cash receipts (rather than just fair-value gains), higher asset management fee income as fund performance improves, and growth in new commitments from both balance sheet and third-party capital. Additional evidence would include Burford attracting larger institutional allocations to its private funds, and a visible reduction in the proportion of non-cash income to reported earnings.
Falsification would be indicated by continued divergence between fair-value gains and realized cash flows, or by stalled growth in new fund commitments amid competitive or performance headwinds.
Expected Industry Path: Execution Amid Variability and Market Opacity
The most plausible outlook is for Burford to continue generating lumpy but positive returns from its diversified portfolio, balancing periods of strong case wins with inevitable losses and slow resolutions. Asset management income should remain a growing, stabilizing force, but principal investing will continue to drive the bulk of earnings volatility.
Realized cash receipts are likely to lag reported fair-value gains due to the long timelines and binary nature of litigation outcomes. Over time, portfolio diversification and data-driven underwriting may reduce volatility, but cannot eliminate it.
Evidence supporting this trajectory would include continued growth in assets under management, stable or improving operating margins, and a relatively steady mix of cash and non-cash income. Divergence from this path could emerge if the competitive environment intensifies, regulatory changes disrupt funding models, or asset valuations come under sustained pressure.
Risks from Valuation Challenges: Impact of Non-Cash Gains, Litigation Outcomes, and Funding Constraints
The core risk for Burford is that fair-value marks overstate the realizable value of its portfolio, with a series of adverse case outcomes or slow recoveries leading to write-downs and cash flow shortfalls. Non-cash income recognized in prior periods may never be realized, eroding investor confidence and constraining the company’s ability to raise new capital—either on balance sheet or in private funds.
Further downside could arise if legal or regulatory changes make it harder to enforce judgments, collect awards, or structure funding arrangements, or if capital markets turn risk-averse and reduce demand for illiquid alternative assets. A deterioration in realized returns versus reported gains, persistent negative case outcomes, or difficulty raising successor funds would confirm this scenario.
Mitigating factors include Burford’s portfolio diversification and experience, but the fundamental sensitivity to legal outcomes and asset illiquidity is not easily hedged.
Events That Could Transform Burford’s Legal Finance Prospects
The ratio of realized cash receipts to reported fair-value gains—if disclosed—would clarify the quality and timing of earnings.
Trends in new commitments and deployments, both on balance sheet and in private funds, would reveal whether Burford is maintaining its capital deployment pace amid competitive and market changes.
Data on the success rate and size of resolved cases, especially large, high-profile matters, would provide insight into underwriting effectiveness and portfolio risk.
Changes in assets under management and the ability to raise successor funds at attractive terms would test the strength of the asset management franchise.
Disclosure of adverse case outcomes or significant write-downs would help calibrate downside risk and the reliability of fair-value marks.
Any regulatory or legal environment shifts affecting enforceability, funding structures, or capital flows into the sector would be highly material.
Fee income trends and operating margin evolution—if broken out—would indicate progress in diversifying income streams and scaling the platform.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments