
Neuronetics in Late 2026: TMS Therapy Economics, Operational Inflection, and the Stakes of Clinical Adoption
Neuronetics, Inc. is showing signs of operational momentum in transcranial magnetic stimulation (TMS) therapy, with improving revenue and positive adjusted EBITDA in 2026. The company’s challenge is to translate recent financial and management progress into sustained profitability, while navigating a complex clinical, regulatory, and reimbursement landscape.
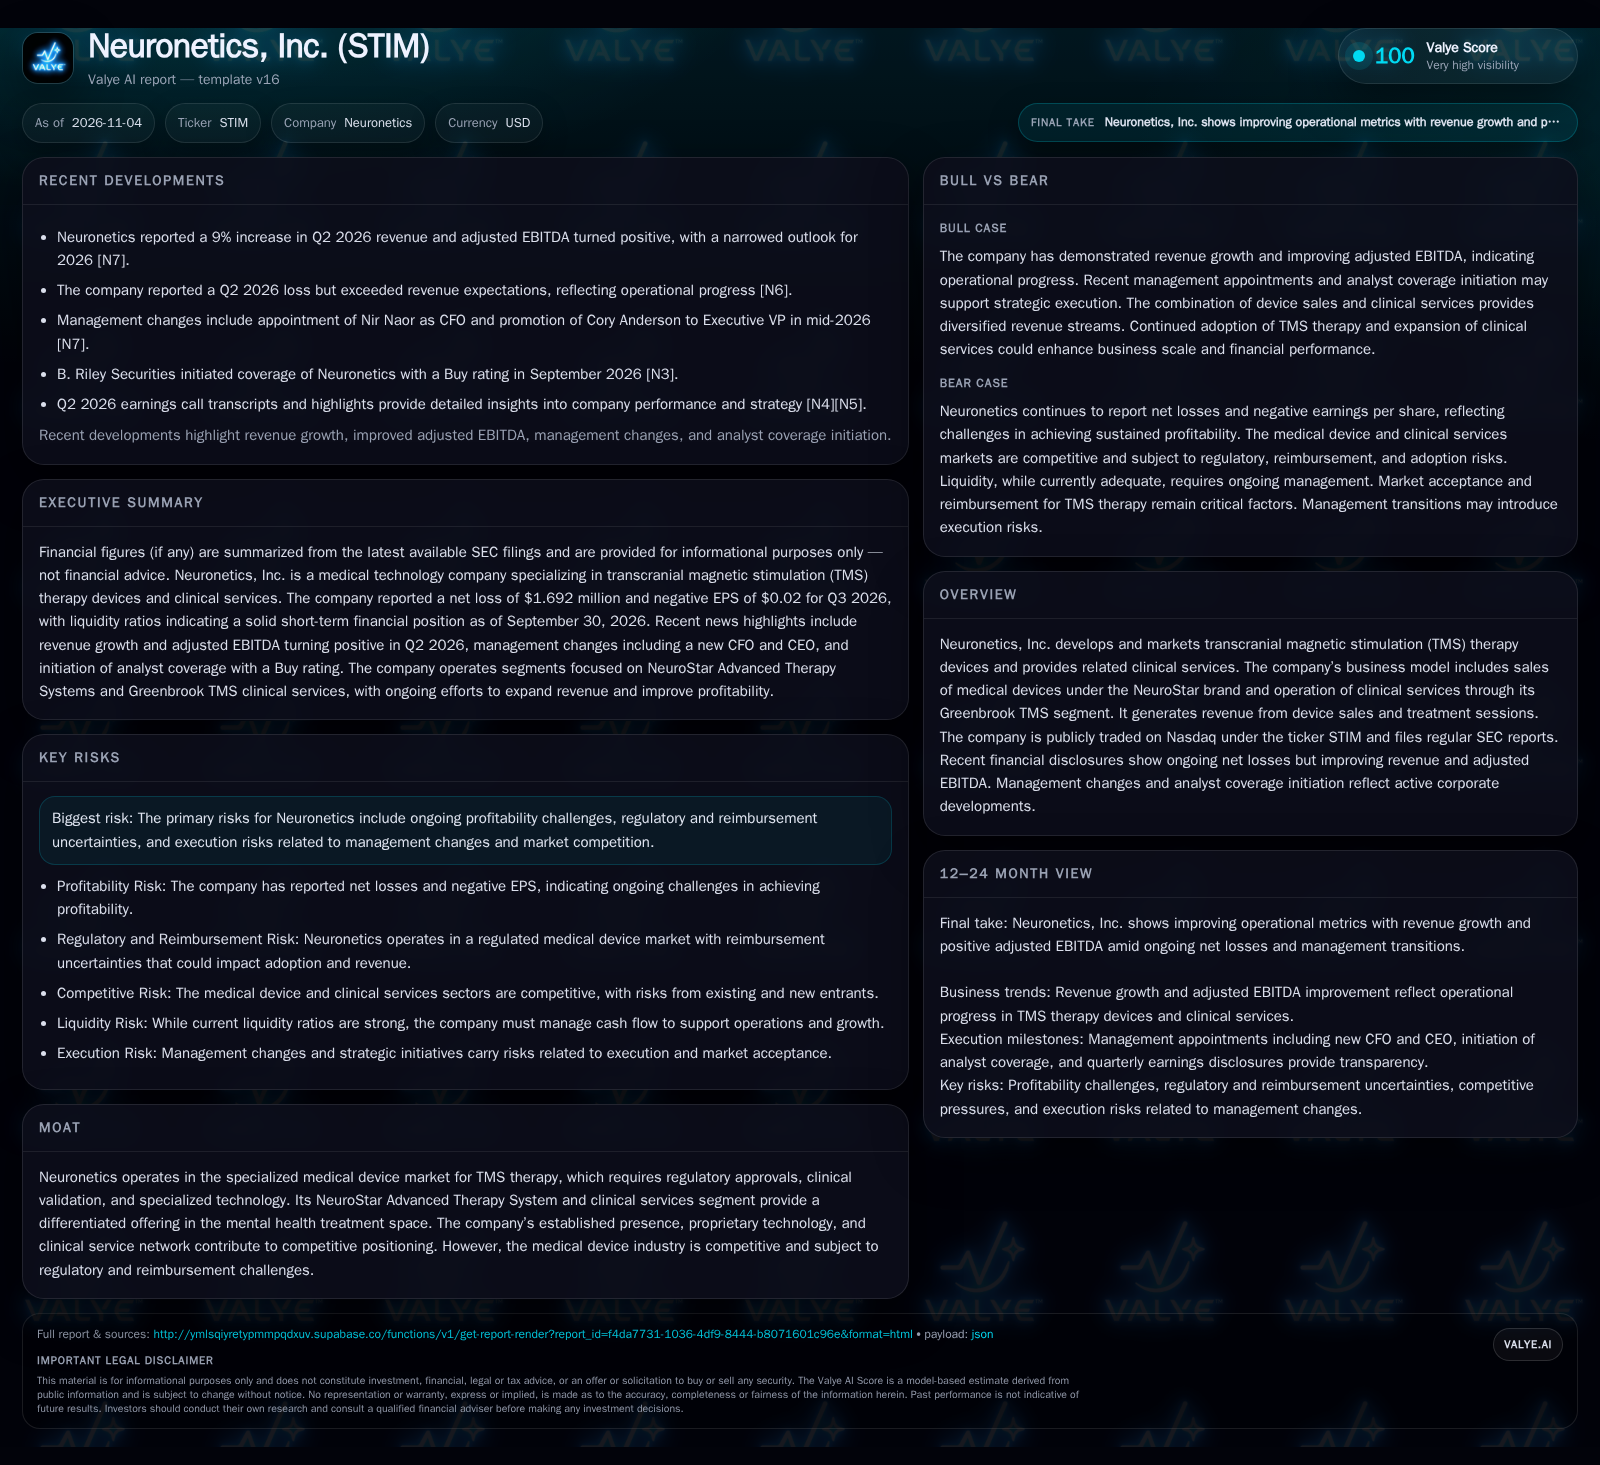
Neuronetics has reported a 9% year-over-year revenue increase and turned adjusted EBITDA positive in Q2 2026, amid ongoing net losses and significant management changes. The company’s TMS therapy platform and clinical services are gaining operational traction, but the path to durable profitability depends on continued adoption, effective cost control, and resilience to reimbursement and competitive pressures. [N7] [S2]
Neuronetics, Inc., a specialist in transcranial magnetic stimulation (TMS) therapy devices and clinical services, enters late 2026 with tangible operational progress but unresolved profitability. A 9% year-over-year revenue increase and a shift to positive adjusted EBITDA in Q2 mark a potential inflection point, suggesting that the company’s commercial model is beginning to scale. However, persistent net losses, ongoing investment needs, and a competitive, reimbursement-sensitive market mean that the company’s ability to sustain and broaden these gains remains in question. The next phase will test whether Neuronetics can convert operational improvements into enduring financial strength, as it navigates evolving clinical, regulatory, and market dynamics. [N7] [S2]
Recent Financial and Strategic Developments Define 2026 Operating Landscape
Neuronetics reported a 9% increase in Q2 2026 revenue, with adjusted EBITDA turning positive—an important operational milestone after a history of net losses. This suggests improving cost discipline or better operating leverage as revenue scales, though the company continues to report a net loss of $1.692 million and EPS of -$0.02 for Q3 2026. As of September 30, 2026, the company’s reported liquidity position, with a current ratio of 2.01 and a cash ratio of 0.82. Notably, management turnover has been significant: the appointment of Nir Naor as CFO and the promotion of Cory Anderson to Executive VP, alongside a new CEO earlier in the year, signal a strategic reset that could impact execution. [N7] [S2]
How TMS Therapy and Clinical Services Could Drive Operating Leverage
Neuronetics generates revenue through two primary channels: sales of its NeuroStar Advanced Therapy TMS devices and clinical treatment sessions provided through its Greenbrook TMS segment. Device sales are likely characterized by relatively lumpy, high-ticket transactions with healthcare providers, while treatment sessions provide a recurring, services-based revenue stream. The mix between these channels influences gross margin and revenue visibility: device sales may offer higher upfront gross margins but less predictability, whereas services could drive steadier, lower-margin recurring revenue.
The company’s ability to scale depends on adoption rates of TMS therapy among clinicians and patients, reimbursement dynamics, and competitive differentiation. Fixed costs—such as R&D, regulatory compliance, and salesforce—are material, suggesting that incremental revenue growth could drive meaningful operating leverage if top-line expansion continues. However, persistent net losses indicate that current scale is insufficient to fully absorb these fixed costs. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity.
The interplay between device sales and clinical services also introduces nuanced considerations for capital allocation and working capital management. For instance, device sales often require upfront manufacturing investment and inventory holding, which can strain cash flow if sales cycles lengthen or if customer payment terms are extended. Conversely, clinical services generate revenue more gradually but may demand ongoing operating expenses related to staffing, facility maintenance, and patient acquisition. Balancing these dynamics is critical; if the company overly prioritizes device sales growth without ensuring clinical service scalability, it may face mismatches in cash conversion cycles that impair liquidity. A useful metric would be the cash conversion cycle segmented by business line to reveal potential stress points or efficiencies.
Moreover, the reimbursement environment's influence extends beyond revenue volume to affect pricing strategy and customer acquisition economics. If reimbursement rates are compressed or reimbursement policies become more restrictive, the company may need to adjust device pricing or offer bundled service contracts to maintain competitive positioning. This could compress gross margins and necessitate tighter cost controls or operational efficiencies to preserve profitability. Additionally, the company’s salesforce effectiveness in educating clinicians and payers on TMS benefits directly impacts adoption curves and revenue growth. Therefore, investment in targeted sales and marketing initiatives must be calibrated carefully against expected reimbursement trends and competitive pressures to optimize return on investment.
Specialized Device Market Requires Differentiation and Clinical Validation
Neuronetics operates in a specialized segment of the medical device market focused on non-invasive neuromodulation for mental health, particularly major depressive disorder. The competitive landscape includes both other TMS device manufacturers and broader neurostimulation or psychiatric treatment alternatives, such as electroconvulsive therapy, pharmacotherapy, and emerging digital therapeutics.
The company’s competitive position depends on several factors: the clinical efficacy and safety profile of its NeuroStar system, depth of clinical validation, physician and patient adoption, and the breadth of its clinical services network. Regulatory approvals and reimbursement coverage are crucial moats but are not insurmountable barriers, as other device makers can also navigate these hurdles. Pricing power is limited by payer policies and the capital intensity of device adoption by clinics. The company’s dual model—combining device sales with direct clinical services—could provide a partial buffer against competitive encroachment, but also exposes it to operational complexity and potential channel conflict.
If Clinical Adoption Accelerates and Reimbursement Expands, Profitability Could Follow
A favorable outcome for Neuronetics would see continued acceleration in TMS therapy adoption, both through expanding indications and increased clinical acceptance. If payers broaden reimbursement or raise payment rates, this could improve both device sales and per-treatment economics. Sustained revenue growth would allow the company to further leverage its fixed cost base, driving operating margins toward profitability.
Confirmation would come from several quarters of double-digit revenue growth, further improvement in adjusted EBITDA and—critically—a move to GAAP profitability. Evidence of expanded payer coverage, strong device placement rates, and growing treatment volumes would further validate the thesis. Conversely, a stall in adoption, static or declining reimbursement rates, or operational slippage in the clinical services segment would challenge the upside case.
In scenarios where clinical adoption accelerates, network effects could further enhance Neuronetics’ competitive position. As more clinicians and patients utilize the NeuroStar system, data accumulation may enable improved treatment protocols and personalized approaches, potentially enhancing clinical outcomes and patient satisfaction. This could reinforce payer confidence and justify higher reimbursement rates or expanded coverage. Additionally, a larger installed base could increase switching costs for providers and patients, strengthening customer retention and reducing churn. If the company leverages these dynamics effectively, it may also unlock opportunities for ancillary revenue streams, such as software upgrades, maintenance contracts, or training services, which would contribute to margin expansion and revenue diversification.
Furthermore, broader reimbursement expansion could catalyze institutional adoption beyond traditional outpatient clinics, including hospitals and integrated health systems. Such expansion would increase patient access and treatment volumes, while potentially enabling more favorable contract terms due to higher volume commitments. However, this would also require the company to navigate complex procurement processes and tailor its sales approach to institutional buyers, which may introduce longer sales cycles but larger deal sizes. Success in this context depends on operational agility and the ability to demonstrate clinical and economic value at scale, reinforcing the importance of robust real-world evidence and health economic outcomes data to support payer and provider decision-making.
Incremental Revenue Gains and Tight Cost Controls Sustain Gradual Progress
The most plausible near-term scenario is continued modest revenue growth as TMS adoption expands at a measured pace and Neuronetics executes on cost containment. Adjusted EBITDA may remain positive or improve, but net income could stay negative as the company invests in sales force expansion, clinical evidence generation, and technology upgrades.
This scenario would be supported by steady device placements, stable or slowly improving payer coverage, and incremental improvements in clinical service utilization. Confirmation would come from consecutive quarters of positive adjusted EBITDA, modestly narrowing net losses, and no material deterioration in cash or liquidity. Falsifying evidence would include a return to negative adjusted EBITDA, material revenue contraction, or adverse regulatory/reimbursement developments.
Reimbursement Pressure or Clinical Adoption Stalls Could Undercut Operating Momentum
The primary risks for Neuronetics stem from reimbursement setbacks or a plateau in clinical adoption. If payers restrict coverage, lower payment rates, or impose new utilization management barriers, both device sales and treatment revenues could stagnate or decline. Competitive pressure from new entrants, superior clinical alternatives, or disruptive technologies could also erode the company’s market share.
A downside scenario would be marked by sequential revenue declines, a reversion to negative adjusted EBITDA, and increased cash burn. Management turnover or operational missteps could also undermine execution. Evidence would include missed revenue targets, negative earnings surprises, or regulatory headwinds affecting market access.
Milestones That Will Test Neuronetics’ TMS Growth Thesis in 2027
Sequential and year-over-year revenue growth rates by segment—especially device sales versus clinical services—if disclosed.
Adjusted EBITDA and net income trends on a quarterly basis, to confirm or challenge the operating leverage thesis.
Device placement rates and utilization metrics for NeuroStar systems, as these indicate demand and installed base expansion.
Updates on payer reimbursement policy changes and coverage expansion for TMS therapy.
Clinical trial results or published real-world evidence supporting expanded indications or superior outcomes versus competitors.
Retention and productivity metrics in the Greenbrook TMS clinical services segment, if disclosed.
Management commentary on competitive dynamics, regulatory developments, and strategic priorities in earnings calls or investor presentations.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments