
Perspective Therapeutics: Alpha-Emitter Innovation, Clinical Milestones, and the Road to Radiopharma Commercialization
Perspective Therapeutics advances targeted alpha therapies for cancer using proprietary Lead-212 isotope technology, with multiple clinical programs progressing and recent regulatory recognition.
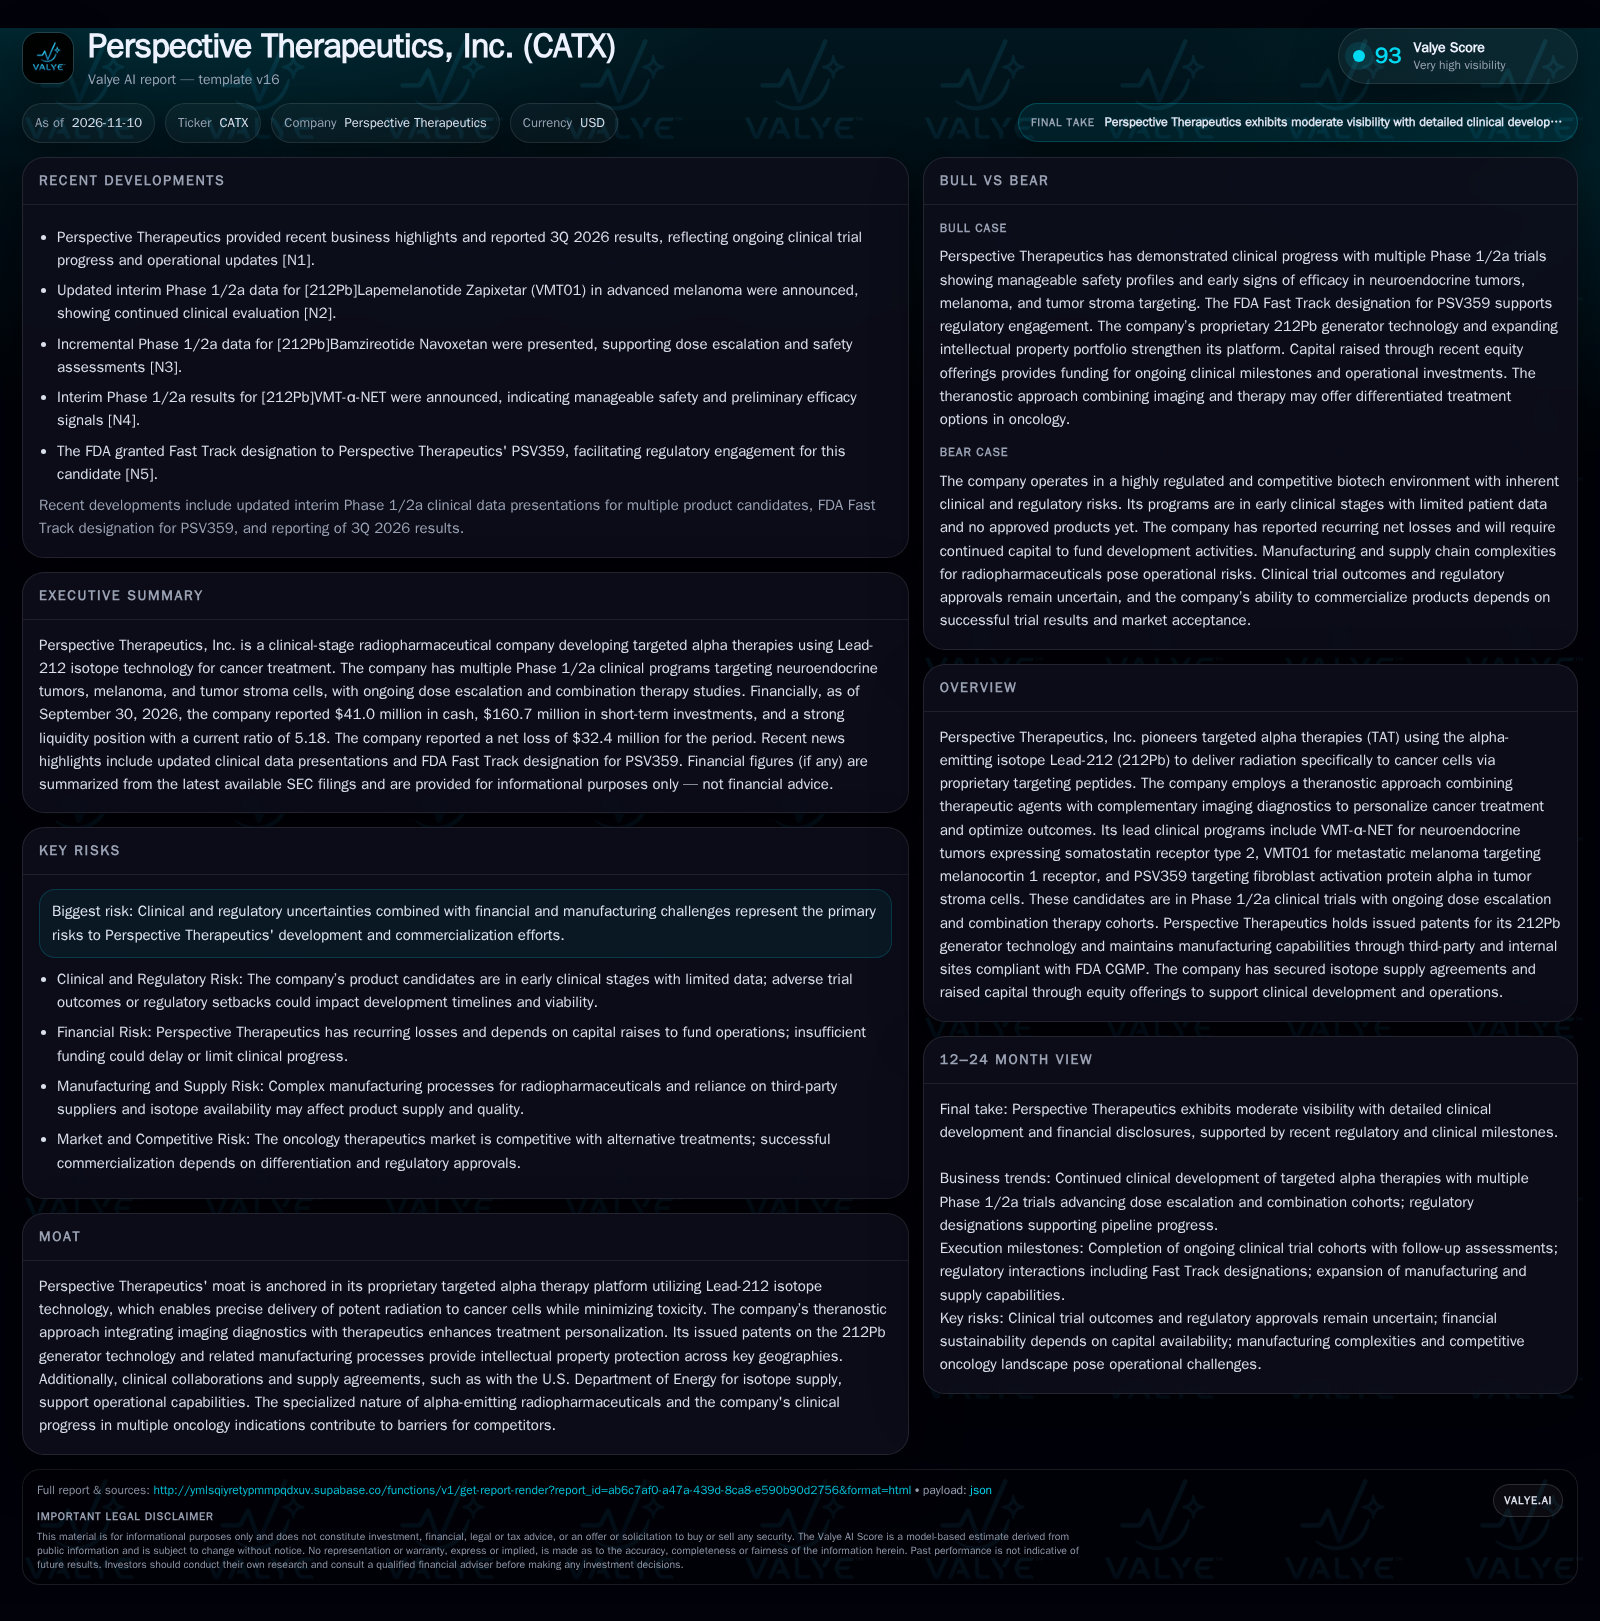
Perspective Therapeutics is a clinical-stage radiopharmaceutical company leveraging proprietary Lead-212 technology for targeted cancer therapies. With three programs in Phase 1/2a trials, recent FDA Fast Track designation for PSV359, and substantial liquidity following a $175 million capital raise, the company is positioned to pursue key clinical milestones through late 2027. However, no products are approved, and material risks include clinical, regulatory, and operational hurdles typical of the sector. The next 12–24 months will be pivotal in validating clinical efficacy, managing cash burn, and demonstrating the scalability of its theranostic platform.[S1] [S2] [N5]
Perspective Therapeutics stands at the intersection of radiopharmaceutical innovation and clinical execution, leveraging its proprietary Lead-212 alpha-emitting technology to develop targeted therapies for difficult-to-treat cancers. With three distinct programs in early clinical trials and the recent FDA Fast Track designation for its fibroblast activation protein (FAP-α) program, the company has achieved notable scientific and regulatory milestones. Its fortified liquidity, following a significant capital raise, provides a window to reach pivotal clinical readouts. However, as with all pre-commercial biotech ventures, the translation of promising early data into regulatory approval and sustainable commercial operations remains a high-stakes challenge.
Recent Clinical Progress and Financial Position Define the Near-Term Outlook
The company reported a current ratio of 5.18 for the period. [S1] [S2] [N2] [N3] [N4] [N5]
These developments matter because they provide Perspective with both the financial runway and regulatory momentum to pursue multiple clinical milestones over the next 12–24 months. Yet, with no approved products and ongoing net losses, the company’s ability to convert clinical promise into long-term value hinges on both trial outcomes and future funding or partnership opportunities.
How the Theranostic Model Could Reshape Oncology Economics
Perspective’s business model is rooted in the development of radiopharmaceuticals that combine a therapeutic payload (Lead-212) with tumor-specific targeting peptides and complementary imaging diagnostics—a theranostic approach. If successful, this could enable highly personalized cancer treatment, potentially commanding premium pricing in oncology. The economics of such therapies typically involve high per-dose reimbursement, reflecting both the complexity of manufacturing alpha emitters and the clinical value of precision targeting.
Fixed costs are substantial in early stages, driven by R&D, clinical trials, and the need to establish compliant manufacturing infrastructure for both the isotope and finished drug product. Variable costs include raw isotope procurement, consumables, and distribution, which can be high given the short half-life and logistical challenges of radiopharmaceuticals. The company’s proprietary generator technology and supply agreement with the U.S. Department of Energy may help mitigate input cost volatility and supply risk, supporting margin stability if scaled.
Operating leverage could be meaningful if Perspective achieves commercial approval, as fixed development and regulatory costs are amortized over growing sales. However, capital needs will remain high until at least one product transitions to revenue generation. The sustainability of the model will depend on payer acceptance, competitive pricing dynamics, and the ability to scale manufacturing without quality or supply disruptions.
Intellectual Property, Platform Differentiation, and the Competitive Radiopharma Landscape
Perspective Therapeutics’ competitive position is underpinned by its issued patents for Lead-212 generator technology, which may limit direct competition in alpha-emitting isotope supply and support the development of a proprietary product portfolio.[S1] The company’s theranostic model, integrating imaging and therapy, aligns with oncology trends favoring precision medicine—potentially enhancing differentiation versus conventional radiotherapy or beta-emitting radiopharmaceuticals.
However, the radiopharma sector is increasingly crowded, with established players and well-funded biotech peers also pursuing targeted alpha therapies and theranostic solutions. Alternatives such as Lutetium-177 and Actinium-225 based agents, along with antibody-drug conjugates and cell therapies, represent both direct and indirect competition. Switching costs for oncologists may be moderate if Perspective’s products demonstrate superior efficacy or safety, but payer and provider adoption will hinge on robust head-to-head clinical data and real-world outcomes.
Barriers to entry remain high due to regulatory complexity, isotope supply constraints, and the need for specialized manufacturing and distribution. Perspective’s supply agreement with the Department of Energy and its internal/external manufacturing network add resilience but do not guarantee insulation from future supply or competitive shocks.
What Success Would Look Like: Clinical Validation Unlocks Platform Value
A favorable scenario for Perspective would see continued positive safety and efficacy data in ongoing Phase 1/2a trials for all lead programs, particularly with PSV359 leveraging its FDA Fast Track status to advance rapidly through clinical and regulatory milestones. If the company can demonstrate statistically significant tumor response rates and durable disease control, it could attract strategic partnerships or licensing deals—potentially providing non-dilutive funding and commercial infrastructure.
Confirmation of this scenario would require: (1) peer-reviewed publication of robust efficacy data; (2) regulatory progression to pivotal Phase 2/3 trials; (3) evidence of scalable, compliant manufacturing of both isotope and finished drug; and (4) early signals of payer and provider interest in the theranostic model. Signs of partnership activity or milestone-based payments would further validate the commercial potential.
Navigating Clinical Development: Progress, Cash Burn, and Uncertainty
The most plausible near-term path is a continuation of current clinical progress, with ongoing dose escalation and expansion cohorts in core programs and incremental data releases supporting safety and preliminary efficacy.
In this scenario, Perspective may initiate later-stage trials for one or more candidates but will likely need to seek additional capital or strategic partnerships before reaching commercialization. The base case does not assume major clinical setbacks, but also does not presume breakthrough efficacy or immediate market adoption. Evidence confirming this scenario would include steady enrollment and dose escalation, regular data updates, and announcements of additional funding or partnership activity. A negative inflection would be triggered by unexpected safety signals or slower-than-expected trial enrollment.
Setbacks in Clinical Trials or Supply Could Derail the Opportunity
The primary downside risk is a material adverse outcome in clinical trials—such as dose-limiting toxicities, lack of efficacy, or patient discontinuations—that leads to halted programs or regulatory delays. Given the early-stage nature of all programs, a single major safety or efficacy failure could have outsized impact on investor confidence and capital access.
Additional risk factors include manufacturing or supply chain disruptions, particularly with the specialized isotopes required, or broader sectoral headwinds (such as reimbursement challenges or competing therapies demonstrating superior efficacy). Evidence of this scenario would include FDA clinical holds, negative interim data, patient deaths attributed to treatment, or public disclosure of manufacturing/supply failures. In these outcomes, Perspective could face reduced liquidity, urgent capital needs, or a potential pivot to out-licensing or asset sales.
Testing the Perspective Therapeutics Thesis: Clinical, Operational, and Commercial Milestones to Track
Progression of VMT-α-NET, VMT01, and PSV359 through later-stage clinical trials, with particular attention to dose-limiting toxicities, overall response rates, and durability of disease control, if disclosed.
Frequency and quality of interim clinical data updates, including peer-reviewed publications or conference presentations.
Advancement of PSV359 under FDA Fast Track, including regulatory interactions, potential breakthrough designation, or movement to pivotal trials.
Burn rate and cash runway relative to clinical progress, including updates on capital raises, partnership deals, or non-dilutive funding.
Evidence of manufacturing scalability and supply chain robustness—such as expanded isotope supply agreements, internal site readiness, or third-party manufacturing audits.
Intellectual property developments, including patent issuances, challenges, or new filings related to the Lead-212 generator platform.
Market signals of payer, provider, or partner interest in theranostic oncology approaches—such as advisory board formation, KOL engagement, or pilot reimbursement agreements.
Competitive landscape developments, particularly clinical readouts or approvals from other targeted alpha therapy or theranostic companies.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments