
Cullinan Therapeutics: Pipeline Catalysts and the Capital Stakes of T Cell Engager Innovation
As regulatory and capital demands rise, the company faces the clinical, commercial, and compliance hurdles typical of late-stage biotech transition.
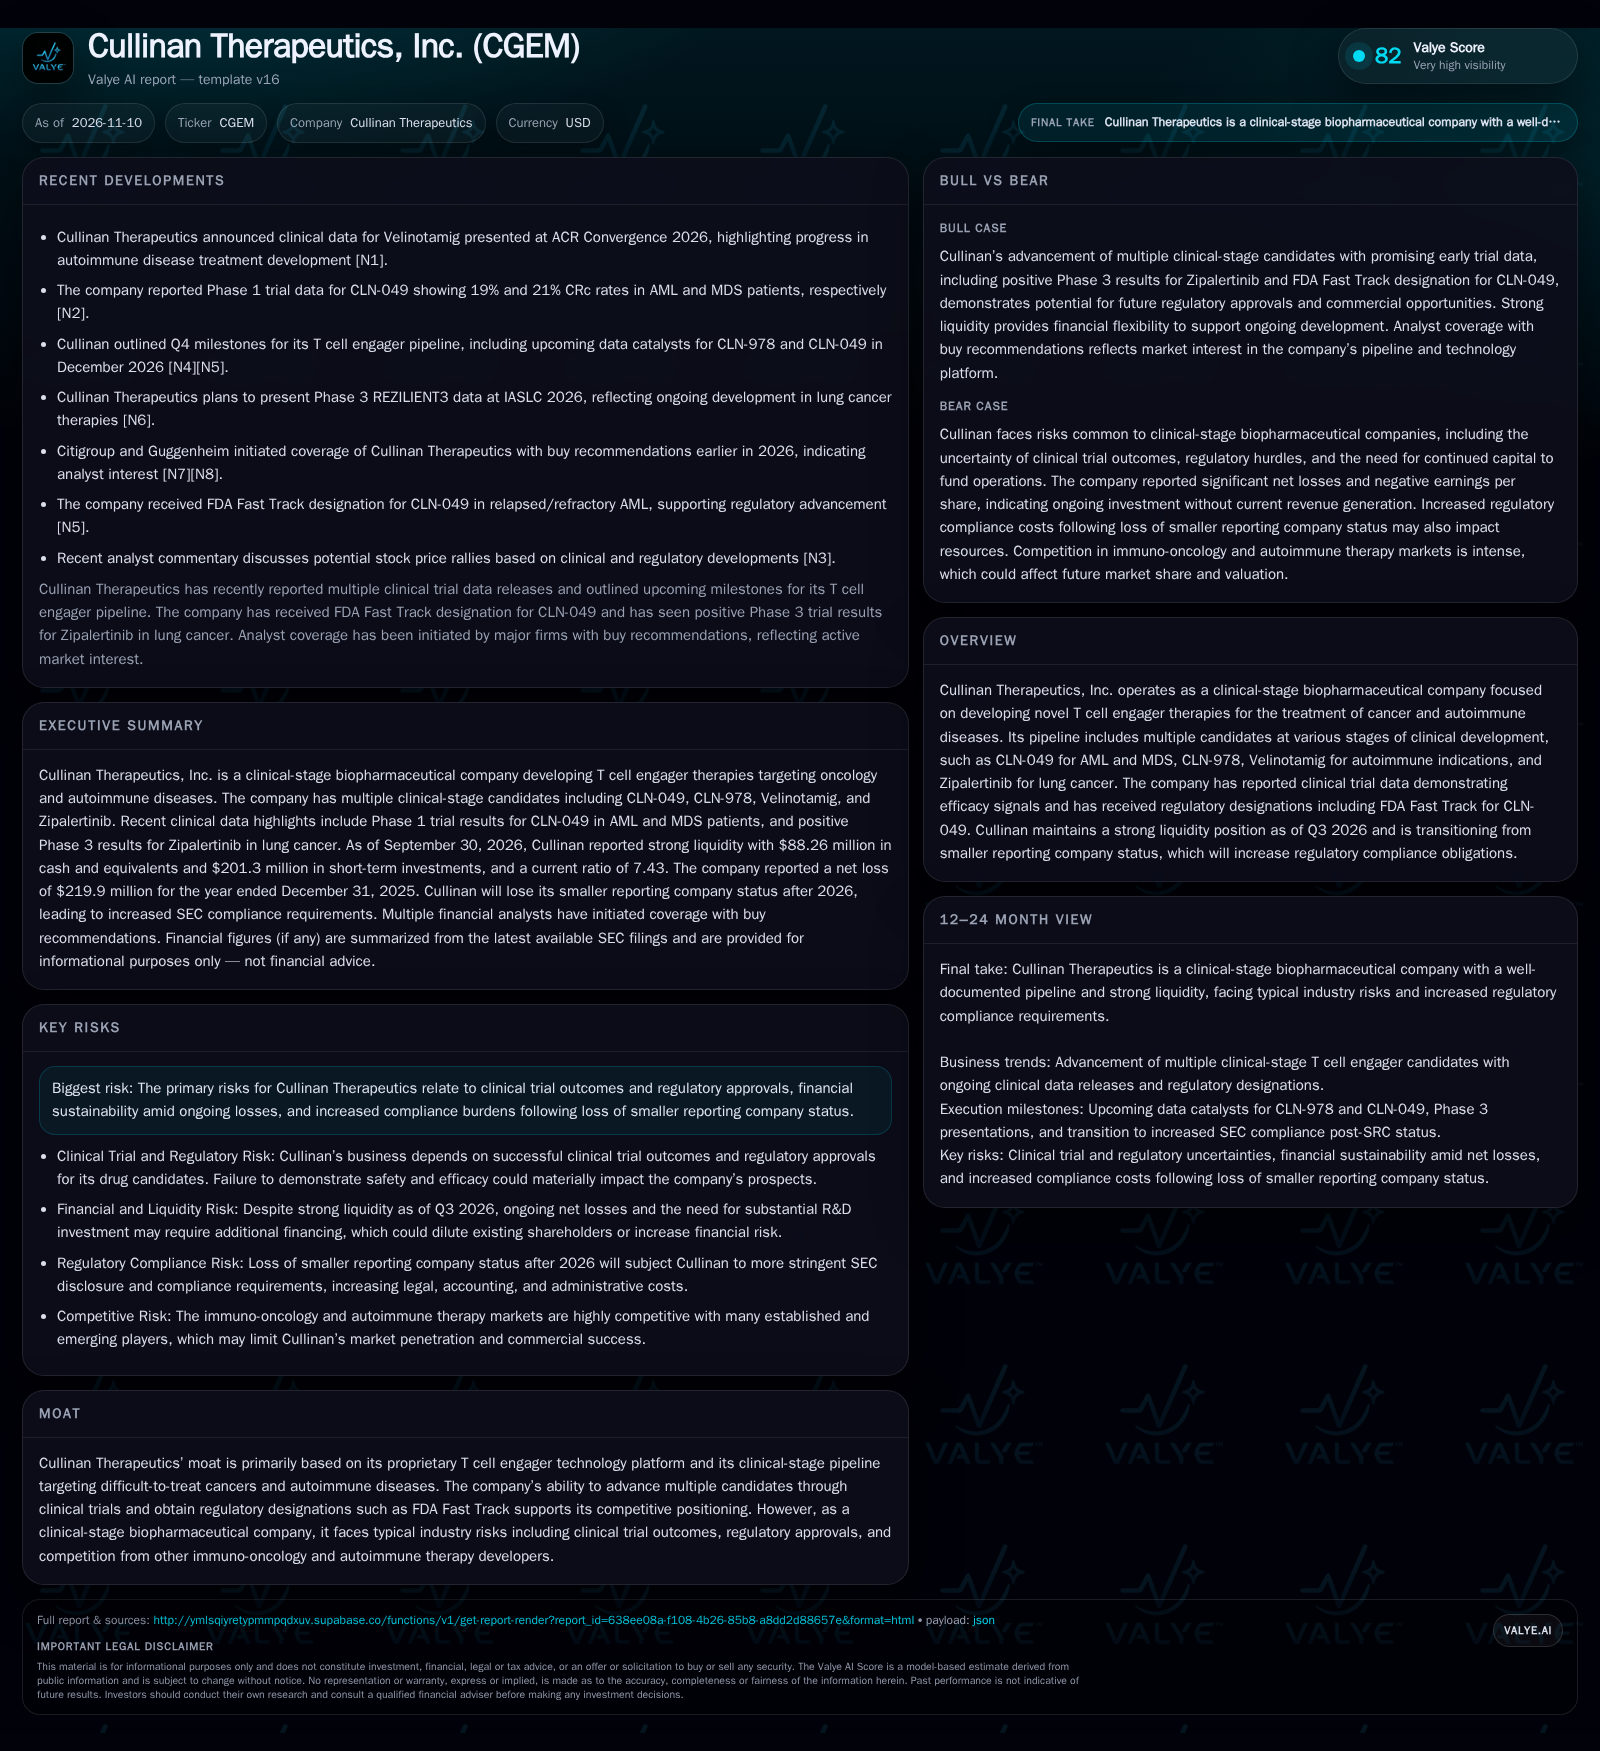
Cullinan Therapeutics holds a reported liquidity position and a diversified pipeline of T cell engager therapies in oncology and autoimmune diseases. With positive early and pivotal clinical data and upcoming catalysts in Q4 2026, the company is positioned for potential value inflection. However, persistent net losses, looming increased SEC compliance, and a highly competitive landscape underscore the need for successful execution and prudent capital management. [S2] [N1] [N2] [N4] [N5]
Cullinan Therapeutics, Inc. stands at a pivotal moment as a clinical-stage biopharma innovator focused on T cell engager therapies for cancer and autoimmune diseases. The company’s transition out of smaller reporting company status will also amplify its compliance obligations, raising the stakes for operational and financial discipline. Success now depends on both clinical execution and strategic capital deployment as competition intensifies across immune-oncology and autoimmune markets.
Recent Clinical Data and Financial Position Shape Immediate Risk-Reward
Cullinan Therapeutics reported $88.26 million in cash and equivalents and $201.3 million in short-term investments as of September 30, 2026, resulting in a reported current ratio of 7.43 and cash ratio of 7.22. This liquidity base is critical as the company navigates upcoming data catalysts and regulatory milestones. [S2]
The company recently disclosed Phase 1 trial data for CLN-049, showing 19% and 21% complete remission with incomplete hematologic recovery (CRc) rates in AML and MDS patients, respectively, and presented Velinotamig clinical data at ACR Convergence 2026 for autoimmune indications. [N1] [N2]
Positive Phase 3 results for Zipalertinib in EGFR Exon 20 insertion-positive NSCLC and outlined Q4 2026 milestones—particularly for CLN-978 and CLN-049—define the near-term opportunity set. [N4] [N5] [N6]
The transition out of smaller reporting company status after December 31, 2026, will increase disclosure and compliance requirements, potentially diverting resources and management attention. [S2]
Pipeline Economics: High-Risk, High-Reward R&D Model Underwrites Value Creation
Cullinan’s business model is typical of clinical-stage biopharma: value is created through the advancement and de-risking of a diversified portfolio of T cell engager assets, with monetization hinging on successful clinical milestones, potential partnering/licensing, and eventual commercialization. Revenue is not currently generated, and the company reported a net loss of $219.9 million for 2025, underscoring the capital-intensive nature of late-stage drug development. [S2]
The economics of T cell engagers, particularly in oncology and autoimmune indications, can be attractive if clinical efficacy and safety are demonstrated. Pricing for novel oncology therapies can be premium, but market access and payer acceptance increasingly hinge on differentiated outcomes and real-world value. If Cullinan advances assets to approval, it could face high gross margins, but commercial infrastructure buildout and post-marketing commitments would drive up fixed costs, potentially delaying operating leverage.
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. The risk-reward calculus is driven by binary clinical outcomes, and capital allocation discipline will be tested as multiple programs reach value inflection points.
Therapeutic Differentiation Versus a Crowded Immuno-Oncology and Autoimmune Arena
Cullinan operates in highly competitive markets where large pharmaceutical companies and well-funded biotechs are aggressively pursuing T cell engagers and next-generation immunotherapies. The company’s potential moat rests on its proprietary technology platform and its ability to address difficult-to-treat cancers and autoimmune diseases with differentiated mechanisms of action.
However, barriers to entry are modest in terms of scientific innovation cycles, and clinical success in early-stage studies does not guarantee regulatory approval or commercial uptake. Larger incumbents may outspend or outpace Cullinan in pivotal trials, and emerging modalities such as bispecifics, CAR-Ts, and engineered cytokines vie for similar clinical endpoints.
Sustainable advantage will depend on demonstrable improvements in efficacy, safety, and patient convenience, as well as strategic partnerships or licensing that can accelerate late-stage development and market access. Intellectual property and first-mover status in selected indications could offer temporary protection, but switching costs and customer lock-in are typically low in specialty therapeutics absent compelling clinical data.
Catalyst-Driven Value Creation if Clinical Data Surpass Expectations
A favorable scenario for Cullinan would see upcoming Q4 2026 data for CLN-978 and CLN-049 exceed clinical benchmarks in efficacy and safety, leading to accelerated regulatory paths or attractive partnership deals. Positive Phase 3 data for Zipalertinib could position the company as a commercial player or make it an acquisition target, especially if real-world evidence confirms trial results.
If Velinotamig demonstrates strong proof-of-concept in systemic lupus erythematosus or other autoimmune indications, Cullinan could diversify beyond oncology and attract interest from larger autoimmune-focused partners.
Confirmation of this scenario would be signaled by: successful clinical readouts, rapid initiation of registrational trials, non-dilutive capital inflows (such as licensing up-fronts or milestone payments), and analyst upward revisions. Conversely, failure to convert positive data into partnering or regulatory momentum would falsify the thesis.
Multiple Shots on Goal, Cash Runway, and a Measured March Toward Pivotal Data
The most plausible trajectory is that Cullinan continues to advance its T cell engager pipeline through sequential data readouts, leveraging its current liquidity to fund ongoing studies while actively seeking partnerships to offset future capital needs. Some programs may show incremental efficacy, supporting further investment, while others could face setbacks typical of clinical-stage portfolios.
Analyst interest and a diversified pipeline provide downside mitigation, but the absence of near-term commercial revenue and persistent net losses will necessitate eventual capital raises or strategic deals. Increased SEC compliance post-2026 may incrementally raise costs but is unlikely to be thesis-defining unless coupled with operational missteps.
Disconfirming evidence would include major clinical failures, inability to secure partnerships, or rapid liquidity erosion.
Clinical Setbacks, Capital Constraints, and Regulatory Drag Could Derail Momentum
In an adverse scenario, Cullinan encounters negative or inconclusive data for its lead assets—particularly CLN-049 or Zipalertinib—eroding investor confidence and making capital raising more difficult or dilutive. Repeated clinical setbacks could force pipeline reprioritization, layoffs, or asset sales.
The loss of smaller reporting company status compounds the challenge by increasing compliance costs and administrative burden, further straining resources. If the company is unable to secure strategic partnerships or non-dilutive funding, it may have to pursue dilutive equity raises at depressed valuations, exacerbating shareholder dilution.
Confirmation of this scenario would include: negative clinical trial readouts, cash burn rates exceeding projections, forced asset out-licensing on unfavorable terms, or management turnover. Falsification would come from successful data catalysts, new partnerships, or creative capital solutions that stabilize the outlook.
Milestones and External Triggers That Will Determine Cullinan’s Next Phase
Upcoming Q4 2026 clinical data for CLN-978 and CLN-049—actual efficacy and safety outcomes versus industry benchmarks. [N4] [N5]
Progression of Zipalertinib toward regulatory submission or meaningful partnering activity following Phase 3 results. [N6]
Cash burn trajectory and updated guidance onreported liquidity position, particularly in light of increased compliance obligations post-2026. If disclosed, quarterly cash utilization would help test financial discipline.
Announcements of new partnerships, licensing deals, or non-dilutive financings that could reduce future equity dilution. [N7] [N8]
Regulatory feedback or acceptance of pivotal trial designs by FDA or EMA for lead assets—would signal path clarity.
Clinical pipeline attrition: discontinuation, reprioritization, or asset sales should be monitored as signals of pipeline health.
Changes in management or board composition, particularly if tied to strategic pivots or operational underperformance.
Analyst estimate revisions or coverage changes in response to new data, capital actions, or competitive developments.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments