
Columbia Financial: Credit Discipline, Community Banking Scale, and the Stakes of Economic Sensitivity
The interplay between community banking strengths and macroeconomic exposure will determine its ability to sustain growth and manage downside shocks.
Its continued performance will depend on its ability to navigate economic cycles and maintain asset quality, particularly as non-performing loans are heavily collateral-dependent. Investors should focus on credit metrics, collateral trends, and the sustainability of recent earnings improvements as key thesis tests. [S2] [N2] [N5]
Columbia Financial, Inc., parent of Columbia Bank, is navigating a period marked by strong recent earnings performance and prudent risk management, but faces ongoing challenges tied to credit quality and economic fluctuations. While Q3 and Q2 2026 results exceeded expectations, the company’s heavy reliance on collateral-backed lending and exposure to local economic cycles means that asset quality and disciplined underwriting will be critical to sustaining its trajectory.
Recent Earnings Surprises and Credit Discipline Shape the Current Outlook
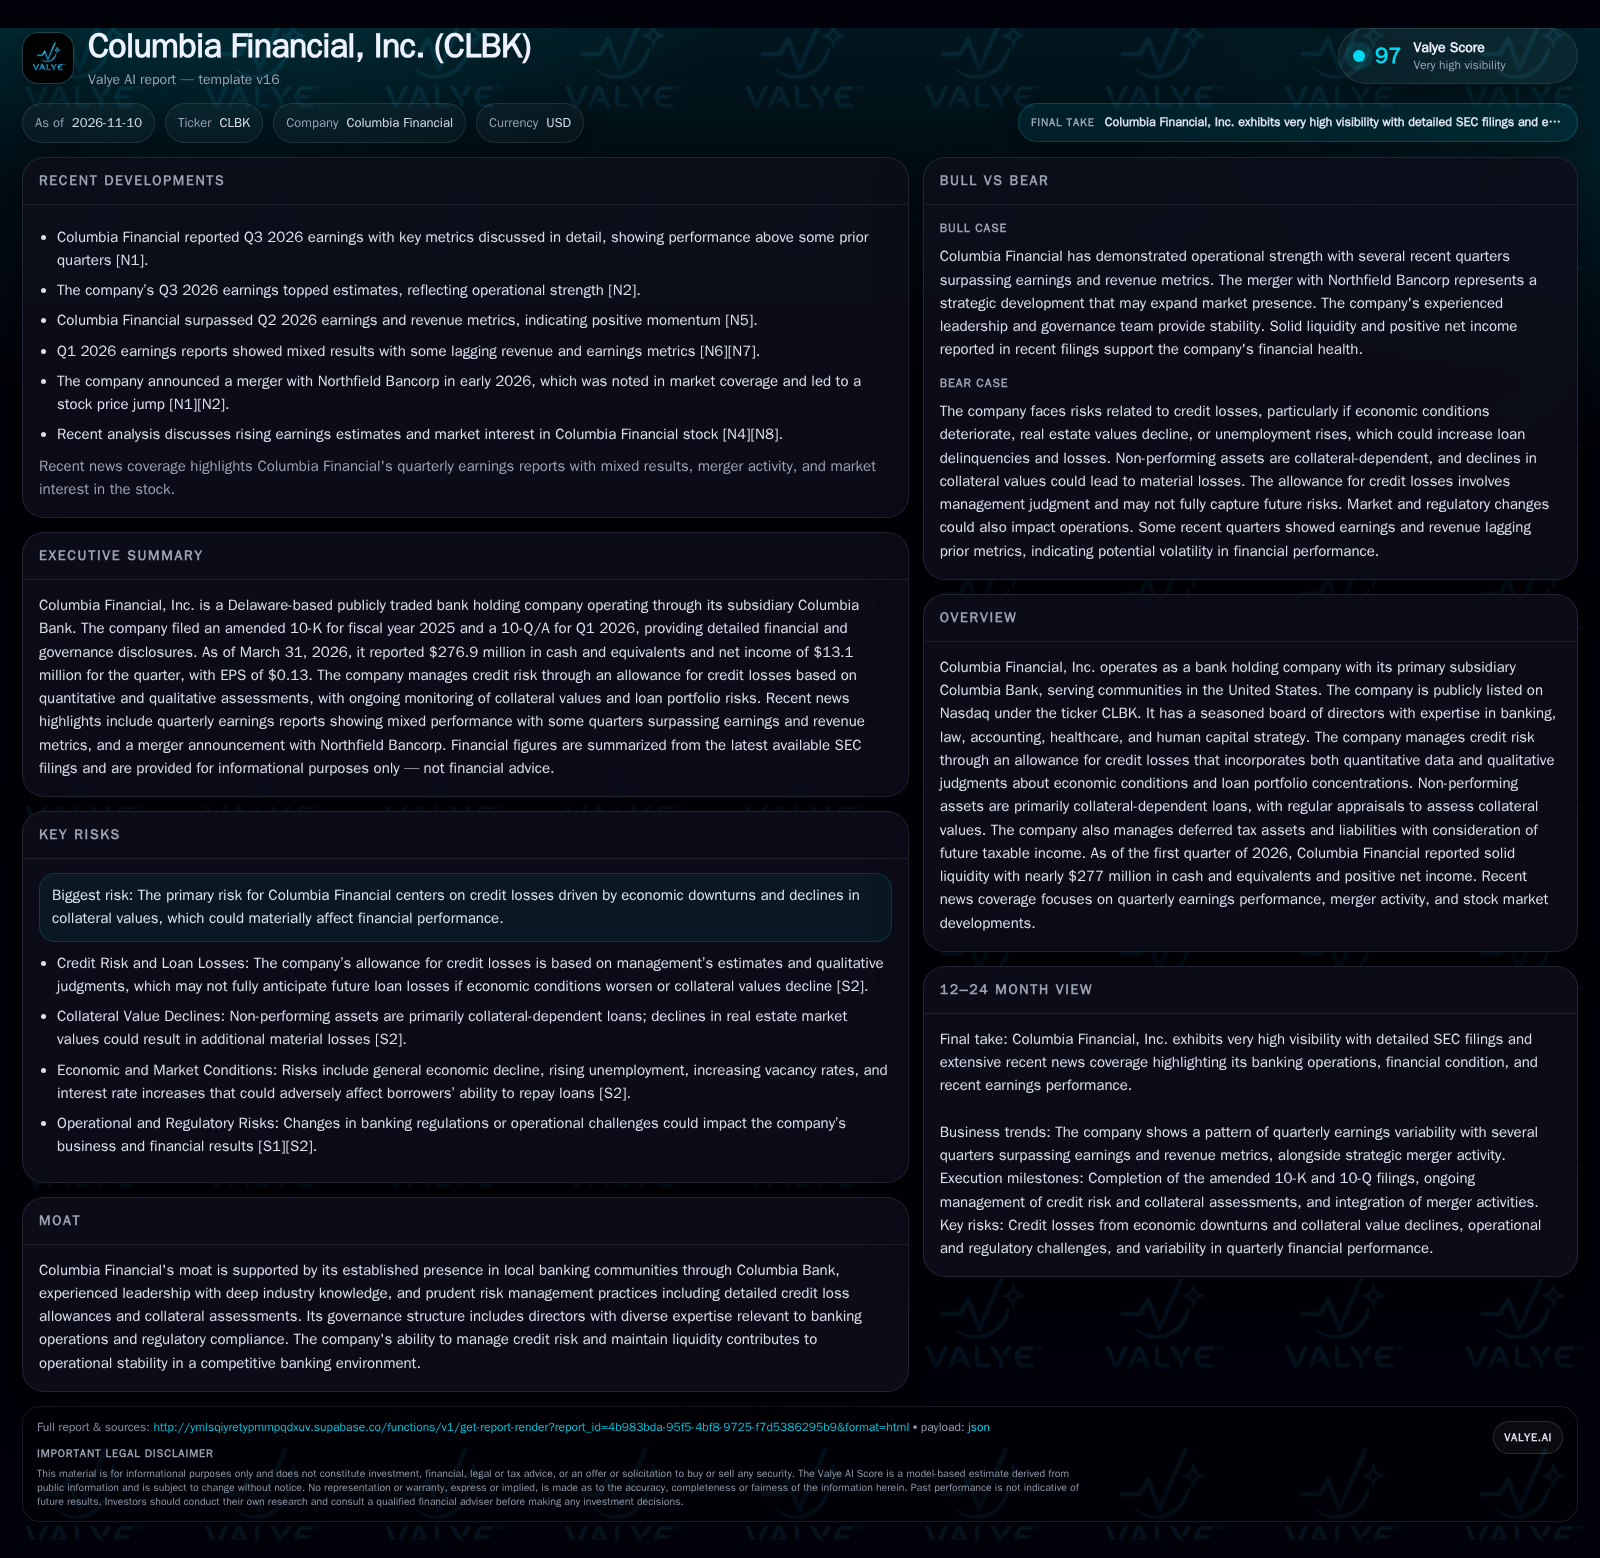
Columbia Financial, Inc. reported Q3 and Q2 2026 earnings that surpassed analyst estimates, reflecting a period of operational strength and positive momentum in core banking activities. The company disclosed $276.9 million in cash and cash equivalents as of March 31, 2026, alongside net income of $13.1 million and $0.13 in earnings per share for Q1 2026. However, Q1 results were mixed, with some revenue and earnings metrics lagging previous quarters, underscoring ongoing earnings volatility. Management continues to emphasize rigorous credit risk controls, with an allowance for credit losses informed by both quantitative models and qualitative economic assessments. The loan portfolio’s non-performing assets are managed primarily through collateral-dependent loans, subject to regular appraisals and fair value adjustments. [S2] [N2] [N5] [N6] [N7]
How Columbia Financial Earns: Interest Margins, Cost Structure, and Credit Loss Leverage
Columbia Financial’s core economics are those of a traditional community bank: it generates revenue primarily through net interest margin (NIM) on loans and investments, supplemented by fee income from deposit and banking services. Its cost base is dominated by interest expense on deposits and borrowings, personnel, and regulatory compliance. The company’s profitability is highly sensitive to the spread between asset yields and funding costs—a relationship influenced by interest rate cycles, deposit mix, and competitive pricing.
Credit losses are a central swing factor. The company’s allowance for credit losses directly impacts net income, especially in periods of economic stress or when collateral values fluctuate. Because non-performing loans are largely collateral-dependent, shifts in local real estate or asset values can rapidly alter loss expectations. Fixed costs in community banking (branches, compliance, technology) mean that Columbia may achieve operating leverage as loan and deposit volumes grow, but it also faces margin pressure if competitive rates rise or economic conditions weaken. Capital needs are moderate for a well-capitalized bank, but unexpected credit events can quickly increase reserve requirements and dampen earnings.
Community Banking Roots and the Battle for Deposits and Asset Quality
Columbia Financial’s competitive positioning is anchored in its established presence within local markets, brand recognition through Columbia Bank, and longstanding customer relationships. Community banks often compete on service, local knowledge, and relationship lending, which can support customer retention and pricing discipline—especially with small businesses and retail clients. The experienced board offers governance strength and sector expertise, potentially aiding regulatory navigation and risk management. [S1]
Counterforces remain. Larger regional and national banks can outcompete on technology investment, digital service breadth, and pricing power. Fintech entrants and non-bank lenders may threaten deposit growth and encroach on specialty lending niches. Columbia’s dependence on collateral-dependent lending exposes it to local real estate cycles, which can be more volatile than diversified national portfolios. Substitution risk arises if customers migrate to digital-first banks or if alternative lending platforms offer more attractive terms.
If Credit Quality Holds and Deposit Franchise Deepens, Earnings Power Could Expand
The most favorable scenario for Columbia Financial is one in which local and regional economic conditions remain stable or improve, supporting both asset quality and loan demand. If commercial and consumer borrowers maintain repayment capacity and collateral values remain resilient, credit losses could stay below historical averages—allowing the company to release reserves or keep provisioning low. This, combined with continued deposit growth and stable funding costs, could drive further NIM expansion and operating leverage.
Confirmation would come from several quarters of declining or stable non-performing asset ratios, modest or falling credit loss provisions, and evidence of deposit growth outpacing peers. Outperformance versus loan growth targets and sustained above-peer return on equity would further validate the bull case. Falsification would be signaled by an uptick in delinquencies, rapid provisioning increases, or deposit outflows as customers chase higher rates elsewhere.
Earnings Variability Remains as Credit and Funding Cycles Fluctuate
The most likely path for Columbia Financial is continued earnings variability, reflecting its exposure to credit cycles and competition for deposits. Periods of outperformance—such as the recent quarters—may be interspersed with quarters where higher credit provisioning or margin compression erode results.
This scenario would be confirmed by ongoing quarter-to-quarter swings in net income and EPS, with credit loss provisions and non-performing asset ratios moving in line with macroeconomic indicators and industry norms. A base case would also see Columbia maintaining or modestly growing its loan book and deposit base, but not decisively outpacing regional peers. Falsification would involve either a sustained period of above-peer earnings growth (signaling upside) or a pronounced, persistent deterioration in asset quality or funding costs (signaling downside).
Material Credit Deterioration or Collateral Value Declines Could Pressure Capital and Earnings
A negative trajectory could unfold if economic conditions worsen—through rising unemployment, declining real estate values, or sector-specific shocks—leading to an increase in loan delinquencies and defaults. Because Columbia’s non-performing assets are largely collateral-dependent, a sharp drop in collateral values would force additional write-downs and credit loss provisions, directly impacting net income and potentially eroding capital ratios.
This scenario would be confirmed by a rapid rise in non-performing asset ratios, accelerated provisioning, and possible regulatory scrutiny of capital adequacy. If depositors lose confidence or seek higher rates, Columbia could also face funding pressure, further squeezing margins. A downside spiral could be triggered by negative trends in local real estate, adverse economic headlines, or evidence of stressed borrowers in the company’s core markets.
Thesis Tests: What Will Determine Columbia Financial’s Next Phase?
Quarterly trends in non-performing asset ratios and credit loss provisions—if disclosed—will be critical to assess underlying asset quality and risk management effectiveness.
Net interest margin (NIM) evolution, especially relative to regional peers, would help evaluate pricing power and funding cost discipline.
Deposit growth rates and customer mix (retail vs. business)—if disclosed—would clarify Columbia's competitive position in core markets.
Quarterly loan growth and composition (commercial vs. consumer, real estate vs. other)—with disclosure—will indicate the sustainability of earnings momentum.
Updates on collateral reappraisal outcomes and any notable write-downs would help gauge exposure to local real estate cycles.
Board or management commentary on economic outlook and credit risk appetite—if provided—will illuminate strategic posture and risk tolerance.
Any regulatory filings or capital adequacy disclosures in response to changing asset quality would be key signals of stress or resilience.
Sustained divergence—positive or negative—in EPS versus consensus estimates could signal inflection points in underlying business momentum.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments