
Surgery Partners: Outpatient Surgical Scale, Payer Leverage, and the Stakes of a Pending Take-Private Transaction
Surgery Partners is navigating a critical juncture as a leading operator of outpatient surgical facilities, balancing scale-driven economics and payer mix exposure against the uncertainties and operational constraints of a major take-private merger. The company's recent performance reflects underlying growth in revenue per case and reported liquidity position, but the outcome and implications of the Spyglass Topco deal now dominate the forward thesis.
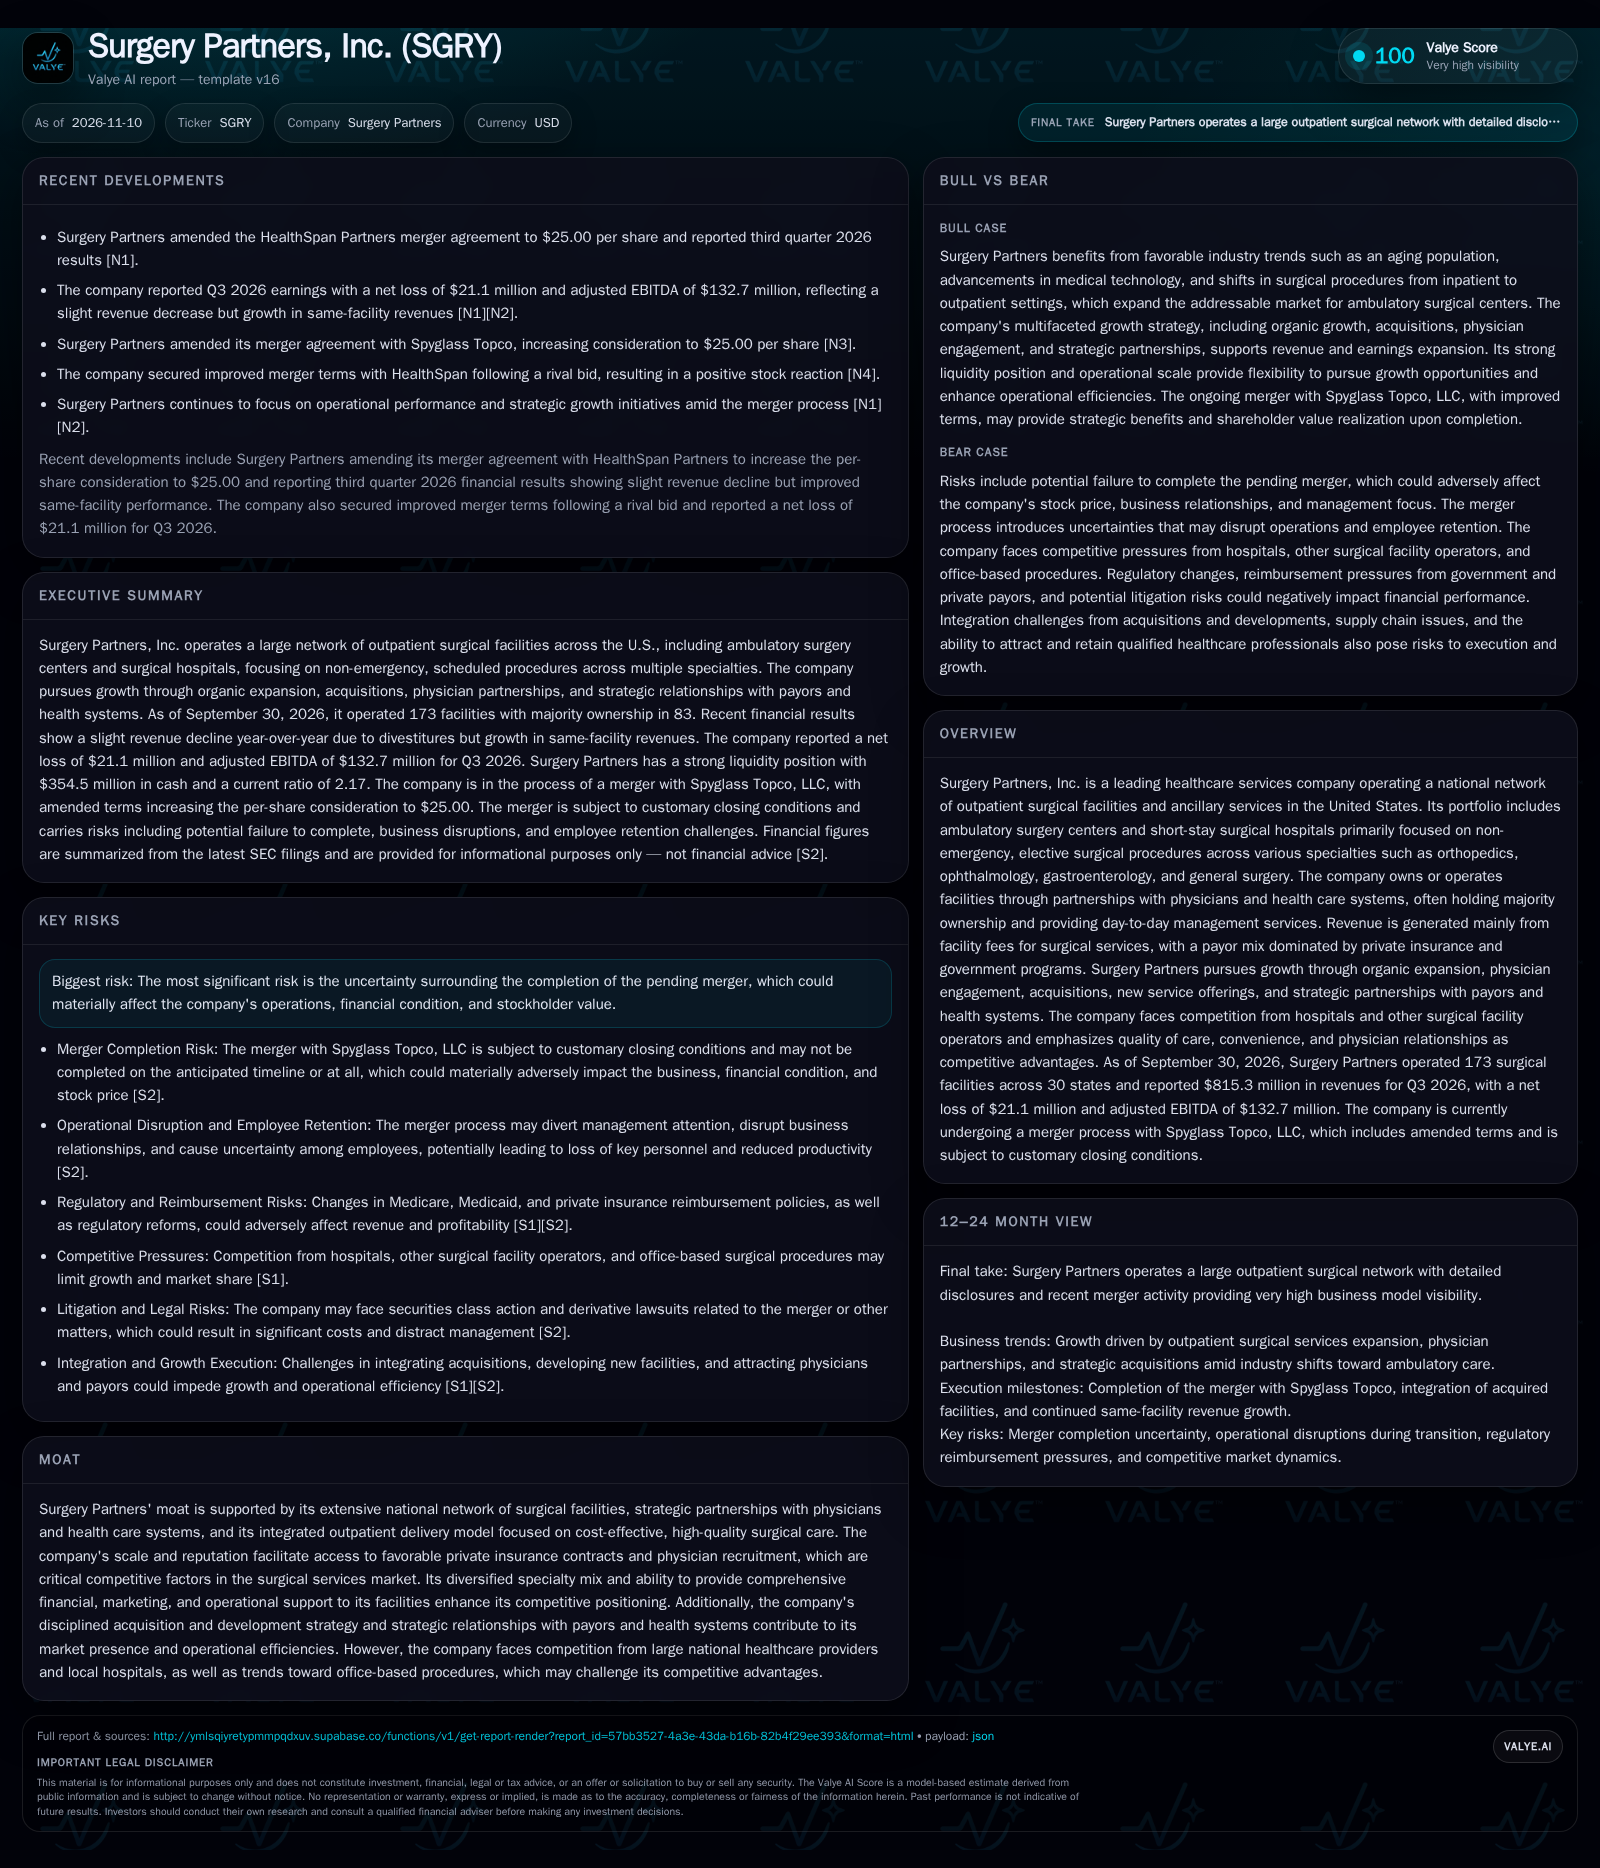
Surgery Partners operates a broad national network of ambulatory surgery centers and hospitals, with Q3 2026 results showing underlying same-facility growth but headline revenues slightly down due to divestitures. The company’s adjusted EBITDA margin remains substantial, and its reported liquidity position. However, the pending merger with Spyglass Topco will likely reshape both governance and strategic direction, introducing new risks and potential value realization for shareholders. The interplay between payer mix shifts, operational leverage, and the evolving competitive landscape will remain central to long-term economics, regardless of the transaction outcome. [S2] [N1] [N3]
Surgery Partners, Inc. stands at a pivotal crossroads for both its business model and shareholder base. As a scaled operator of outpatient surgery centers and surgical hospitals, the company has demonstrated resilience through solid same-facility growth and disciplined operational management. Yet, headline revenue declines and a pending take-private merger with Spyglass Topco have introduced both immediate uncertainty and the prospect of strategic transformation. The forward outlook now hinges on the interplay between payer mix dynamics, the economics of outpatient surgical care, and the unresolved question of transaction closure and post-merger integration.
Merger Terms, Facility Trends, and Underlying Growth: What the Latest Quarter Reveals
Surgery Partners reported Q3 2026 revenues of $815.3 million, down 0.8% year-over-year, primarily due to facility divestitures. However, adjusted same-facility revenues increased 6.0%, driven by a 5.8% rise in revenue per case and almost flat (+0.2%) same-facility case volume, highlighting underlying organic momentum despite portfolio changes [S2].
The company’s adjusted EBITDA for the quarter was $132.7 million, a 2.7% decrease from the previous year, indicating relative margin stability even as overall revenues dipped [S2].
As of September 30, 2026, Surgery Partners operated 173 facilities across 30 states, with majority ownership in 83 and a consolidated reporting base of 115 facilities [S2]. The payor mix remains balanced but is shifting: 52.3% private insurance, 42.8% government, and the remainder self-pay and other categories [S1].
The pending merger with Spyglass Topco, under amended terms, will take the company private at $25.00 per share, subject to customary closing conditions including shareholder and regulatory approvals [S2] [N1] [N3]. This development dominates the near-term outlook, with risks of disruption, litigation, and employee retention flagged in company disclosures [S2].
How Outpatient Surgery Economics Drive Margins and Strategic Flexibility
Surgery Partners generates the vast majority of its revenue from facility fees for scheduled surgical procedures, unlike traditional hospitals that also depend on emergency and high-acuity inpatient volumes. This outpatient focus enables more predictable scheduling, lower fixed costs per procedure, and opportunities for scale-driven purchasing and administrative efficiencies.
The company’s economic model hinges on two key levers: case volume and revenue per case. The latter is influenced by specialty mix (e.g., orthopedics and ophthalmology typically command higher rates), payer mix, and negotiated reimbursement contracts. An increase in revenue per case, as seen in Q3 2026, may reflect favorable shifts in procedure type, payer negotiations, or case complexity, but could also be partially offset by flat or declining volumes if macroeconomic or competitive pressures persist [S2].
Fixed costs at the facility level—staff, lease, equipment—are partially offset by variable labor and supply expenses, creating operating leverage when volumes expand. However, the company must continually invest in physician partnerships, compliance, and technology to maintain its competitive position and regulatory standing.
Capital needs are moderate for ongoing operations but can spike with acquisitions, facility upgrades, or expansion into new specialties. The company’s liquidity position as of late 2026 ($354.5 million cash and $692.8 million revolver availability) provides optionality for both organic and inorganic growth, though the impending merger may shift capital allocation priorities post-close [S2].
Scale, Payer Relationships, and Physician Engagement as Competitive Differentiators
Surgery Partners’ national footprint of 173 facilities across 30 states offers meaningful scale advantages in payer negotiations, supply chain management, and clinical standardization. This breadth supports negotiating leverage with both private insurers and government programs, which is critical as reimbursement pressures intensify sector-wide.
The company’s integrated outpatient model and physician partnership structure are designed to attract high-quality providers and foster physician alignment, which can enhance procedural throughput and specialty mix. However, physician recruitment and retention remain ongoing challenges, especially as office-based procedural alternatives grow and competitors seek to replicate similar partnership models.
Key competitor categories include large hospital systems expanding outpatient footprints, other national and regional ambulatory surgery center operators, and increasingly, office-based surgical practices enabled by advances in minimally invasive techniques.
Long-term, Surgery Partners’ ability to maintain or grow its share will depend on continuing to deliver superior convenience, quality, and cost-effectiveness, while managing the risks of payer mix shifts and regulatory reimbursement changes.
If the Merger Closes Smoothly: Value Unlock, Strategic Repositioning, and Margin Expansion
A favorable scenario unfolds if the Spyglass Topco acquisition closes on schedule with minimal operational disruption. In this case, shareholders realize the $25.00 per share consideration, and the company gains access to new capital, private ownership flexibility, and potentially longer-term investment horizons less constrained by public market pressures [S2] [N1] [N3].
Post-merger, Surgery Partners could accelerate tuck-in acquisitions, specialty expansion (e.g., higher-acuity orthopedic or cardiovascular procedures), and technology-enabled operational efficiencies. Margin expansion may be achievable if the company leverages its scale to renegotiate supply contracts and payer rates, and if new ownership supports investments in physician engagement and digital infrastructure.
Evidence confirming this scenario would include: timely merger closure, minimal staff or physician turnover, acceleration of same-facility growth, improved adjusted EBITDA margins, and strategic announcements of new growth initiatives or partnerships post-close.
Falsification would come from delayed or failed transaction closure, significant loss of key personnel, or post-merger operational setbacks such as integration issues or declining facility performance.
What Stable Outpatient Growth Looks Like Absent Major Disruption
The most plausible trajectory, pending merger outcome, is that Surgery Partners continues to deliver incremental same-facility growth driven by procedure mix optimization, payer contract renewals, and selective expansion or acquisition. Margins remain relatively stable, with modest upside if pricing or specialty mix trends are favorable, but with persistent headwinds from reimbursement and labor cost pressures.
Base case confirmation would involve ongoing low- to mid-single-digit same-facility revenue growth, stable or improving adjusted EBITDA margins, and successful navigation of merger-related distractions without major operational slippage.
Evidence against this scenario would include a sharp deterioration in payer mix (e.g., rising government share without offsetting rate increases), significant case volume declines, or prolonged merger uncertainty leading to physician or staff attrition.
How Merger Failure or Payer Mix Deterioration Could Undercut Value
The most significant risk is failure to close the Spyglass Topco merger, which could result in a sharp stock price decline, heightened business uncertainty, and possible loss of strategic direction or key personnel [S2]. Operational disruption during a protracted or failed transaction process may also weaken physician and payor relationships, impeding volume growth and margin stability.
A secondary but material risk is adverse movement in payer mix—such as a higher proportion of government payors or increased reimbursement pressure from both public and private insurers. This could compress revenue per case and reduce EBITDA margins, especially if not offset by cost containment or specialty mix upgrades.
Other downside catalysts include regulatory changes reducing outpatient reimbursement, increased competition from office-based or hospital-affiliated surgical sites, or labor and supply cost inflation outpacing revenue growth.
Confirmation of this scenario would include failed or indefinitely delayed merger closure, sequential declines in same-facility growth, material increases in government payer share, and/or adverse regulatory or legal developments.
Milestones and Metrics That Will Define Surgery Partners’ Post-Transaction Value Proposition
Progress toward and ultimate completion of the Spyglass Topco merger, including shareholder approval timelines and regulatory clearance, will be the primary determinant of near-term shareholder outcomes.
Retention of key physicians and management during and after the merger process—if disclosed—will be critical for sustaining facility performance and growth.
Trends in same-facility revenue growth, broken out by volume versus revenue per case, will clarify the sustainability of underlying demand and pricing power.
Evolution of payer mix, specifically shifts between private insurance and government programs, and any disclosed changes in reimbursement rates or contract terms.
Adjusted EBITDA margin trends by quarter, especially in the context of inflationary pressures on labor and supplies.
Pace and scale of new facility openings, acquisitions, or service line expansions—if disclosed—would help test the company’s ability to deploy capital for growth post-transaction.
Any litigation, regulatory, or legal developments relating to the merger or ongoing operations, as such events could materially impact both near- and long-term value.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments