
Curaleaf’s Path Forward: Regulatory Flux, Tax Overhang, and the Limits of Scale in U.S. Cannabis
Curaleaf stands as one of the most geographically diversified operators in the U.S. cannabis sector, but its business is shaped by ongoing regulatory ambiguity, a material tax liability, and operational constraints arising from federal illegality. The company’s growth ambitions—including a pending acquisition offer—must be weighed against persistent risks unique to the cannabis value chain.
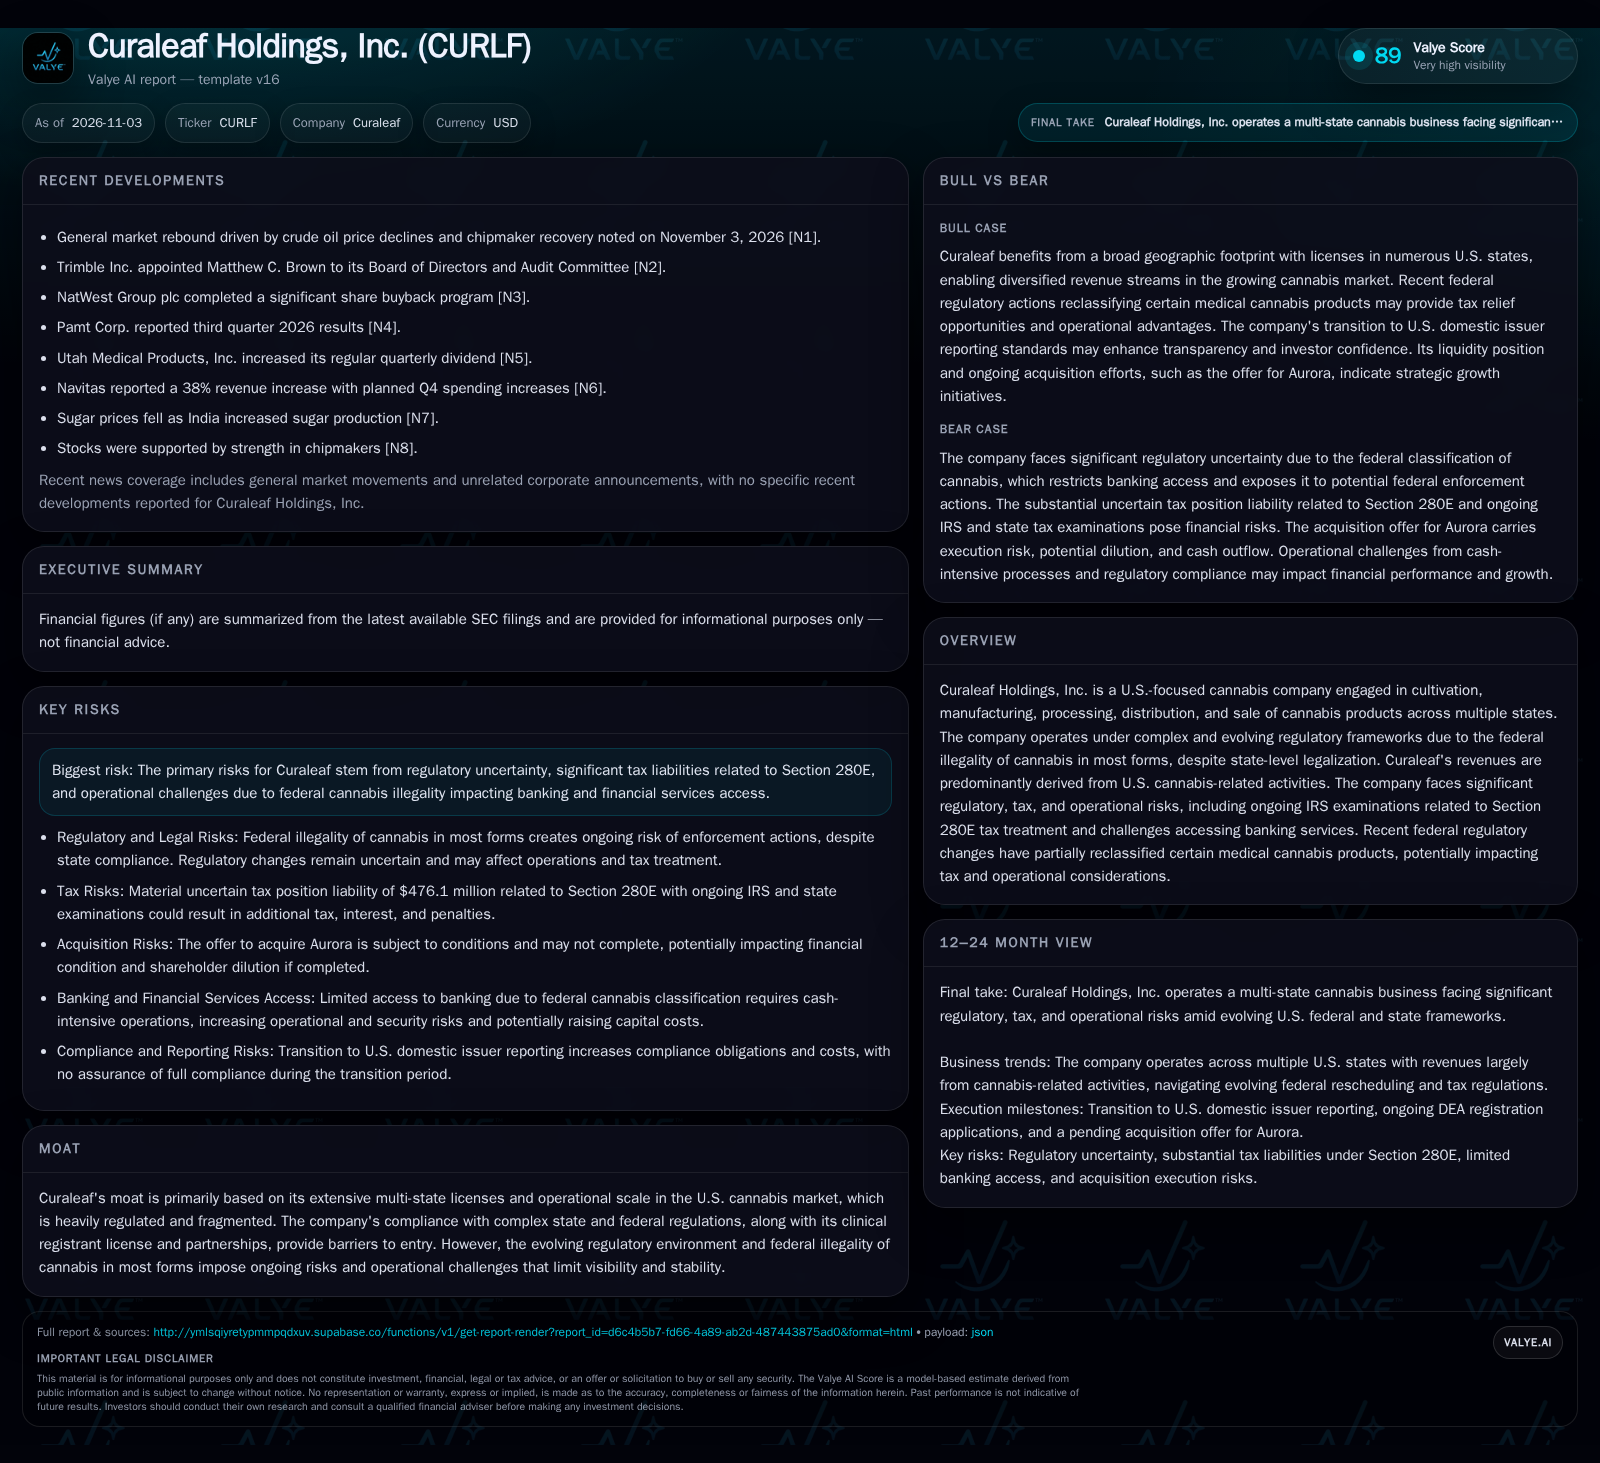
Curaleaf operates a multi-state cannabis business with 83%+ of revenues tied to U.S. cannabis activities. It faces a $476.1M uncertain tax position due to Section 280E, ongoing IRS/state examinations, and regulatory flux after partial federal rescheduling of medical cannabis. The company’s pending Aurora acquisition would require cash and share issuance, introducing dilution and liquidity questions. Operational reliance on cash transactions persists due to limited banking access. The outlook hinges on regulatory evolution, tax resolution, and Curaleaf’s ability to translate scale into sustained profitability. [S1]
Curaleaf Holdings, Inc. is emblematic of both the promise and the persistent headwinds in the U.S. cannabis sector. With operations spanning more than a dozen states and a diversified product and license portfolio, Curaleaf’s scale is rare in a fragmented market. Yet, the company’s growth is constrained by unresolved regulatory, tax, and operational hurdles—including a substantial $476 million tax liability and continuing federal illegality that limits access to banking. As Curaleaf pursues expansion through acquisition and adapts to shifting federal rules, the core question is whether its scale and regulatory adaptability can ultimately translate into durable economic advantage—or whether structural headwinds will keep profitability and capital flexibility elusive. [S1]
Material Tax Exposure, Regulatory Flux, and an Ambitious Acquisition Drive
Curaleaf’s Q3 2026 financials show 83% of revenue tied to U.S. cannabis activities, underscoring its entrenched position in state-legal markets but exposing it to federal legal risk. The company is carrying a $476.1 million uncertain tax position liability under Section 280E, with ongoing IRS and state examinations—indicating the risk of further tax, interest, or penalties. Recent federal regulatory actions have reclassified some medical cannabis products to Schedule III, which could eventually change federal tax treatment, but the legal and operational landscape remains unsettled.
Curaleaf’s pending offer to acquire Aurora, if completed, would require both cash and new share issuance, meaning dilution for current shareholders and a draw on existing liquidity. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. The company’s need to operate largely in cash due to banking restrictions adds further operational complexity and risk. [S1]
How Multi-State Cannabis Economics Are Distorted by Tax and Banking Barriers
Curaleaf’s revenue comes primarily from the sale of cannabis products—cultivation, processing, and retail—across multiple state markets, each with its own regulatory and competitive dynamics. In theory, this multi-state footprint could deliver operating leverage as fixed costs are spread over a broad base, and as regulatory moats limit new entrants. However, Section 280E of the Internal Revenue Code remains a major economic distortion: it prevents cannabis companies from deducting most ordinary business expenses, resulting in structurally higher effective tax rates and suppressing net margins.
The company’s $476.1 million tax liability highlights how operating cash flow is not fully fungible and may be subject to retroactive IRS claims. Moreover, lack of federal banking access forces Curaleaf to conduct many transactions in cash, increasing security costs and limiting financial efficiency. The capital intensity of the business is further elevated by the need for physical security, redundant compliance systems, and higher insurance premiums. While scale theoretically provides purchasing and operational efficiencies, these are partly offset by the complexity of operating in different state regimes and the drag of compliance overhead.
Curaleaf’s pending acquisition offer for Aurora could increase revenue and geographic diversity, but it would also require substantial cash outlay and share issuance, diluting existing equity holders. The company’s ability to generate positive free cash flow and reinvest in growth is thus constrained by both external (tax and regulatory) and internal (acquisition funding) demands. [S1]
Scale, Licensing, and the Barriers—But Not Immunity—from Structural Risks
Curaleaf’s principal competitive asset is its multi-state license portfolio, which is difficult to replicate given regulatory caps, capital requirements, and the lengthy application process in most markets. This scale advantage enables Curaleaf to diversify revenue streams across states, potentially dampening volatility from single-market shocks. In addition, its clinical registrant license in Pennsylvania and compliance infrastructure may provide first-mover or knowledge advantages in adapting to shifting regulations.
However, these advantages do not confer immunity from industry-wide headwinds. The fragmented U.S. cannabis market is increasingly competitive, with both existing multi-state operators and well-capitalized local players vying for share in limited-license states. Price compression—driven by oversupply in mature markets—can erode margins, and Curaleaf’s geographic breadth may dilute its ability to dominate any single market. The company’s exposure to ongoing regulatory risks, especially unresolved federal tax treatment and banking constraints, is shared across the sector. Substitution risk from illicit markets and emerging alternative products (e.g., synthetic cannabinoids, hemp-derived THC analogs) also weighs on long-term pricing power.
Ultimately, Curaleaf’s moat is real but conditional: it rests on its ability to maintain licensure, navigate compliance, and adapt faster than regional or national peers as the regulatory environment evolves. [S1]
If Regulatory Relief and Tax Reform Arrive in Tandem, Scale Could Unlock Margin Expansion
The most favorable scenario for Curaleaf is a convergence of regulatory and tax reform. If the reclassification of certain cannabis products to Schedule III leads to broad IRS acceptance of normal business deductions, Curaleaf’s effective tax rate could fall dramatically—freeing up operating cash flow for reinvestment or debt reduction. Simultaneous progress on federal banking reform (such as passage of the SAFE Banking Act or related measures) would enable access to lower-cost financial services, streamline operations, and reduce cash-handling risks.
In this environment, Curaleaf’s multi-state scale would become a true competitive weapon: the company could leverage purchasing power, centralized compliance, and brand reach to drive margin expansion. The Aurora acquisition, if executed on favorable terms, could further solidify its position as a top-tier national operator and enable cross-state synergies.
Confirmation of this scenario would come from rapid regulatory implementation—IRS guidance on Section 280E changes, major banks entering the sector, and Curaleaf reporting meaningful reductions in tax expense and improved operating margins. Evidence of successful Aurora integration and accretive financial performance would further validate the upside case. Conversely, slow or piecemeal reform, persistent tax outflows, or integration setbacks would undermine this trajectory.
Regulatory Uncertainty Persists, Forcing Incrementalism and Defensive Capital Allocation
The most plausible near-term scenario is continued regulatory limbo. Federal rescheduling and banking reform proceed slowly or partially, with ambiguity on when (or if) Section 280E relief will be fully realized. Curaleaf is forced to manage a large tax liability, allocate capital defensively, and operate with cash-handling inefficiencies. Margins remain under pressure due to high compliance costs and limited ability to deduct expenses.
Incremental state-by-state growth continues, but price competition and oversupply in mature markets constrain margin expansion. The Aurora acquisition, if completed, delivers revenue diversification but is not immediately accretive, given integration costs and share dilution. Cash flow is sufficient to maintain operations and fund compliance, but not to meaningfully accelerate growth. The company’s competitive position is stable, but the equity story is capped by regulatory and tax drag.
Evidence for this scenario would include continued reporting of material tax liabilities, lack of clear IRS or federal banking policy changes, and slow or uneven margin improvement. Any delays or complications in the Aurora deal would further reinforce the base case.
Tax Shock, Regulatory Setbacks, or Cash Crunch Expose Structural Fragility
The adverse scenario is triggered if the IRS or state tax authorities impose additional penalties, accelerate payment demands, or deny anticipated relief from Section 280E, forcing Curaleaf to make large cash outflows or take on expensive debt. A failure to secure or maintain DEA registration for qualifying operations could further limit future growth or expose the company to enforcement risk.
Federal regulatory stasis or regression—such as renewed enforcement or further delays in banking reform—would prolong cash-intensive operations, drive up security and compliance costs, and further constrain working capital. If the Aurora acquisition proceeds under these conditions, the resulting dilution and cash outflow could exacerbate balance-sheet stress, potentially requiring asset sales or capital raises at unfavorable terms.
Confirmation of this scenario would include large one-time tax charges, negative working capital trends, missed compliance milestones, or adverse regulatory actions. Evidence of cash shortages, forced asset sales, or punitive financing would further indicate downside realization.
What Will Determine Whether Curaleaf’s Scale Translates to Sustainable Value?
Progress—or lack thereof—on IRS guidance and federal policy regarding Section 280E tax deductibility for state-legal cannabis businesses. A useful metric would be any reduction in the company’s reported uncertain tax position liability or tax expense ratios.
Updates on Curaleaf’s application for DEA registration for qualifying operations, including whether registration is granted and maintained. Confirmation of expanded access would support the regulatory-adaptation thesis.
Clarity and execution milestones on the Aurora acquisition: deal closing, integration updates, and pro forma financial disclosures will be critical to assessing whether the transaction is accretive or dilutive.
Trends in gross margin and operating margin, especially any evidence of improvement tied to regulatory or tax relief (if disclosed).
State-level revenue and market share trends, if disclosed, to test whether Curaleaf’s geographic diversity is translating to stable or growing share in key markets.
Evidence of improved access to banking and lower cash-handling costs, such as new financial partnerships or reductions in security/compliance overhead.
Any new regulatory actions—positive or negative—at the federal or major state level that materially alter the operational or financial landscape for U.S. cannabis operators.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments