
InnovAge’s Government Healthcare Growth: Regulatory Leverage and Fragility in Focus After Q4 Miss
InnovAge Holding Corp. shows double-digit revenue growth but faces structural risks as a government-reimbursed healthcare provider. Recent capital raising and earnings volatility underscore how regulatory, reimbursement, and operational factors could shape future outcomes.
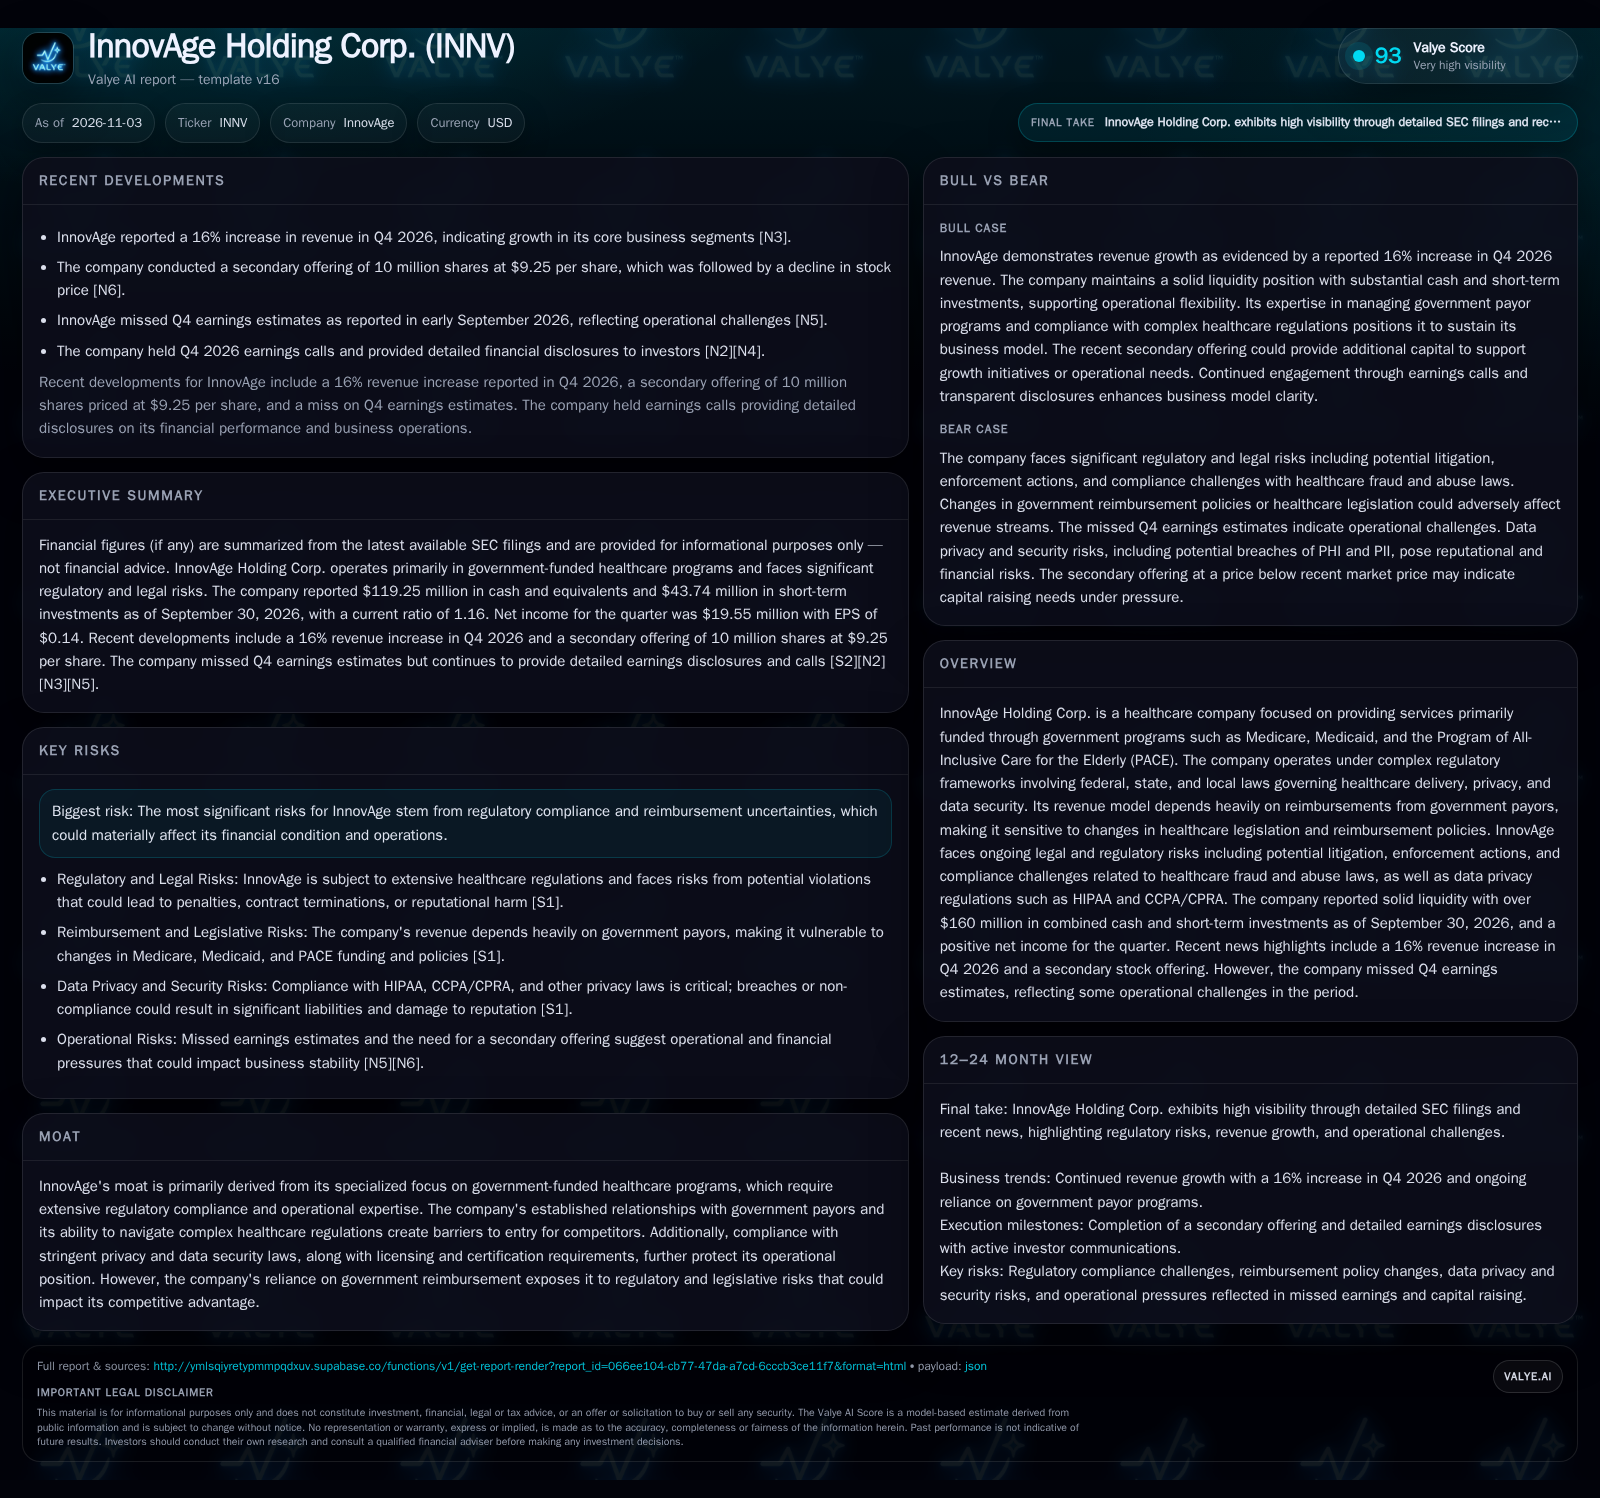
InnovAge Holding Corp. reported a 16% revenue increase in Q4 2026 but missed earnings estimates and raised capital through a secondary share offering. The company’s reliance on Medicare, Medicaid, and PACE programs drives both its growth and its vulnerability to regulatory and reimbursement changes. [S2] [N2] [N3] [N5] [N6]
InnovAge Holding Corp. is navigating a complex inflection point. Despite a robust 16% revenue jump in Q4 2026, the company missed earnings expectations and turned to the equity markets for fresh capital. This juxtaposition of top-line momentum and bottom-line shortfall spotlights InnovAge’s core challenge: translating its scale in government-funded healthcare into durable, margin-accretive growth while managing significant regulatory, reimbursement, and compliance risks. The company’s recent results and capital actions reveal both the opportunities and fragilities of a business model deeply tethered to policy currents.
Recent Revenue Growth and Capital Moves Shape InnovAge’s Risk-Reward Profile
InnovAge reported a 16% increase in revenue for Q4 2026, indicating growth in its Medicare, Medicaid, and PACE-funded operations. However, the company missed Q4 earnings estimates, with net income at $19.55 million and EPS of $0.14 for the quarter. The company also completed a secondary offering of 10 million shares at $9.25 per share, shortly after which its stock price declined. As of September 30, 2026, InnovAge held $119.25 million in cash and $43.74 million in short-term investments, with a current ratio of 1.16. These facts collectively signal a company experiencing topline momentum but facing operational and capital allocation pressures, and underline its ongoing exposure to swings in earnings performance and the need to buffer liquidity. [S2] [N2] [N3] [N5] [N6]
How InnovAge’s Revenue Model Balances Scale and Sensitivity
InnovAge’s economics are fundamentally driven by per-capita payments and reimbursements from government payors, primarily under Medicare, Medicaid, and PACE. This structure provides recurring revenue potential and can support scale in regions where the company can aggregate sufficient patient volume. However, pricing is largely set by policy rather than market negotiation, which limits the company’s ability to offset rising costs or margin pressures through rate increases. Volume growth—expanding the pool of eligible seniors or increasing market penetration—remains one of the few levers for revenue expansion.
The model is capital-intensive in administrative overhead, compliance, and care delivery infrastructure. Operating leverage can emerge if fixed administrative and regulatory costs are spread over a larger member base, but this is counterbalanced by the need to maintain high compliance standards. Changes in reimbursement rates or eligibility criteria could have immediate and material impacts on profitability, given the low pricing flexibility and high fixed-cost base. Recent capital raising via a secondary offering suggests either a need to fund growth initiatives or to shore up balance sheet flexibility amid operational volatility.
The reliance on government payors creates a unique dynamic where InnovAge’s revenue streams are relatively predictable but also inherently inflexible. This inflexibility means that cost management becomes a critical determinant of profitability, as the company cannot easily pass through cost increases to payors. In this context, operational efficiency initiatives—such as optimizing care coordination, reducing hospital readmissions, and leveraging data analytics to improve patient outcomes—are essential to sustaining margins. Moreover, the capital-intensive nature of compliance requires continuous investment in systems and personnel, which may limit the pace at which operating leverage can be realized, especially if regulatory requirements tighten or evolve rapidly.
Barriers and Vulnerabilities in a Heavily Regulated Niche
InnovAge’s competitive position is shaped by its deep specialization in government-funded elder care, particularly through PACE. The regulatory complexity and operational expertise required to participate in these programs create real barriers to entry for new competitors. Existing relationships with government payors, licensing, and compliance infrastructure further entrench incumbents.
However, this moat is double-edged: the same regulatory environment that limits competition also exposes InnovAge to abrupt policy shifts or enforcement actions that could erode its operating base. Competing providers—such as other specialized PACE operators, managed care organizations, and large regional healthcare systems—may have broader resources or diversified revenue streams, potentially allowing them to weather reimbursement shocks more effectively. Technology-enabled disruptors and home-based care models could also incrementally erode InnovAge’s share if regulatory frameworks evolve to support alternative care delivery.
InnovAge’s specialization in PACE and related government programs positions it within a niche that demands not only regulatory compliance but also high-quality care delivery tailored to complex patient needs. This dual requirement strengthens barriers to entry but also exposes the company to risks if it fails to maintain clinical outcomes or patient satisfaction. Competitors with broader service portfolios or integrated healthcare delivery models may be better positioned to absorb regulatory shocks or diversify revenue, potentially exerting pressure on InnovAge’s market share. Additionally, evolving healthcare policies that encourage value-based care and alternative payment models could reshape competitive dynamics, making adaptability and innovation critical to maintaining a defensible position.
What Could Unlock Sustained Margin Expansion and Market Share Gains?
If InnovAge can continue to drive double-digit revenue growth while translating scale efficiencies into improved margins, the company could materially outpace policy-driven headwinds. Evidence that would confirm this scenario includes sustained revenue growth above industry norms, margin expansion even as regulatory costs rise, and successful deployment of secondary-offering proceeds into accretive growth or operational upgrades.
Additional confirmation could come from stable or rising reimbursement rates, positive policy developments favoring PACE expansion, and a track record of regulatory compliance with minimal enforcement actions. Demonstrated ability to control care costs per member while maintaining quality would also reinforce the upside thesis. Conversely, a sharp uptick in compliance costs or a failure to convert scale into margin would falsify this scenario.
Sustained margin expansion would likely depend on InnovAge’s ability to scale its administrative infrastructure efficiently while maintaining or improving quality metrics that influence reimbursement rates and regulatory goodwill. If the company can leverage technology to automate compliance processes, enhance care coordination, and reduce manual interventions, fixed costs per member could decline, driving operating leverage. Furthermore, favorable policy shifts expanding eligibility or increasing reimbursement rates for PACE programs would amplify growth potential. Strategic investments funded by capital raises could accelerate geographic expansion or service diversification, provided these initiatives are executed with discipline and yield measurable improvements in member outcomes and cost efficiencies.
Stability Hinges on Execution and Policy Continuity
The most plausible outcome is that InnovAge achieves moderate revenue growth, with profitability fluctuating in response to reimbursement policy, compliance costs, and operational execution.
Confirmation for this scenario would include mid-single-digit to low-double-digit revenue growth, stable but modest margins, and continued but cautious capital deployment. Watchpoints include ongoing regulatory reviews, updates to Medicare/Medicaid rates, and quarterly earnings performance relative to expectations. A major regulatory shock, loss of key contracts, or persistent underperformance on margins would challenge the base case.
How Regulatory or Operational Shocks Could Erode InnovAge’s Model
Downside risks for InnovAge crystallize if reimbursement rates are cut, eligibility rules tighten, or the company faces significant legal or regulatory penalties. Operational missteps—such as data privacy breaches, quality failures, or compliance violations—could trigger contract terminations or costly settlements, directly impacting both revenue and reputation.
Evidence supporting this scenario would include declining revenue or membership, rising compliance and legal costs, adverse regulatory findings, or a need for further dilutive capital raises. A downward reset in government funding or a major data breach would quickly stress InnovAge’s ability to cover fixed costs and could force retrenchment.
Operational, Regulatory, and Financial Developments That Could Shift InnovAge’s Trajectory
Quarterly revenue growth rates relative to peer government-funded healthcare providers and industry benchmarks.
Trends in net income margin and evidence of operating leverage as member volume increases, if disclosed.
Updates to Medicare, Medicaid, or PACE reimbursement rates, eligibility criteria, or regulatory requirements.
Incidence and severity of regulatory actions, investigations, or enforcement settlements disclosed by the company.
Utilization of proceeds from the secondary offering: whether funds are allocated to growth initiatives, compliance infrastructure, or used to shore up liquidity.
Frequency and impact of data privacy or security incidents, including breaches of PHI or PII.
Changes in patient/member retention rates and satisfaction scores, if disclosed, as proxies for service quality and competitive position.
Any material changes in the mix of government payor programs or geographic expansion/contraction.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments