
CapsoVision: AI-Powered Capsule Endoscopy Confronts Expansion, Regulation, and Financial Viability
CapsoVision’s FDA-cleared CapsoCam Plus and recent AI Highlights tool mark progress in GI diagnostics, but the company’s future hinges on successful commercialization of next-generation colon capsules, regulatory wins, and overcoming persistent operating losses.
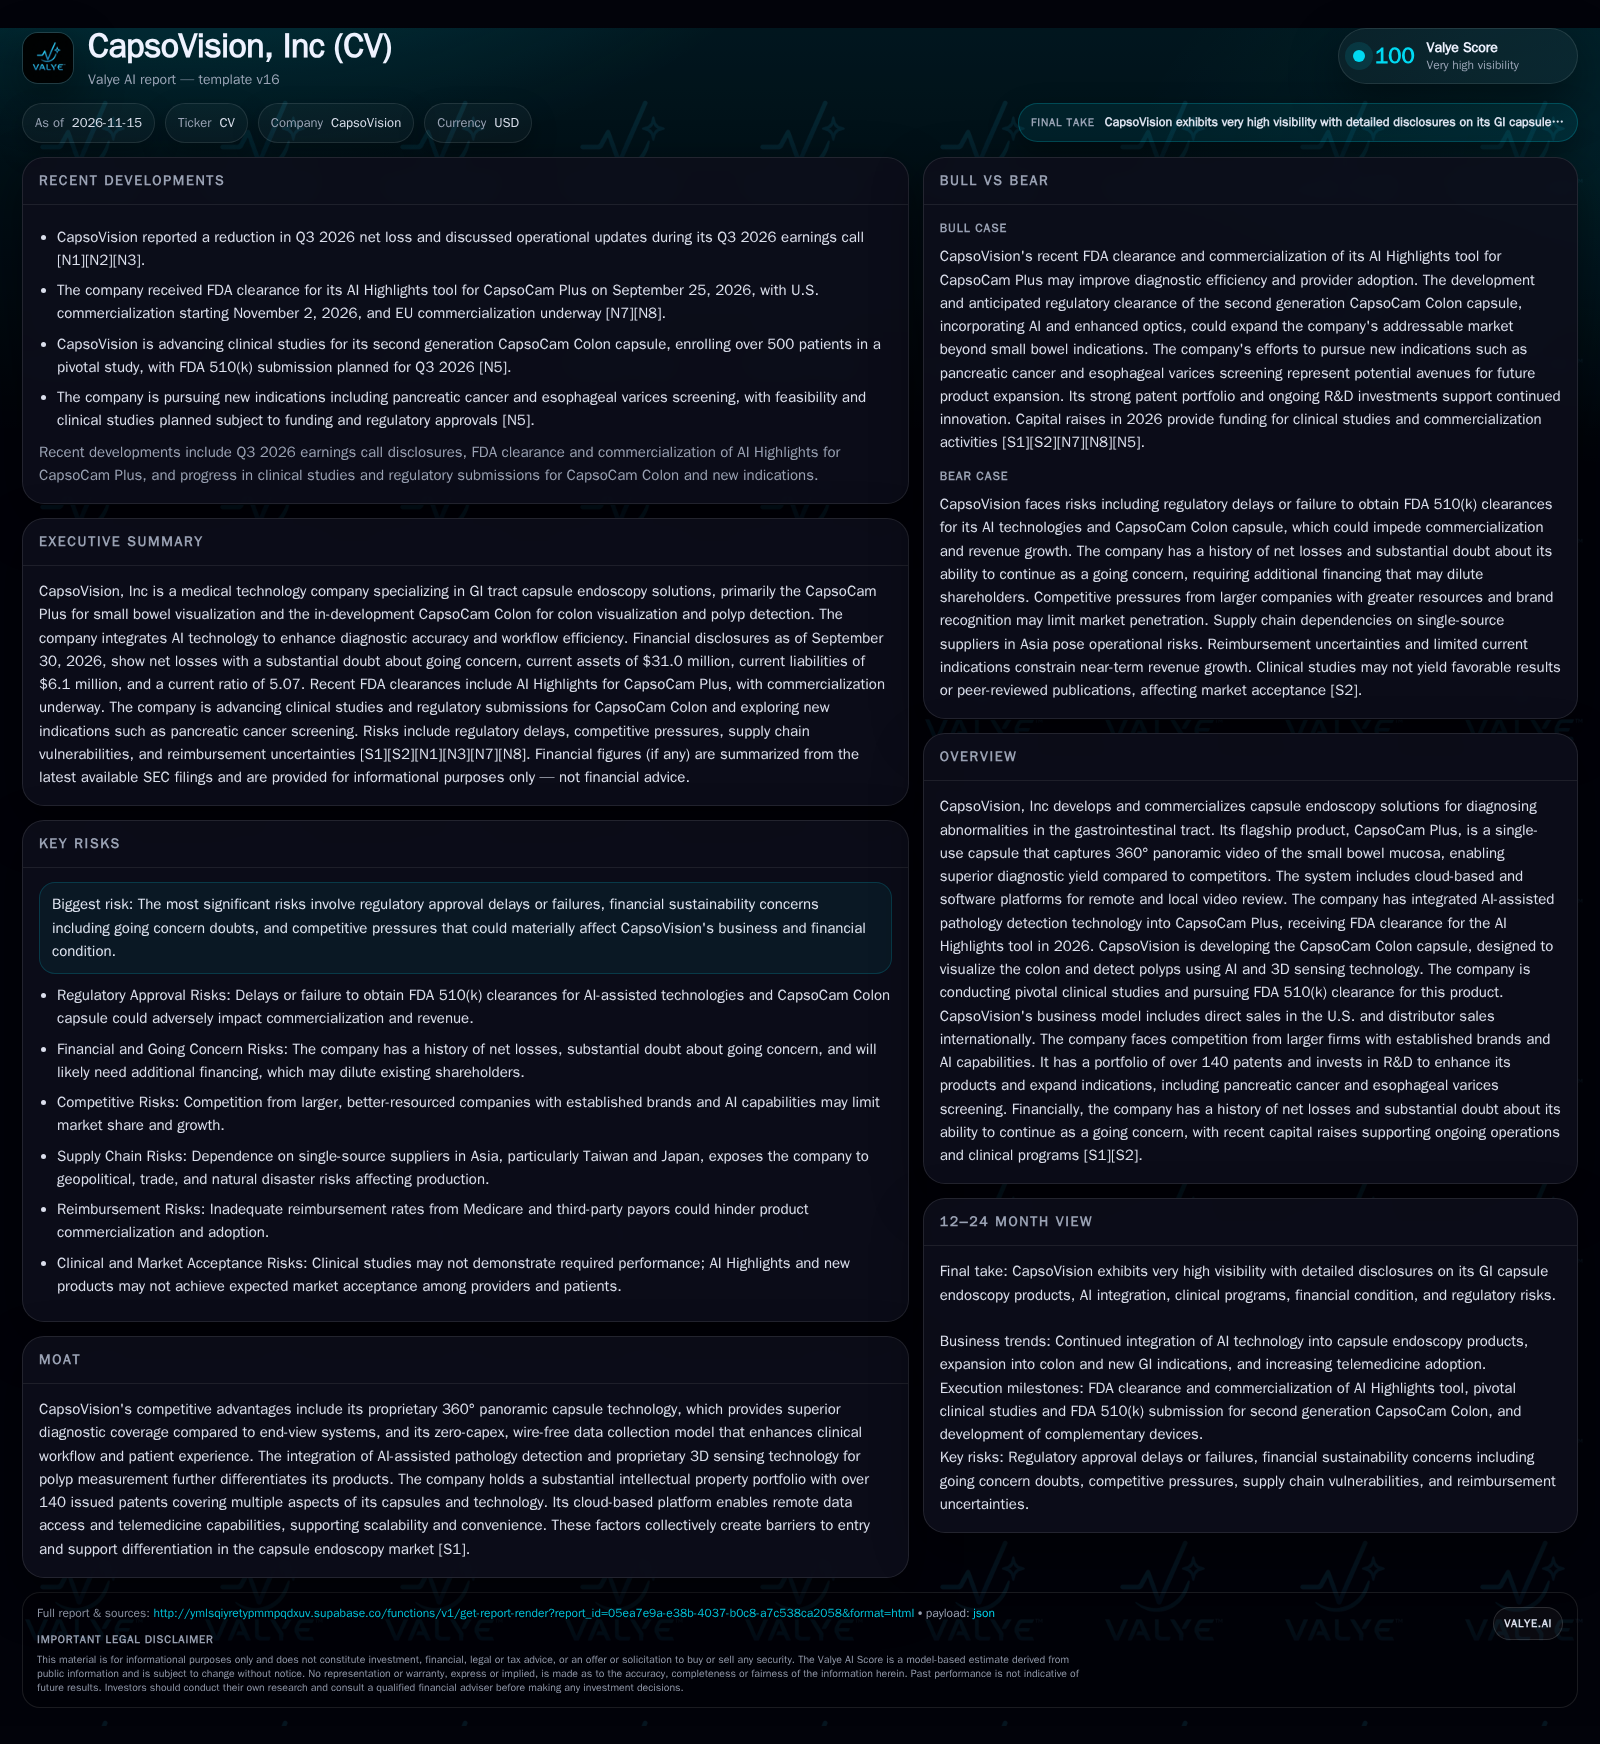
CapsoVision is commercializing its 360° panoramic CapsoCam Plus capsule endoscopy system, with 2025 revenue growth driven by increased capsule sales. The recent FDA clearance for its AI Highlights tool and ongoing development of a colon-targeted capsule represent the next phase, but continued net losses, going-concern warnings, and dependence on future regulatory approvals create a high-stakes environment. Expansion into new GI indications and successful AI integration could unlock broader market potential if clinical and commercial milestones are achieved. [S1] [S2] [N7] [N8]
CapsoVision, Inc. stands at a crossroads as it seeks to expand beyond its established CapsoCam Plus small bowel capsule endoscopy platform. With over 161,000 patients treated and a recent 15% revenue uptick, the company is pushing into AI-powered diagnostics and colon visualization—critical markets for non-invasive GI screening. However, material net losses, persistent questions around financial sustainability, and the high bar for regulatory and clinical validation of its next-generation products mean the company’s future will be dictated by its ability to convert technical progress into commercial traction and sustained funding. The next 18 months are likely to prove pivotal.
CapsoVision’s Latest Advances Amid Ongoing Industry Challenges
CapsoVision’s CapsoCam Plus capsule endoscopy system generated $13.6 million in revenue for 2025, up 15% from 2024, reflecting increased sales volume and suggesting growing clinical adoption for small bowel visualization. The company has now treated over 161,000 patients as of December 2025, pointing to a meaningful installed base and operational scale. In September 2026, the FDA cleared CapsoVision’s AI Highlights tool for CapsoCam Plus, enabling automated pathology detection and workflow optimization, with U.S. commercialization commencing in November and EU rollout underway. [S1] [N7] [N8]
Despite these advances, CapsoVision reported a net loss of $7.3 million for Q3 2026 and an accumulated deficit of $177.5 million as of September 30, 2026. The company raised $33.8 million through multiple equity offerings in 2026, but its disclosures continue to cite substantial doubt about its ability to continue as a going concern, highlighting the urgency of translating pipeline milestones into revenue and margin expansion. [S2]
Scaling Potential and Constraints of CapsoVision’s Capsule Technology
CapsoVision’s commercial model is anchored in single-use CapsoCam Plus capsule sales, augmented by cloud-based software (CapsoCloud) and desktop review tools (CapsoView). Revenue is fundamentally tied to procedure volume, as each diagnostic event consumes a new capsule, creating a direct link between clinical adoption and top-line growth. The zero-capex, wire-free model removes the need for capital equipment, potentially lowering adoption friction for providers and facilitating telemedicine use cases. However, the degree of pricing power is likely limited by reimbursement rates and competition from larger players with established provider relationships.
Operating leverage is plausible if volume grows, as R&D, regulatory, and fixed overhead costs are spread over more units, but the company’s persistent net losses highlight a cost structure that remains ahead of current revenue scale. The business is capital-intensive, with ongoing R&D for new indications (colon, pancreas, esophagus) and the need to fund clinical trials and regulatory submissions. The absence of recurring software or service revenue at scale means margins are likely dominated by hardware economics and manufacturing efficiency, though future expansion into AI-driven diagnostics and remote monitoring could improve mix if successfully commercialized.
Positioning Within the Competitive Gastrointestinal Diagnostics Landscape
CapsoVision’s primary competitive edge is its 360° panoramic imaging, which offers superior mucosal visualization compared to traditional end-view capsules. Its zero-capex, wire-free system and cloud-enabled workflow create potential workflow and patient-experience advantages. The recent FDA clearance of the AI Highlights tool further differentiates the platform by promising workflow efficiency and diagnostic support for clinicians.
However, CapsoVision competes against larger GI device manufacturers and diagnostics firms—many with deeper commercial infrastructure, broader portfolios, and growing AI capabilities. These incumbents can leverage bundled sales, established reimbursement pathways, and brand recognition to defend share and pressure pricing. Substitution risk is also present from emerging endoscopic techniques, non-capsule imaging solutions, and future advances in AI-enabled diagnostics. The company's 140+ issued patents provide some IP protection, but market share gains will likely require not just technical superiority but also clear clinical and economic benefits that drive payer and provider adoption.
Regulatory Successes and Indication Growth as Value Catalysts
A favorable scenario for CapsoVision would see the CapsoCam Colon capsule achieve FDA 510(k) clearance following the ongoing pivotal study, validating its AI and 3D polyp measurement capabilities. This would open the door to U.S. commercialization for colon visualization and polyp detection—potentially a much larger market than small bowel diagnostics, especially for patients unable to undergo standard colonoscopy. If regulatory approvals are achieved on schedule and clinical data are compelling, the company could drive rapid adoption among GI practices and health systems seeking less invasive, telemedicine-compatible screening solutions.
Further upside could come from successful expansion into new indications such as pancreatic cancer and esophageal varices screening, leveraging the core platform’s flexibility and AI integration. Confirmation of this scenario would require positive pivotal study results, timely FDA clearances, favorable reimbursement decisions, and early signs of strong provider uptake and recurring order growth in new indications. Evidence of operating leverage—such as margin expansion on rising volumes—would further support the bull case.
Balancing Steady Growth with Financial and Regulatory Complexities
The most plausible near-term trajectory is continued growth in CapsoCam Plus sales as the company capitalizes on expanded indications (such as pediatric use and telemedicine) and recently cleared AI tools. However, CapsoCam Colon-related revenue is unlikely before late 2027, given the regulatory timeline. Ongoing net losses are expected as the company funds R&D, clinical trials, and commercial readiness for the colon and future pipeline products.
Incremental adoption is likely to depend on demonstrating clear workflow and diagnostic benefits relative to competitors, obtaining favorable reimbursement, and overcoming inertia among providers. The company will probably need additional capital to sustain operations through the next phase of product launches. This scenario would be confirmed by steady, if moderate, year-over-year revenue growth, continued clinical progress, and manageable dilution from future financings. It would be challenged if clinical data disappoints, regulatory timelines slip, or competitive offerings erode CapsoVision’s market share.
Risks from Regulatory Delays, Clinical Outcomes, and Funding Shortfalls
A negative outcome could unfold if CapsoVision fails to secure FDA clearance for CapsoCam Colon or its AI technologies, whether due to insufficient clinical data, regulatory pushback, or unforeseen safety/performance issues. This would restrict the company to its current small bowel indication, capping addressable market and stalling revenue growth. Adverse reimbursement decisions or inability to demonstrate cost-effectiveness versus competitors could further limit adoption.
On the financial front, persistent net losses and delayed product milestones would force reliance on dilutive financings or, in the worst case, raise existential questions if capital markets tighten or investor support wanes. Supply chain disruption—given dependence on single-source suppliers in Asia—could add operational volatility. Downside confirmation would come from missed regulatory timelines, disappointing clinical results, declining sales, or worsening going-concern disclosures.
Key Developments Shaping CapsoVision’s Long-Term Business Prospects
Quarterly CapsoCam Plus sales volume and revenue growth, particularly in new segments such as pediatric and telemedicine use, would provide a direct measure of adoption momentum if disclosed.
Progress in the pivotal clinical study for CapsoCam Colon, including enrollment rates, interim data quality, and peer-reviewed publication of results, will be crucial to support regulatory submissions.
FDA 510(k) submission timing and clearance outcome for CapsoCam Colon and its AI/3D features—any delay or negative feedback could materially alter the outlook.
Updates on reimbursement coverage and payment rates for both existing and new indications, as these will determine provider economics and adoption pace.
Operating expense trends relative to revenue growth, especially as AI tools and new capsules move toward commercialization, will signal whether operating leverage is achievable.
Disclosures on additional capital raises, burn rate, and going-concern language will clarify the company’s financial runway and dilution risk.
Supply chain stability, especially regarding key suppliers in Asia—any reported disruptions or cost increases could impact gross margins and delivery timelines.
Early customer feedback and adoption rates for the AI Highlights tool and any future AI-enabled products, if disclosed, would help test the thesis around workflow and diagnostic differentiation.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments