
Charlotte’s Web Holdings: Expanding Botanical Wellness Ambitions Confront Regulatory, Profitability, and Brand Inflection Points
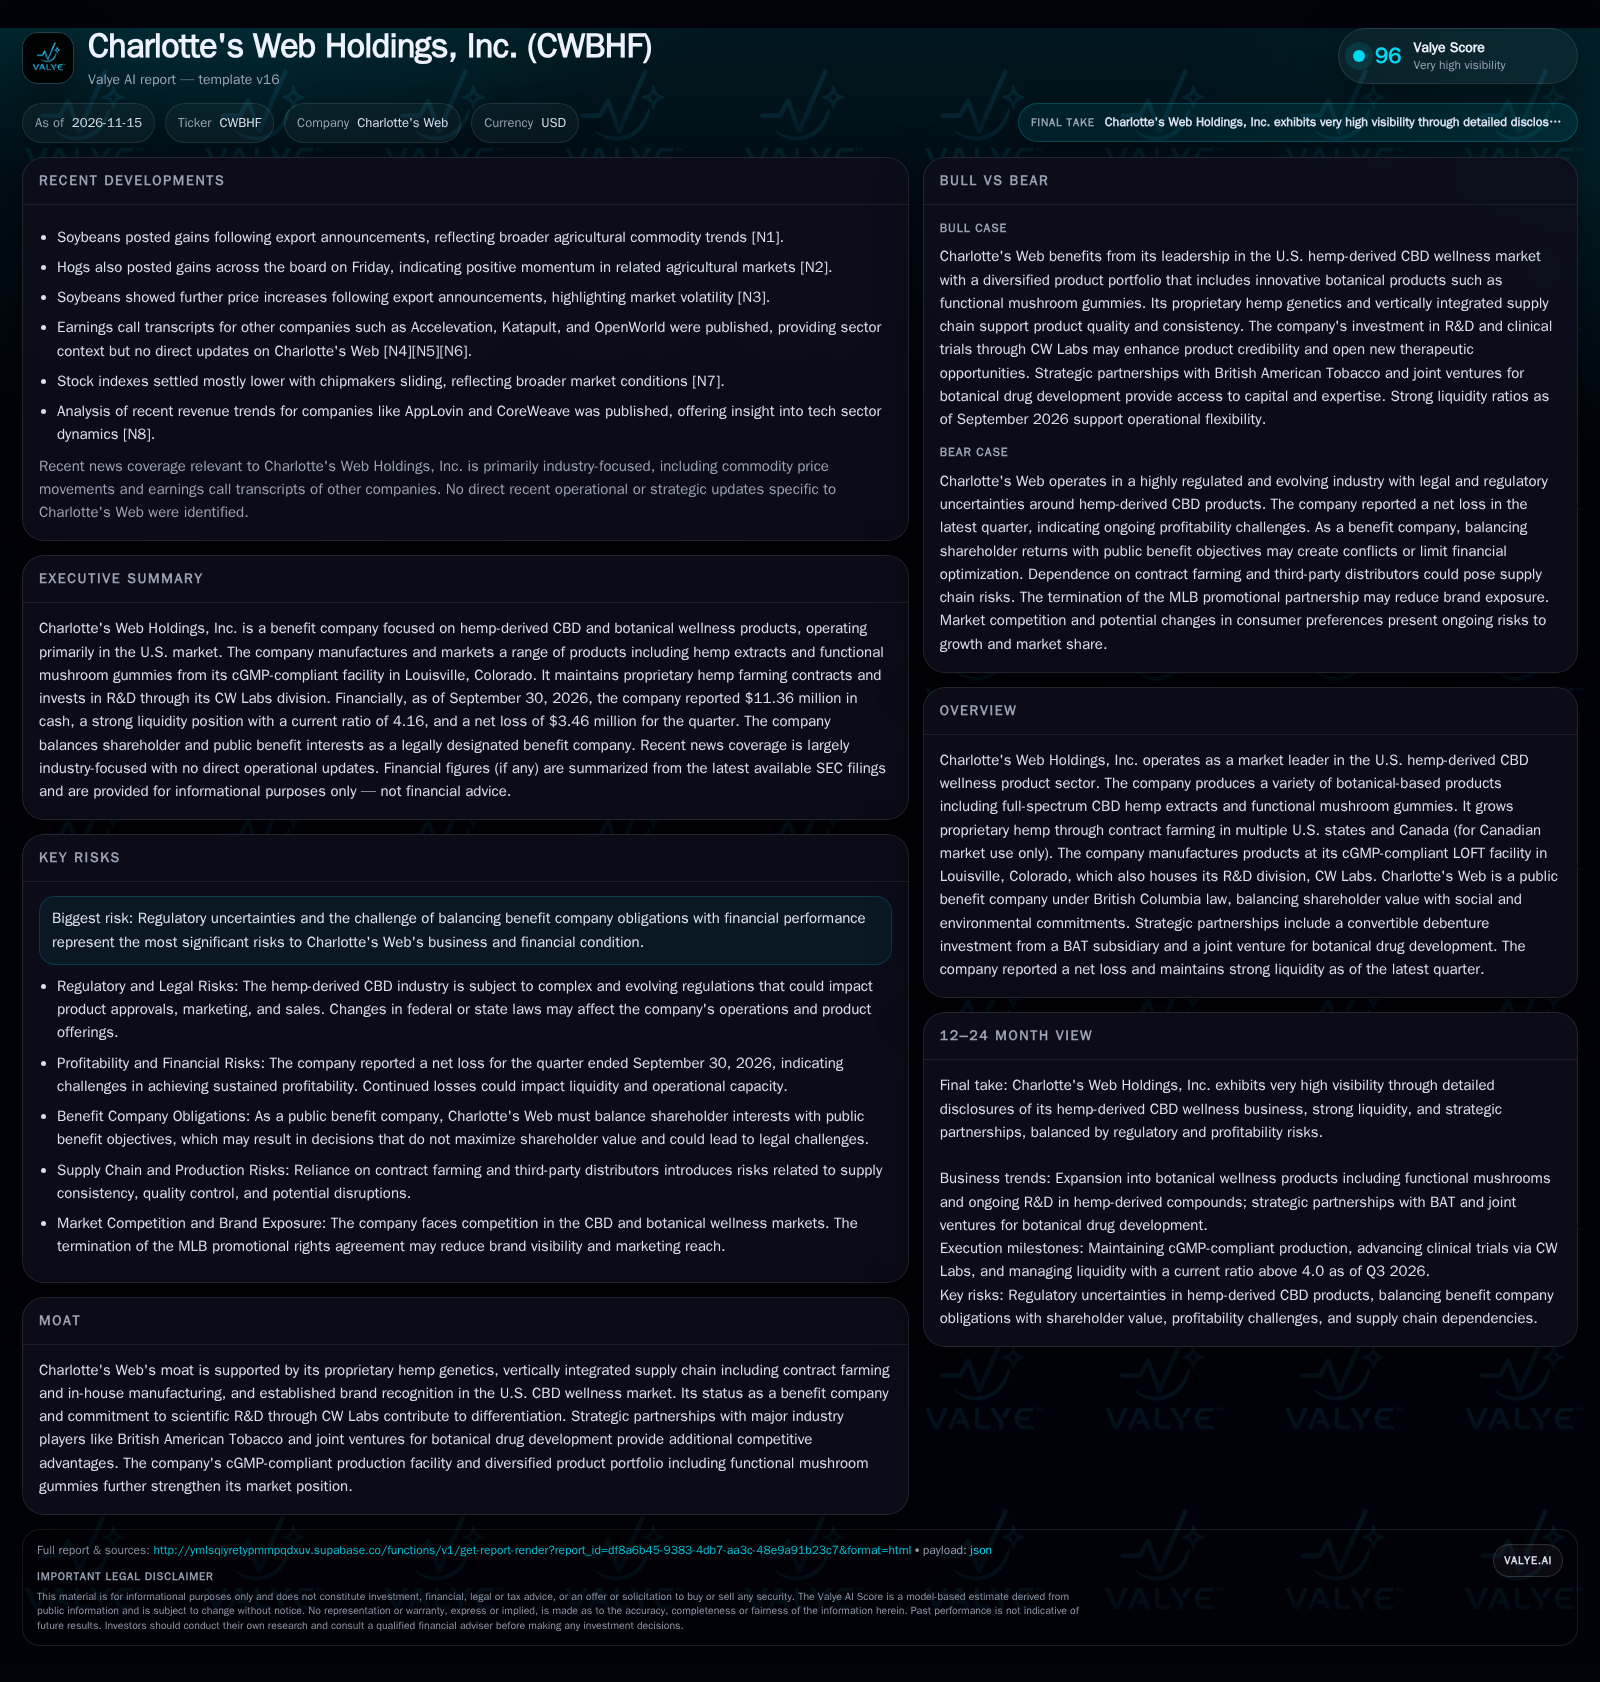
Charlotte’s Web Holdings, a leading U.S. hemp-derived CBD wellness brand, is navigating a transitional period marked by product diversification, ongoing net losses, and the loss of a major promotional partnership. The company’s reported liquidity position and strategic alliances provide optionality, but regulatory uncertainty and evolving industry dynamics keep the path to sustainable profitability complex and contingent.
Charlotte’s Web Holdings is leveraging its established CBD brand, proprietary hemp genetics, and vertical integration to expand into new botanical wellness categories such as functional mushrooms. The outlook hinges on Charlotte’s Web’s ability to convert innovation and operational discipline into consistent profitability amid a shifting legal landscape.[S1] [S2]
Charlotte’s Web Holdings, Inc., long a bellwether in the U.S. CBD wellness sector, is at a strategic crossroads. The company’s move to diversify beyond hemp-derived products, coupled with disciplined supply chain management and high-profile partnerships, underscores its ambition to remain relevant as the regulatory and consumer environment evolves. Yet, persistent net losses, the end of a marquee sports partnership, and the inherent volatility of the cannabinoid and broader botanical wellness markets frame a period of heightened execution risk. Investors and industry observers must weigh the company’s liquidity and innovation pipeline against profit headwinds and regulatory crosscurrents.
Recent Financials and Strategic Shifts Redefine Charlotte’s Web’s Near-Term Landscape
As of September 30, 2026, Charlotte’s Web reported a net loss of $3.46 million for the quarter and maintained cash and equivalents of $11.36 million, with a current ratio of 4.16 and a cash ratio of 1.51.[S2] This substantiates a high degree of near-term liquidity, even as profit remains elusive. The company’s revenue base continues to be dominated by hemp-derived CBD wellness products, but the September 2024 launch of a functional mushroom gummy line marks a deliberate move to diversify beyond hemp. Notably, Charlotte’s Web’s exclusive partnership with Major League Baseball ended in 2025, with the company receiving a waiver of remaining fees—a development that could reduce mainstream brand exposure but may also free up marketing resources.[S1] Strategic partnerships with British American Tobacco (via a convertible debenture) and a joint venture for botanical drug development continue, providing capital and optionality for product and channel innovation.
How Charlotte’s Web’s Vertically Integrated Model and Product Mix Influence Economics
Charlotte’s Web’s business model centers on proprietary hemp genetics, contract farming, and in-house cGMP-compliant manufacturing. This vertical integration can theoretically yield cost control and quality assurance advantages, especially in a commoditizing CBD market. The product portfolio is broad: full-spectrum hemp extracts, topicals, capsules, tinctures, and, since late 2024, functional mushroom gummies. Revenue mix is still heavily weighted to CBD, but the addition of non-hemp botanicals could offer margin diversification if the company can leverage existing distribution and branding.
The capital intensity of the business is moderate: proprietary genetics and contract farming limit the need for direct agricultural asset ownership, while the LOFT facility consolidates production, R&D, and quality control. Operating leverage is plausible as volumes scale, but persistent net losses suggest that fixed costs (including R&D via CW Labs, compliance, and marketing) still outpace gross profit. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2]
Pricing power in CBD has been under pressure industry-wide, driven by oversupply and regulatory ambiguity. Charlotte’s Web’s ability to command a premium may rest on brand equity, clinical validation, and differentiation via proprietary formulations or new categories like functional mushrooms. The economics of the mushroom segment are not yet established; success will depend on consumer adoption, regulatory clarity, and the cost structure relative to CBD products.
Brand Strength, Supply Chain Control, and Partnerships Shape Charlotte’s Web’s Defenses—But New Threats Emerge
Charlotte’s Web has historically enjoyed strong brand recognition and a reputation for quality in the U.S. CBD market, aided by its proprietary genetics, cGMP production, and broad retail footprint. Its vertically integrated approach can help mitigate some supply chain volatility, and the company’s status as a public benefit corporation is a point of differentiation for value-driven consumers.
However, the competitive landscape is fluid. The commoditization of CBD, proliferation of new entrants, and the encroachment of large CPG and wellness brands increase pricing and shelf-space pressure. The termination of the MLB partnership removes a high-visibility channel, potentially eroding a unique brand advantage. The company’s new functional mushroom products face established competitors in the broader adaptogen and supplement space, where brand loyalty and regulatory landscapes differ from CBD.
Strategic relationships with British American Tobacco and AJNA BioSciences provide access to capital, regulatory expertise, and potential future distribution or drug-development channels, but the benefits are contingent on execution and regulatory developments. The question is whether Charlotte’s Web can translate its legacy in CBD into durable advantages as consumer preferences and legal frameworks evolve.
If Botanical Diversification and Clinical Validation Drive New Growth, Profitability Could Inflect
A favorable scenario would see Charlotte’s Web successfully leveraging its R&D (via CW Labs) and strategic partnerships to launch differentiated, clinically substantiated products across both CBD and non-hemp botanical categories. If functional mushroom gummies and future offerings resonate with consumers—supported by credible clinical data and robust marketing—the company could regain top-line momentum and justify premium pricing.
Evidence confirming this scenario would include sustained revenue growth in new product categories, improved gross margins as scale and product mix shift, and clear market share gains relative to both traditional CBD competitors and new botanical wellness entrants. Positive clinical trial readouts, expanded distribution agreements, and new or renewed high-profile partnerships would further validate the thesis. A return to profitability or narrowing net losses, especially as fixed costs are leveraged, would be a concrete inflection point.
A Mixed Transition: Incremental Growth, Margin Pressure, and Regulatory Flux Persist
The most plausible near-term scenario is that Charlotte’s Web continues to experience modest growth in its legacy CBD portfolio, with new product categories like functional mushrooms contributing, but not transforming, the revenue base. Competitive intensity and regulatory ambiguity are likely to keep pricing and margins under pressure.
Confirmation of this scenario would be a relatively flat or single-digit top-line trajectory, stable or slightly improving gross margins, and continued but manageable net losses. Regulatory developments—such as incremental FDA guidance or state-level rule changes—could create both headwinds and tailwinds but are unlikely to resolve decisively in the near term. Evidence to the contrary would include a major regulatory breakthrough, a significant new partnership, or a sharp swing in profitability (positive or negative).
Profitability Remains Out of Reach as Regulatory and Brand Risks Compound
In a bearish scenario, Charlotte’s Web fails to gain meaningful traction with new product lines, while CBD category growth stagnates or declines due to competition, pricing pressure, or adverse regulatory actions. The loss of the MLB partnership could accelerate brand erosion, making customer acquisition more expensive and less efficient.
If net losses widen and cash burn accelerates, the company could face the prospect of dilutive financing or cost-cutting that undermines R&D and long-term positioning. Evidence would include declining sales, shrinking margins, deteriorating liquidity metrics, or material negative regulatory developments (such as product bans, labeling restrictions, or adverse clinical findings). Failure to renew or replace high-profile partnerships, or the loss of strategic support from key investors, would further confirm downside risks.
What Will Determine Charlotte’s Web’s Next Chapter in Botanical Wellness
Quarterly revenue by product category—including functional mushroom gummies—if disclosed, would clarify the impact of diversification.
Gross margin progression and cost discipline, particularly as product mix shifts, will be critical to monitoring operating leverage.
Updates on clinical trial outcomes or published studies from CW Labs would help validate product claims and pricing power.
Announcements of new or renewed high-profile partnerships could offset the loss of MLB and support brand visibility.
Any material regulatory events—positive or negative—at the federal or state level should be tracked for their impact on sales channels and compliance costs.
Trends in marketing spend and customer acquisition costs would illuminate the efficiency of growth investments as the company pivots beyond CBD.
Liquidity and burn rate metrics should be monitored to assess the sustainability of operations if net losses continue.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments