
MeiraGTx: Clinical Progress, Manufacturing Scale, and the Stakes of Platform Validation
MeiraGTx is advancing late-stage gene therapy programs and pioneering riboswitch-controlled therapeutics, underpinned by proprietary GMP manufacturing and substantial partnerships. Yet, the company faces the capital intensity, regulatory hurdles, and commercial uncertainties typical of clinical-stage biotech — with near-term inflection points tied to clinical data, partner milestones, and the realization of platform economics.
MeiraGTx combines late-stage gene therapy assets, a novel riboswitch platform, and integrated manufacturing, with support from major pharma partners. Recent Q3 results highlight persistent losses and limited product revenue, despite reported liquidity position and new capital raised. The next phase hinges on clinical readouts, regulatory progress, and the translation of technology into commercial agreements or products.
MeiraGTx sits at a critical juncture for clinical-stage genetic medicine companies: it has established world-class GMP manufacturing facilities, secured high-profile partnerships, and advanced multiple late-stage clinical programs. Its proprietary riboswitch gene regulation platform could enable a new class of controllable gene therapies. However, the company’s Q3 2026 results—showing limited revenue and continued losses—underscore the challenges of translating platform innovation into sustainable economics. The next 12-24 months will test whether MeiraGTx can convert its technological and manufacturing strengths into value-creating clinical milestones, partner payments, and eventual commercial products.
Recent Milestones and Financial Realities Shape the Next Chapter
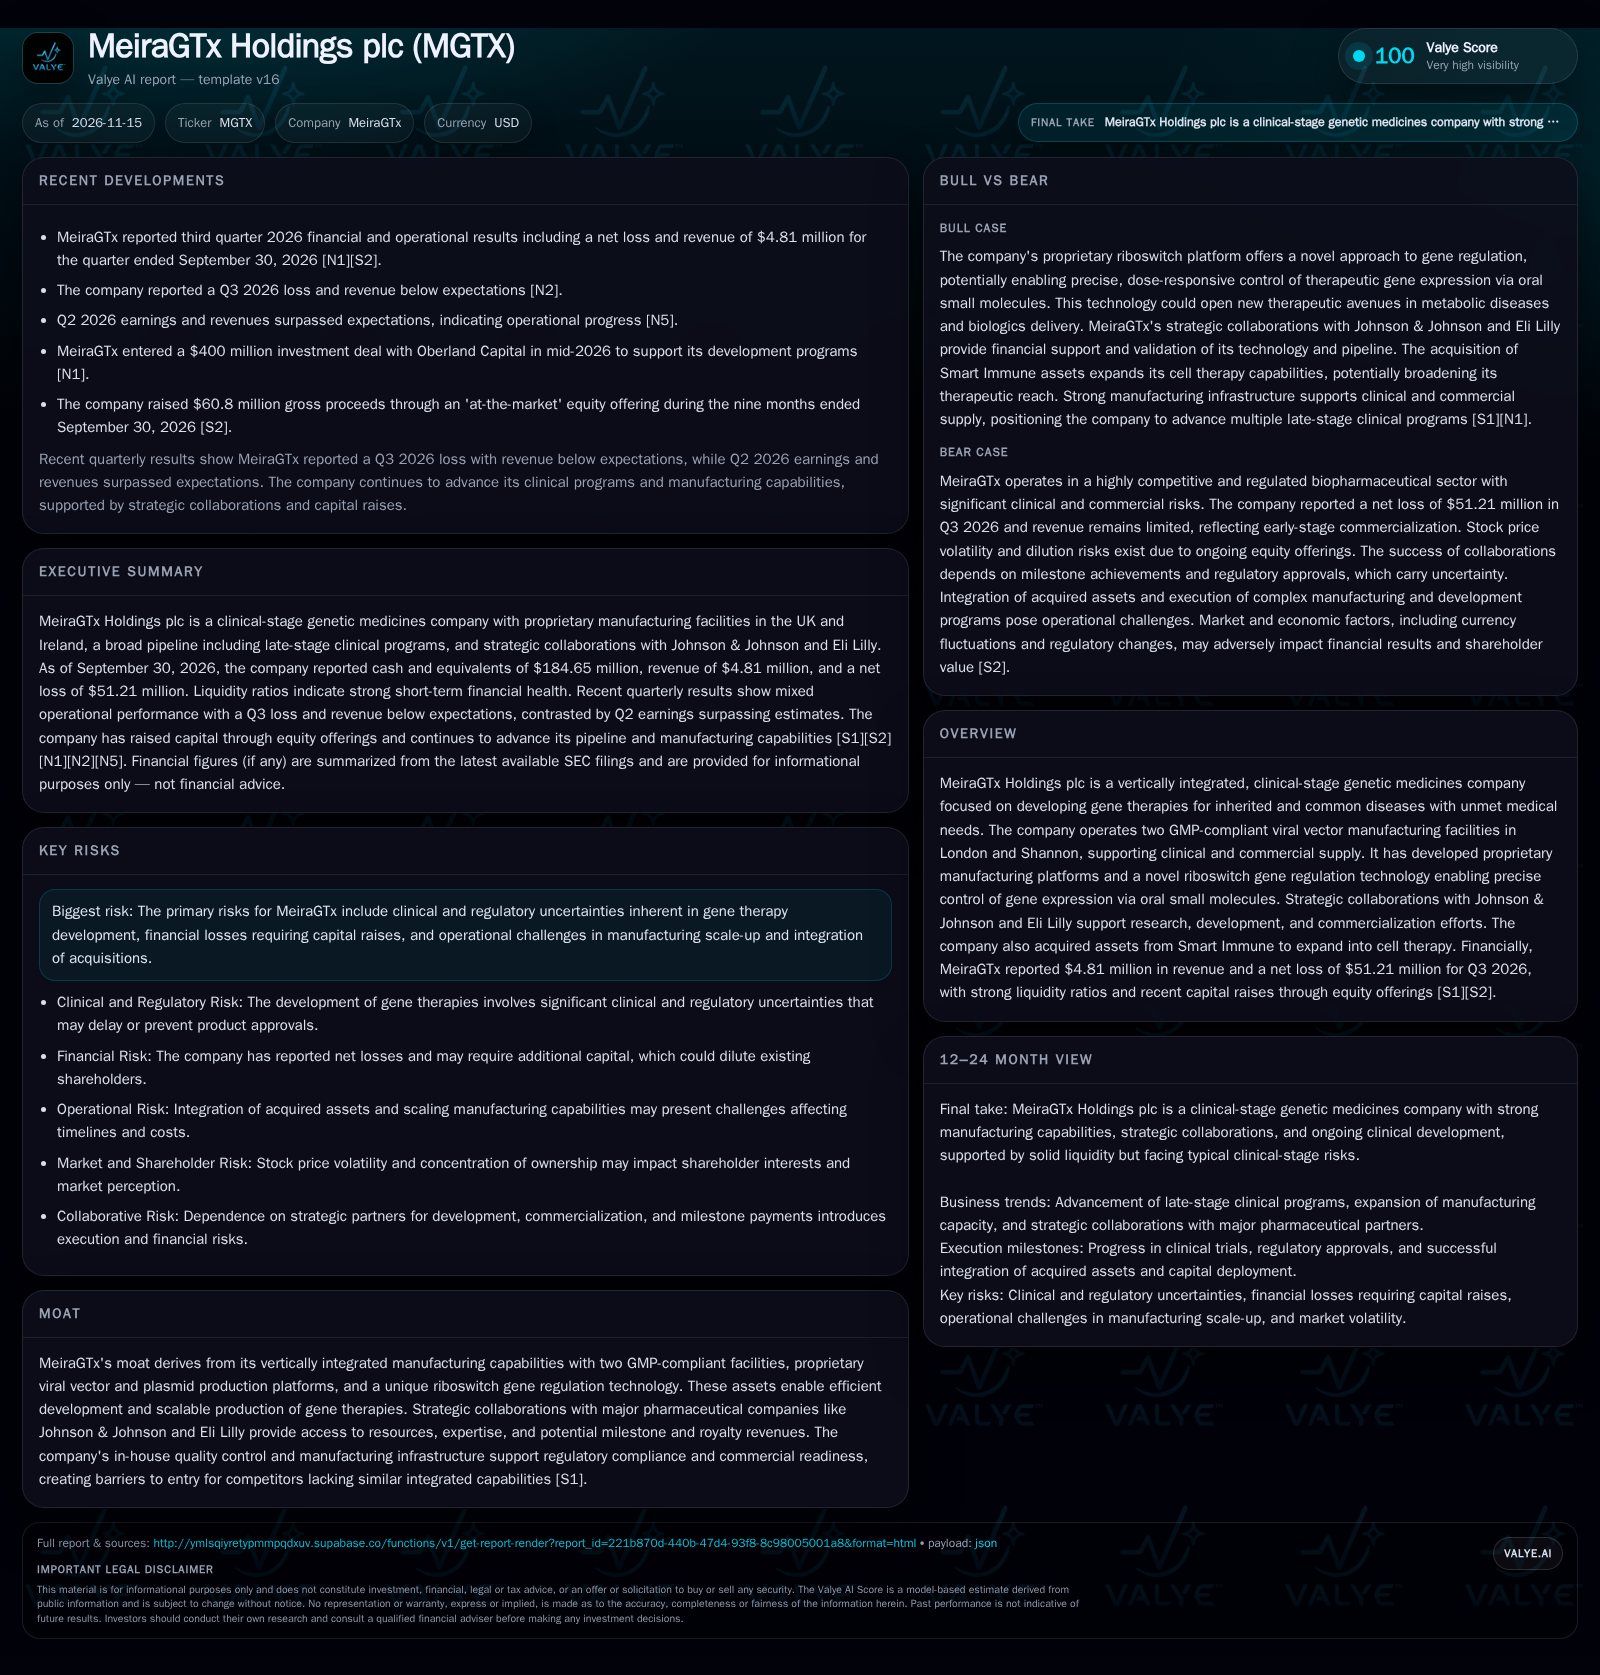
As of September 30, 2026, MeiraGTx reported $4.81 million in revenue and a net loss of $51.21 million for the quarter, with an EPS of -$0.53 [S2]. These results reflect the company’s ongoing transition from a research-oriented biotech to a potential commercial-stage player—operating at significant loss while advancing late-stage clinical programs. Liquidity ratios are strong (current ratio 4.62, cash ratio 3.52), supported by $184.65 million in cash and equivalents and $60.8 million in gross proceeds from recent at-the-market equity offerings [S2]. Capital generation has been augmented by partnership and asset sales, including a $65 million upfront payment (plus milestones) from Johnson & Johnson and up to $430 million in potential funding from a 2025 collaboration with Hologen [S1]. The company’s vertically integrated GMP manufacturing infrastructure is operational, with two facilities (London and Shannon) supporting both clinical and potential commercial supply [S1].
How MeiraGTx’s Platform and Partnerships Could Drive Future Economics
MeiraGTx’s business model is fundamentally anchored in proprietary R&D, platform licensing, and manufacturing. The company’s economics are currently dominated by R&D expenses, manufacturing scale-up costs, and the lumpy, milestone-driven revenue from collaborations and asset sales. With only $4.81 million in Q3 revenue and no recurring product sales, the company is not yet demonstrating commercial leverage [S2].
The economics could shift dramatically if one or more late-stage programs succeed: gene therapy launches typically command high per-patient prices, but face slow initial uptake, complex reimbursement, and concentrated payer scrutiny. The riboswitch platform, if validated, could open new modalities—enabling dose-titratable gene therapies and expanding addressable indications, potentially supporting both out-licensing and internal pipeline expansion.
Manufacturing is a key fixed-cost base but could yield high incremental margins if capacity is leveraged at scale. MeiraGTx’s GMP facilities (including an internally controlled plasmid production hub) suggest future cost-of-goods advantages and supply reliability. However, near-term economics remain dependent on external funding, milestone payments, and the timing of clinical/regulatory inflection points.
Differentiation in a Crowded Gene Therapy Landscape
MeiraGTx operates in a highly competitive gene therapy and genetic medicines market, where dozens of clinical-stage companies and established pharma are racing toward regulatory approvals. Its main points of differentiation are: a) a vertically integrated manufacturing platform, b) the riboswitch gene regulation technology enabling externally controlled gene expression, and c) strategic partnerships with major pharmaceutical companies (Johnson & Johnson, Eli Lilly, Hologen) [S1].
Integrated GMP manufacturing provides supply chain resilience and speed to clinic, which could be an advantage over less vertically integrated peers, especially in the context of regulatory scrutiny on viral vector quality. The riboswitch platform, if clinically validated, may offer a unique mechanism for programmable gene therapies—potentially reducing dose-limiting toxicities or enabling more precise, chronic disease management.
However, these advantages are conditional: competitors are investing heavily in their own manufacturing, gene regulation, and delivery technologies. The field is also exposed to rapid advances in non-viral technologies (e.g., mRNA, gene editing) that could erode the long-term exclusivity of viral vector approaches. MeiraGTx’s partnerships provide validation and access to non-dilutive funding but also introduce execution risk if milestones are not met.
Clinical Success and Platform Validation Unlock Transformational Value
A favorable outcome for MeiraGTx would require positive late-stage clinical results in at least one lead indication (e.g., radiation-induced xerostomia or Parkinson’s disease), enabling regulatory submission and approval. This could trigger milestone payments from partners, unlock additional development funding, and potentially enable the first product launches—converting fixed manufacturing capacity into high-margin product sales.
If the riboswitch platform demonstrates dose-responsive control and clinical benefit in trials, it could become a sought-after technology for both internal and partnered programs—spurring licensing revenue, new collaborations, and pipeline expansion. The company’s ability to manufacture at commercial scale would enable rapid product rollout and strengthen its negotiating position with payers and partners.
Evidence confirming this scenario would include positive pivotal trial readouts, regulatory filings and approvals, disclosure of new or expanded licensing agreements, and a material ramp in product or royalty revenue. Sustained partner engagement and additional non-dilutive funding would further validate the platform’s value.
Progression Through Clinical Milestones, Reliance on Partner Funding, and Gradual Validation
The most plausible path for MeiraGTx over the next 12-24 months involves continued advancement of its late-stage programs, periodic achievement of clinical milestones, and incremental validation of its technology platform. Revenue is likely to remain dominated by milestone and collaboration payments, with commercial product sales delayed until at least one program achieves regulatory approval and reimbursement.
Integration of acquired assets (e.g., Smart Immune’s CAR-T portfolio) could expand addressable indications but also introduce operational complexity.
Evidence supporting this scenario would include steady progress in clinical trial enrollment and data releases, additional partnership or licensing activity, and maintenance of a reported balance sheet position. Delays in clinical outcomes or regulatory review, or a lack of new commercial agreements, would challenge this trajectory.
Stalled Clinical Progress and Delayed Milestones Pressure the Model
In a negative scenario, MeiraGTx could encounter clinical setbacks—such as safety signals, lack of efficacy, or regulatory delays—in its lead programs. This would defer or foreclose milestone payments from partners, prolonging the period of cash burn and increasing dependence on dilutive equity financing or asset sales.
If the riboswitch platform fails to demonstrate sufficient clinical advantage or partner interest, the company’s differentiated positioning could erode, reducing the likelihood of new licensing or collaboration revenue. Operational challenges in scaling manufacturing or integrating acquired assets could further strain resources.
Confirmation of this downside would come from negative or inconclusive clinical trial results, withdrawal or downsizing of partner collaborations, missed or delayed milestone payments, and repeated equity offerings that dilute existing shareholders. Persistent net losses without a clear path to product revenue would raise questions about long-term sustainability.
What Will Determine Whether MeiraGTx Converts Platform Promise Into Durable Value?
Pivotal clinical trial outcomes in lead indications such as radiation-induced xerostomia and Parkinson’s disease—timing, results, and regulatory submissions.
Progress and disclosures regarding the clinical validation of the riboswitch platform, including dose-control data and external interest (if disclosed).
Magnitude and timing of milestone and royalty payments from existing partnerships (Johnson & Johnson, Eli Lilly, Hologen)—actual cash inflows versus projected.
New or expanded collaboration and licensing agreements, particularly those that provide non-dilutive funding or expand the scope of the riboswitch platform.
Ramp in product, royalty, or manufacturing revenue beyond milestone payments—a useful metric would be the initiation of commercial supply agreements (if disclosed).
Integration milestones and pipeline progress for acquired cell therapy assets from Smart Immune—evidence of operational and clinical advancement.
Frequency and terms of additional capital raises—especially if operating cash burn exceeds expectations or milestone payments are delayed.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments