
Definium Therapeutics: Clinical Momentum, Psychedelic Innovation, and the Challenge of Converting Promise to Product
Definium Therapeutics advances late-stage clinical trials for its proprietary psychedelic-based therapies, with reported liquidity position and regulatory tailwinds. The company’s future now hinges on pivotal Phase 3 data, commercial execution, and the durability of its competitive edge in a rapidly evolving neuropsychiatric market.
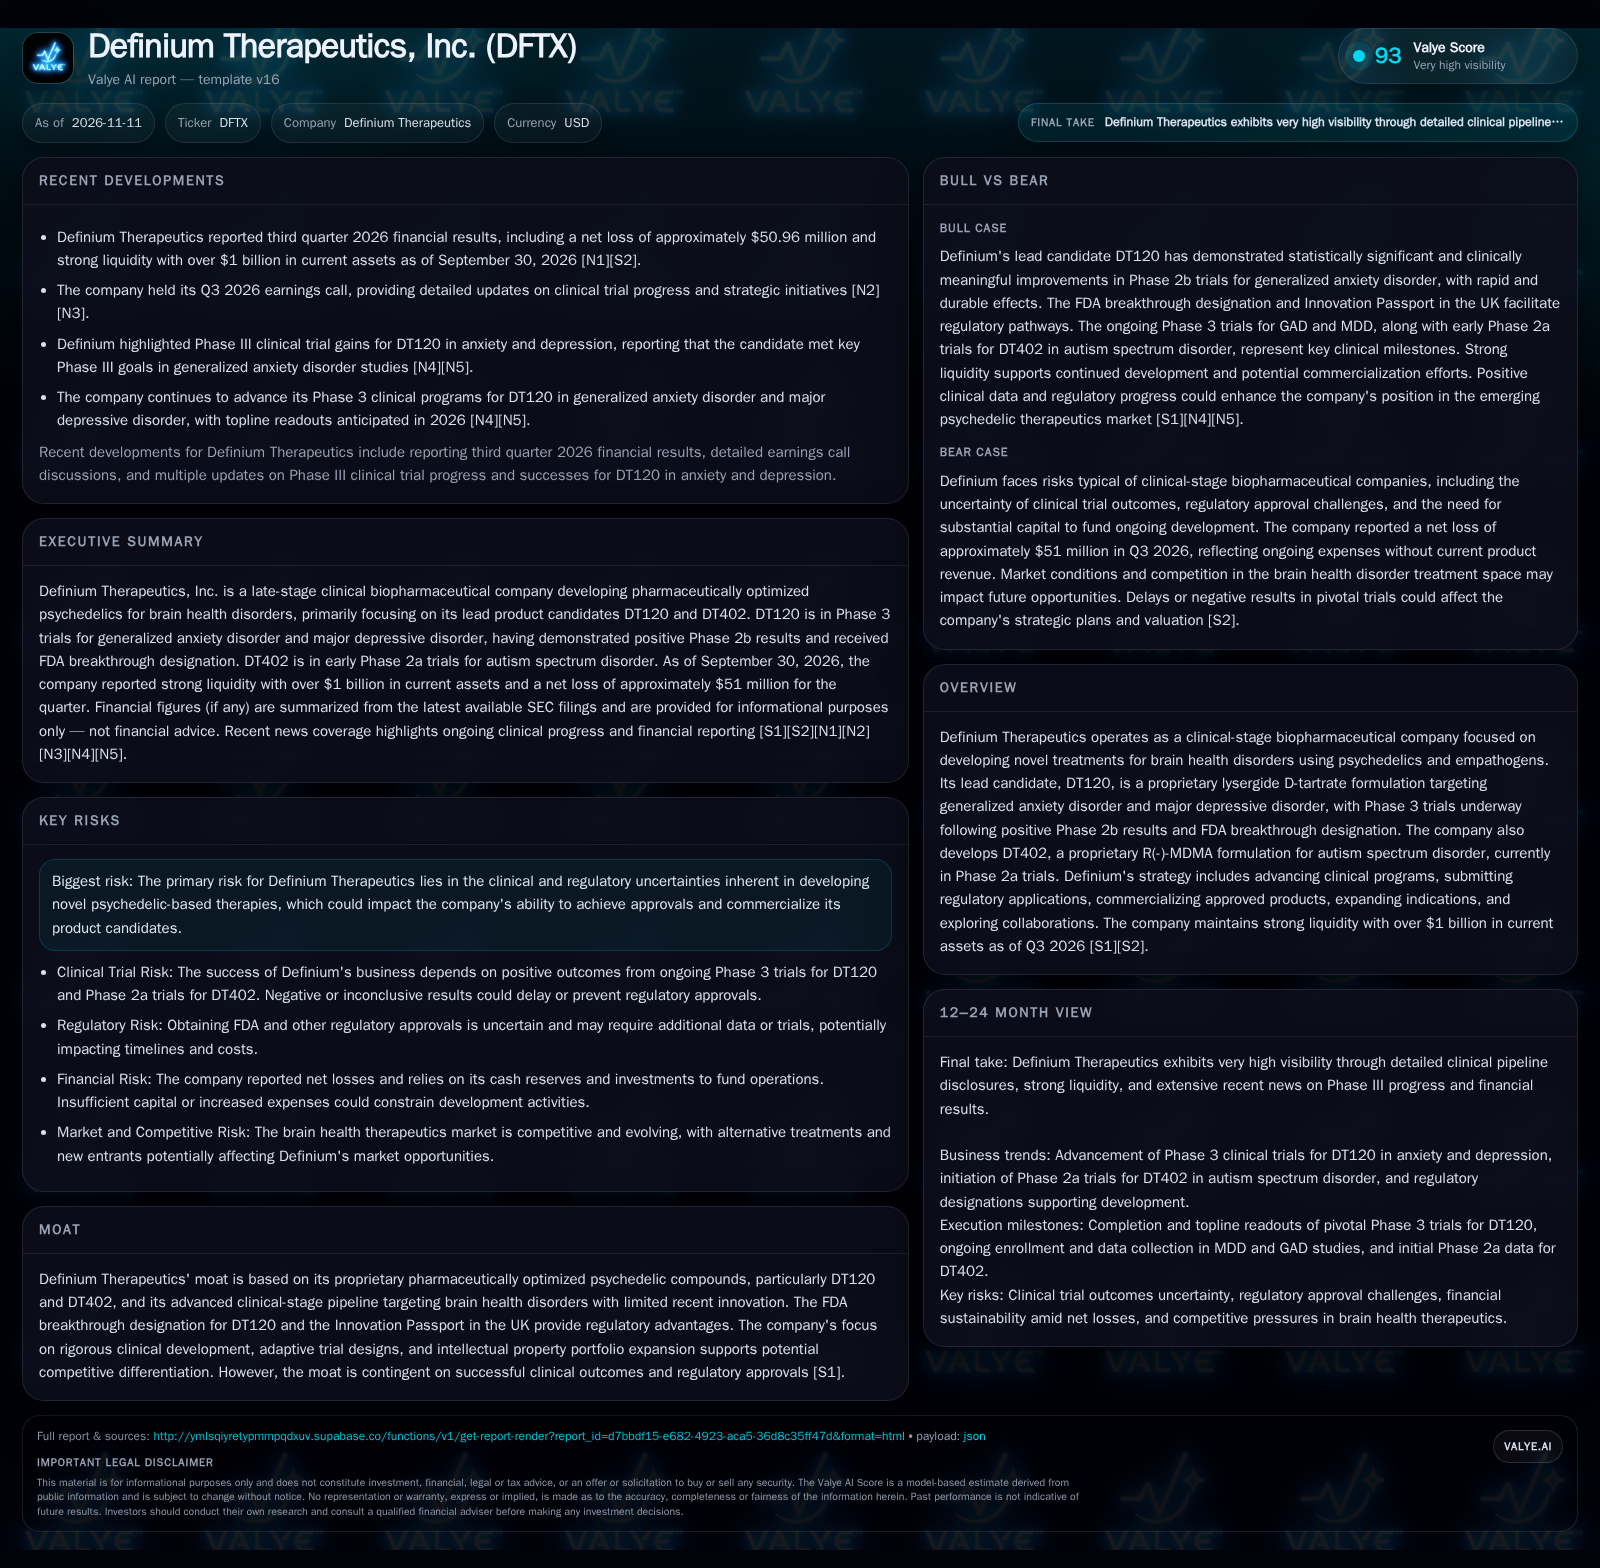
Definium Therapeutics is pursuing FDA approval for its lead psychedelic therapy DT120, which has demonstrated significant Phase 2b and early Phase 3 efficacy in generalized anxiety disorder. [S1] [S2] [N4] [N5]
Definium Therapeutics stands at a pivotal crossroads in the neuropsychiatric drug development landscape. With its lead psychedelic-derived therapy DT120 advancing through late-stage clinical trials and receiving regulatory designations that could accelerate market entry, the company is well-capitalized to drive toward commercialization. Yet, as with all clinical-stage biotechs, Definium’s fate is tightly linked to the outcome of upcoming pivotal trial readouts and its ability to overcome regulatory, competitive, and market-access hurdles. The next 12–24 months will be decisive in determining whether Definium can transition from clinical promise to a sustainable commercial business.
Definium’s Clinical and Financial Milestones Set the Stage for a High-Stakes 2026
Definium Therapeutics is progressing its lead candidate, DT120, through Phase 3 clinical trials for generalized anxiety disorder (GAD) and major depressive disorder (MDD), following statistically significant and clinically meaningful results in Phase 2b and early Phase 3 studies. The company received FDA breakthrough therapy designation for DT120 in GAD, which may expedite regulatory review and could provide a faster route to approval if pivotal data are positive. A second candidate, DT402, is in Phase 2a trials for autism spectrum disorder, signaling pipeline breadth.
Financially, as of September 30, 2026, Definium reported $241.15 million in cash and $805.7 million in short-term investments, totaling over $1 billion in current assets versus $67.73 million in current liabilities. This results in a current ratio of 15.53 and a cash ratio of 15.46, reflecting reported liquidity position. However, the company posted a net loss of $50.96 million for Q3 2026, underlining the ongoing cost of late-stage clinical development in the absence of revenue. [S1] [S2] [N1] [N4] [N5]
How Psychedelic Drug Development Could Translate Into Commercial Value
Definium’s business model is predicated on successfully developing and commercializing novel psychedelic-based therapies for neuropsychiatric conditions with high unmet need. If DT120 is approved, the company could generate revenue through direct sales, specialty distribution, or partnerships with larger pharmaceutical companies. Pricing power for first-in-class or best-in-class psychiatric therapies—especially those with rapid onset and durable efficacy, as suggested by DT120’s Phase 2b results—can be substantial, particularly in indications like GAD and MDD where treatment-resistant populations drive premium pricing.
The economics of psychedelic therapies may differ from traditional chronic oral medications. If DT120 is administered episodically (as acute intervention or periodic dosing), revenue will depend on per-treatment pricing, adoption rates among prescribers, and reimbursement dynamics. Payer acceptance will hinge on demonstrated clinical benefit, cost-offsets (e.g., reduced chronic medication use or hospitalizations), and safety/tolerability profile. Operating leverage could be high if fixed R&D and SG&A costs are amortized over a large patient base, but this depends on regulatory approval, speed of uptake, and competitive intensity.
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. The ability to secure partnerships or licensing deals could mitigate this risk but would also dilute economics.
Definium’s Moat: Proprietary Compounds, Regulatory Head Start, and the Race Against Rivals
Definium’s proprietary formulation of lysergide (DT120) and R(-)-MDMA (DT402) give it a differentiated scientific and intellectual property position in a field where few psychedelic-based drugs have advanced into late-stage trials. The FDA breakthrough designation and UK Innovation Passport for DT120 create a regulatory tailwind—accelerating timelines and potentially enhancing payer and prescriber confidence if pivotal results hold up.
However, the competitive landscape for psychiatric and neurodevelopmental disorders is fierce and rapidly evolving. Other biotechs, academic spinouts, and established pharmaceutical companies are advancing alternative psychedelic compounds, novel mechanisms, and digital therapeutics. Traditional antidepressants, anxiolytics, and emerging neuromodulation approaches also compete for the same patient populations. The durability of Definium’s moat depends on successful trial outcomes, robust IP protection, and the ability to establish provider and patient trust in a historically stigmatized therapeutic class. Should DT120 or DT402 receive approval, rapid market penetration could be challenged by payer skepticism, prescriber inertia, or competitive launches.
Breakthrough Data and Regulatory Acceleration Unlock Commercialization Pathways
In an upside scenario, Definium’s ongoing Phase 3 trials for DT120 in GAD and MDD yield statistically significant and clinically meaningful results, confirming and extending the benefits seen in Phase 2b. The FDA and other regulators grant timely approval, leveraging the breakthrough therapy designation to expedite review. Early commercial launch is met with strong prescriber interest, favorable payer coverage, and rapid adoption among patients with treatment-resistant anxiety and depression.
Pipeline momentum is sustained as DT402 demonstrates early efficacy in autism spectrum disorder, opening additional market opportunities. The company leverages its liquidity to build commercial infrastructure or secure favorable licensing/partnership terms. Evidence that would confirm this scenario includes positive topline Phase 3 data, regulatory filings and approvals on or ahead of schedule, early sales traction, and expansion of the label or indications.
Clinical Progress Tempered by Market Complexity and Gradual Uptake
The most plausible scenario is that Definium delivers positive but nuanced Phase 3 results for DT120, supporting regulatory submission but potentially raising questions about patient selection, safety, or real-world effectiveness. Approval is granted, but initial commercialization is measured as payers and prescribers assess the therapy’s role relative to existing standards and competing entrants. Uptake is gradual, with revenue growth constrained by reimbursement negotiations, education efforts, and the need to overcome residual stigma around psychedelic drugs.
DT402 progresses through early clinical development, but its ultimate addressable market and value proposition remain to be proven. This scenario would be confirmed by approval of DT120 with modest early sales, ongoing Phase 2/3 studies for DT402, and persistent net losses during the commercialization ramp.
Trial Setbacks or Regulatory Barriers Erode Strategic Momentum
In a downside scenario, Phase 3 trials for DT120 fail to replicate earlier efficacy or reveal new safety concerns, leading to regulatory delays, additional study requirements, or outright rejection. Without an approved product, Definium continues to burn cash at a high rate, with the risk of future dilution or cost-cutting if additional capital is required. Competitors may seize the opportunity to advance alternative therapies or capture prescriber mindshare, further eroding Definium’s prospective market position.
Should DT402 also produce inconclusive or negative results, pipeline value would decline sharply, leaving the company exposed to sector volatility and financing risk. Evidence confirming this scenario would include negative or equivocal Phase 3 data, regulatory setbacks, workforce reductions, or strategic pivots away from core programs.
Milestones and Signals That Will Define Definium’s Transition from Clinical-Stage to Commercial Enterprise
Topline Phase 3 readouts for DT120 in both generalized anxiety disorder and major depressive disorder: the most material near-term catalysts for the company’s valuation and strategic options.
Timing, content, and regulatory feedback on New Drug Application (NDA) submissions for DT120—specifically, whether the FDA leverages the breakthrough therapy designation for accelerated review.
Early payer and prescriber adoption rates for DT120, if approved: a useful metric would be prescription growth in the first 12–24 months post-launch, as well as coverage decisions by major insurers.
Progression of DT402 through Phase 2a and into Phase 2b trials, including early efficacy signals and safety/tolerability data.
Cash burn trajectory and runway updates, particularly if disclosed in relation to commercialization plans, trial expansions, or new pipeline investments.
Announcements of partnerships, licensing deals, or commercial alliances that could supplement internal capabilities or de-risk launch.
Competitive landscape developments—such as approval or late-stage advancement of rival psychedelic or neuropsychiatric therapies—that could affect Definium’s addressable market or pricing environment.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments