
Douglas Elliman’s Luxury Focus: Platform Integration, Market Volatility, and the Sustainability of High-Touch Brokerage
Douglas Elliman leans on its luxury brand, technology investments, and comprehensive service suite to drive growth in high-value residential markets. The company’s recent operational progress is set against a backdrop of persistent market cyclicality, regulatory scrutiny, and the challenge of sustaining margins amid evolving agent and client expectations.
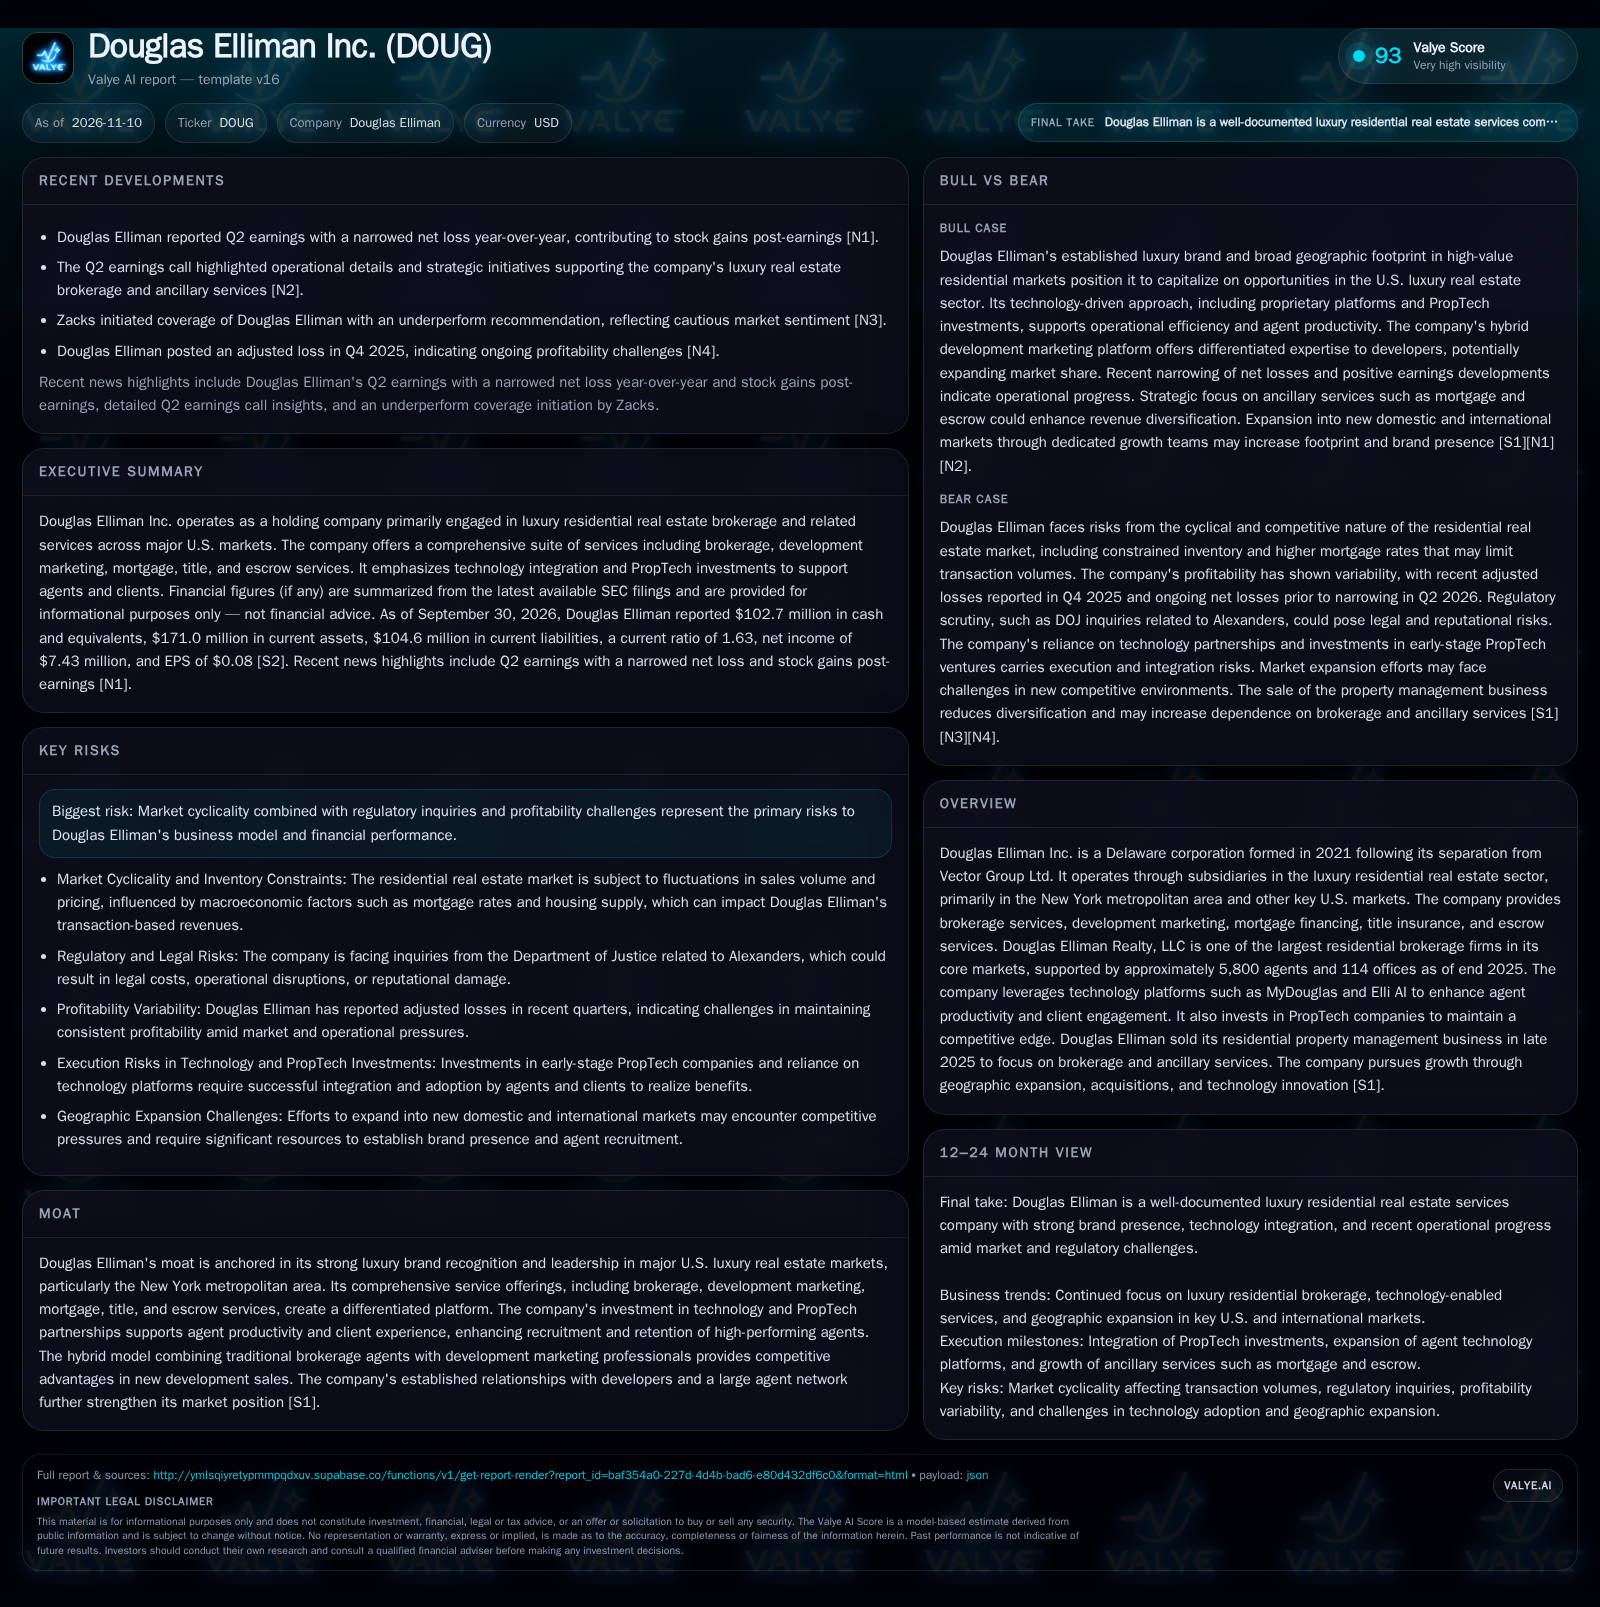
Douglas Elliman remains a leading luxury real estate brokerage with a high average transaction value and national footprint, but its fortunes are closely tied to U.S. housing cycles and competitive pressures. The company’s push into technology-enabled services and ancillary offerings could diversify revenues, yet profitability remains variable and regulatory risk is nontrivial. Execution on platform integration and market expansion will determine whether Elliman can convert its brand and agent scale into durable earnings power amid a shifting brokerage landscape. [S1] [S2]
Douglas Elliman Inc. stands as one of the largest luxury residential brokerages in the U.S., wielding a strong brand and a broad agent network across high-value coastal and urban markets. Recent results show a return to profitability in Q3 2026 after periods of net losses, as the company pivots further into technology integration and ancillary services to offset the inherent volatility of real estate cycles. Yet, the company’s future hinges on its ability to sustain agent productivity, navigate regulatory headwinds, and realize the promise of its technology and platform investments. In an increasingly competitive—and cyclically exposed—luxury brokerage landscape, Elliman’s next chapter will be defined by its capacity to balance operational leverage, agent incentives, and the evolving expectations of high-net-worth clients. [S1] [S2]
Recent Profitability, Luxury Positioning, and Strategic Shifts Define the Present
Douglas Elliman reported a net income of $7.43 million and EPS of $0.08 for Q3 2026, marking a period of operational improvement following earlier adjusted losses in Q4 2025. This return to profitability is notable given the company’s exposure to cyclical luxury housing markets and recent market-wide constraints on transaction volumes. [S2] [N4]
With an average home transaction value of $1.86 million in 2025, Elliman’s business is concentrated in high-value segments, supporting higher potential commission revenues per deal compared to mainstream brokerages. The company’s agent base of roughly 5,800 and 114 offices as of year-end 2025 underscores its national scale, especially in luxury markets across New York, Florida, and California. [S1]
Elliman’s strategic focus has shifted further toward core brokerage and ancillary services, following the sale of its property management business in October 2025. The company continues to emphasize technology platform integration and PropTech investment, allocating $11.4 million to PropTech as of December 2025. [S1]
How Elliman’s Revenue Model and Cost Structure Interact with Housing Cycles
Douglas Elliman’s core economics are driven by transaction-based commission revenues—meaning that topline performance is highly sensitive to luxury home sales volumes and pricing trends. With an average home transaction value of $1.86 million, even modest swings in unit volumes or price per home can have outsized impacts on revenue. The company’s commission splits with agents are a key variable cost; as is typical in the industry, top-producing agents command higher splits, which can pressure gross margins as the company seeks to attract and retain talent.
The expansion into ancillary services (mortgage, title, escrow) offers potential for higher take-rates and margin accretion, as these services can be cross-sold to brokerage clients. However, the sale of the property management business reduces revenue diversification and leaves the company more exposed to residential transaction cycles.
Operating leverage is present but limited by the variable nature of agent commissions and the necessity of high-touch service. Fixed costs include office leases, technology investments, and management overhead. Technology platforms—if widely adopted—could create incremental efficiencies in agent productivity and client onboarding, but the capital outlay for PropTech and platform integration may weigh on near-term margins if transaction volumes soften.
Capital needs are relatively modest for a brokerage model, outside of technology and platform investment. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2]
Brand, Breadth, and Platform: Sources of Advantage and Points of Vulnerability
Douglas Elliman’s competitive edge rests on its strong luxury brand reputation, deep developer relationships, and comprehensive service suite in high-value urban markets. Its national agent network and development marketing division allow it to serve both buyers and large-scale projects, differentiating it from smaller boutiques and some digital-first entrants.
However, the competitive landscape is shifting. Traditional brokerages face margin compression from digital competitors, discount models, and platforms that seek to disintermediate agents or reduce commission rates. Luxury segments may be somewhat insulated by client preference for high-touch, relationship-driven service, but even these are subject to pressure as technology platforms improve transparency and convenience.
Elliman’s investments in proprietary technology (e.g., MyDouglas, Elli AI) and PropTech partnerships are intended to support agent productivity and client experience, but the real test is whether these features drive agent recruitment/retention and client conversion at a lower cost than competitors. The company’s ability to scale ancillary services and integrate offerings across its network is another potential advantage—but also a complex operational challenge.
The company’s withdrawal from property management narrows its diversification, making its core business more susceptible to competitive and market shocks.
If Technology-Enabled Brokerage Yields Higher Margins and Market Share
The bullish scenario for Douglas Elliman centers on successful execution of its technology integration and the expansion of ancillary services. If proprietary platforms like MyDouglas and Elli AI materially increase agent productivity—by automating administrative tasks, surfacing leads, or improving client engagement—the company could see higher agent retention and recruitment, allowing it to grow market share without proportionally increasing fixed costs.
Further, if cross-selling of mortgage, title, and escrow products becomes standard in Elliman transactions, the company could capture a greater share of the total home-buying wallet, smoothing revenues even if transaction volumes fluctuate. Such integration could also foster stickier client relationships and higher overall margin per transaction.
Confirmation of this scenario would require evidence of increasing agent productivity metrics (e.g., deals per agent, retention rates), higher penetration rates of ancillary products, and margin expansion even as the agent base scales. Sustained positive net income, especially in weaker housing markets, would also support the upside case.
Navigating Cycles: Operational Progress Balanced by Enduring Volatility
The most plausible scenario for Douglas Elliman is continued cyclicality in top-line growth and profitability, with operational progress in technology and ancillary services offset by the realities of the luxury housing market. The company is likely to maintain its strong brand and agent base, but commission splits and competitive pressure will constrain margin expansion.
Incremental improvements in agent productivity and technology adoption may help stabilize earnings, but the company remains exposed to swings in luxury home transaction volumes—especially in New York, Florida, and California. The sale of property management assets increases this sensitivity.
This scenario would be confirmed by ongoing modest profitability or break-even results, stable or slightly improving agent recruitment/retention rates, and steady ancillary revenue contribution. A reversal—such as declining agent headcount, persistent losses, or further margin compression—would suggest the base case is too optimistic.
Luxury Market Downturn, Regulatory Pressure, and Platform Execution Risks
The bearish scenario for Douglas Elliman involves a sustained downturn in luxury home transactions—potentially triggered by rising mortgage rates, a broader economic slowdown, or persistent inventory constraints. In this environment, the company’s high fixed costs (office leases, technology investments) could become a burden, especially as commission revenues fall and agent splits remain competitive.
Regulatory scrutiny, such as ongoing DOJ inquiries, could lead to legal expenses, operational disruption, or even reputational damage that impacts agent and client acquisition. At the same time, if technology investments fail to deliver productivity gains or are poorly adopted by agents, the company could face rising costs without offsetting revenue growth.
This scenario would be confirmed by renewed net losses, declining agent headcount, weak adoption of technology platforms (if disclosed), and negative news flow related to regulatory actions or legal costs.
Milestones and Data Points That Will Reveal Elliman’s Ability to Convert Scale Into Sustainable Earnings
Agent productivity metrics—such as average transactions per agent and agent retention—would provide insight into the effectiveness of technology platforms and Elliman’s value proposition (if disclosed).
Penetration rates for ancillary services (mortgage, title, escrow) as a percentage of total transactions would help test the thesis that diversification can smooth revenues and improve margins.
Sustained net income or margin expansion, particularly in periods of market softness, would indicate improved operating leverage or successful cost management.
Agent headcount and office footprint trends will reveal whether Elliman is maintaining or growing share in core and expansion markets.
Adoption rates for proprietary technology platforms among agents (if disclosed) would be a leading indicator of ROI from PropTech investments.
Regulatory developments—such as resolution or escalation of DOJ inquiries—could materially impact near- and long-term performance.
Market share in core luxury metros (New York, Miami, Los Angeles) versus peers, if disclosed, would clarify competitive positioning.
Transaction volume and average deal size trends, especially relative to macroeconomic and housing market conditions, will be critical for forecasting revenue volatility.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments