
Dermata’s Bioneedle Bet: Shifting from Prescription to Consumer Skincare in a Crowded Market
Dermata Therapeutics is repositioning itself from Rx acne therapies to direct-to-consumer and B2B cosmetic and OTC skincare, leveraging proprietary Bioneedle technology. With mid-2026 launches approaching, the company’s ability to carve out a defensible niche will depend on product differentiation, execution in consumer channels, and evidence of real-world impact beyond clinical promise.
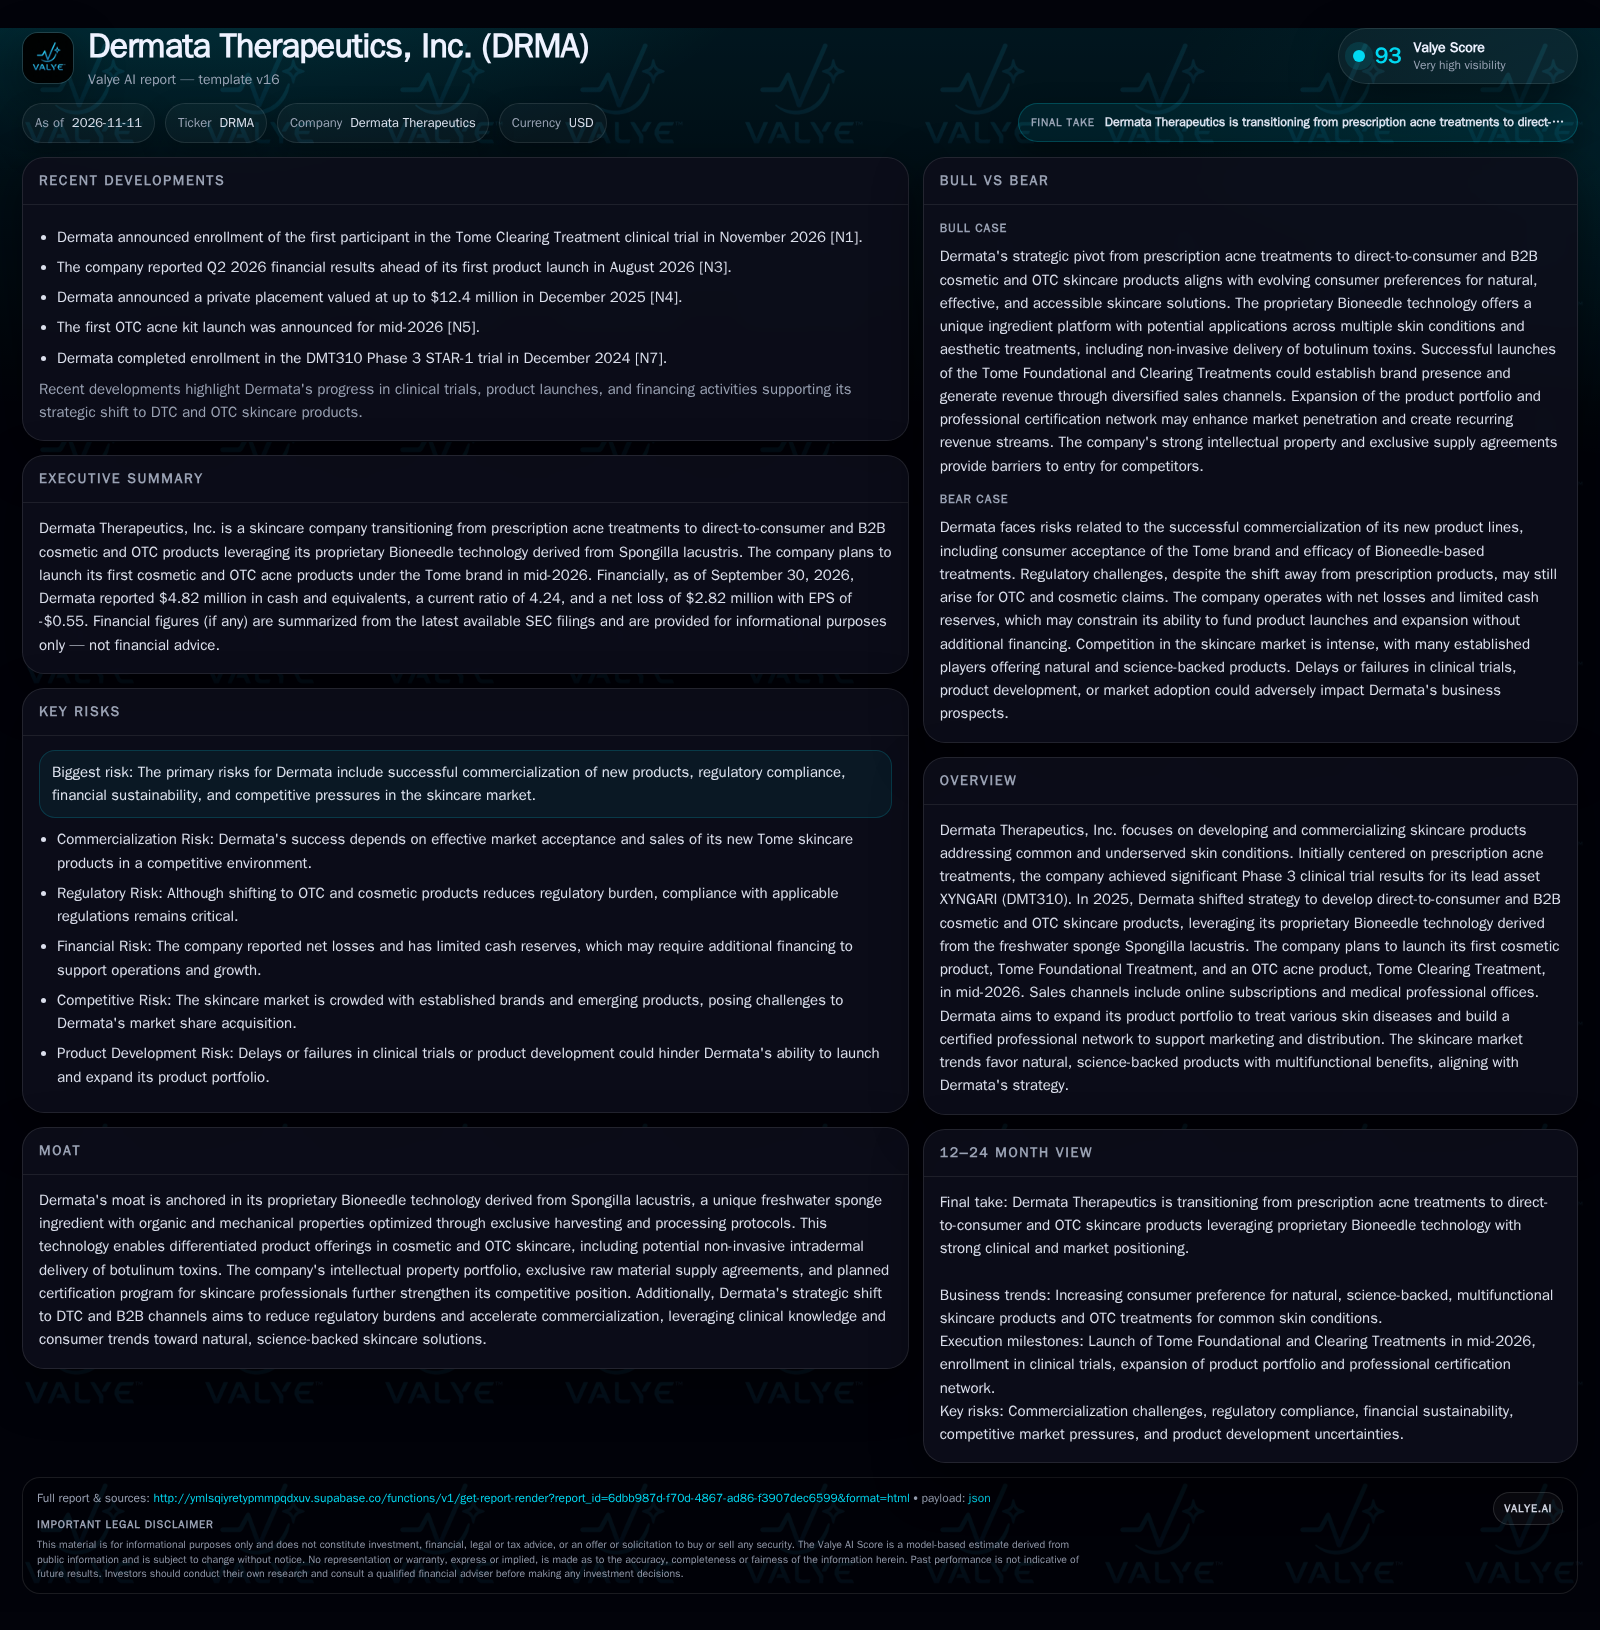
Dermata Therapeutics is pivoting from prescription acne drugs to consumer and professional skincare, launching its first Bioneedle-based cosmetic and OTC acne products in mid-2026. The company’s clinical pedigree and proprietary technology offer a unique angle, but success will hinge on market adoption, competitive positioning, and prudent financial management as it transitions to faster-cycle, high-competition channels. [S1] [N1] [N3] [S2]
Dermata Therapeutics stands at a strategic crossroads, shifting from a prescription-focused biotech to a consumer-oriented skincare company built on proprietary Bioneedle technology. With launches of its Tome Foundational Treatment and OTC Tome Clearing Treatment slated for mid-2026, Dermata is aiming to capture demand for natural, science-backed skincare in both direct-to-consumer and professional channels. The company’s successful execution will depend not only on clinical results, but on product-market fit, brand traction, and the ability to compete against entrenched and emerging players in a rapidly evolving landscape. Financial sustainability will be tested as the company invests in commercialization with reported cash balance and ongoing losses. [S1] [N1] [N3] [S2]
Dermata’s Strategic Pivot: From Clinical Milestones to Consumer Product Launch
Dermata Therapeutics is preparing to launch its first cosmetic and OTC acne products—the Tome Foundational Treatment and Tome Clearing Treatment—in mid-2026, marking a significant transition from its original focus on prescription acne therapies. The company’s proprietary Bioneedle technology, developed from Spongilla lacustris, is positioned as a differentiator in a market seeking natural, science-backed solutions. Recent developments include the enrollment of the first participant in the Tome Clearing Treatment clinical trial in November 2026, and a reported cash balance of $4.82 million with a net loss of $2.82 million as of September 30, 2026. These facts set the stage for Dermata’s execution risk as it moves from clinical promise to commercial reality. [S1] [N1] [N3] [S2]
Making Money in Skincare: Subscription Ambitions and Fixed-Cost Leverage
Dermata’s new business model is built around selling cosmetic and OTC skincare products through monthly subscriptions on its website and via medical professionals for in-office treatments. The company aims to leverage its proprietary Bioneedle ingredient to create a recurring revenue stream, capitalizing on consumer willingness to pay for natural and clinically validated solutions. The economics of DTC skincare can offer attractive gross margins, particularly if customer acquisition costs (CAC) and churn are kept in check. However, scaling requires significant upfront investment in marketing, education, and distribution. Fixed costs related to product development, manufacturing scale-up, and professional certification will create operating leverage, but only if volumes ramp as planned.
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. If Dermata achieves a high subscription retention rate and successful B2B uptake, fixed-cost leverage could translate into positive operating margins. Conversely, slow adoption or high CAC would magnify losses and necessitate further dilution or strategic alternatives.
A critical factor in Dermata's subscription model success lies in the unit economics of customer acquisition and retention. Given the crowded skincare market, the cost to attract and convert consumers can be substantial, especially when competing against brands with established digital marketing expertise and larger advertising budgets. If Dermata can leverage its clinical data and unique Bioneedle technology to reduce skepticism and shorten the consumer decision cycle, it could lower CAC and improve payback periods. Conversely, failure to create compelling, differentiated messaging or to optimize digital channels could lead to elevated CAC, pressuring margins and cash flow.
Furthermore, the scalability of Dermata's manufacturing and supply chain infrastructure will influence operating leverage. Proprietary ingredients and specialized delivery formats like Bioneedles may entail higher production complexity and costs compared to conventional skincare products. If the company can achieve economies of scale through volume growth and process optimization, fixed costs per unit will decline, enhancing gross margins. However, if production scale-up encounters technical hurdles or supply constraints, cost inefficiencies could persist, limiting profitability despite revenue growth. Strategic partnerships with contract manufacturers or ingredient suppliers could mitigate these risks but may introduce margin dilution or dependency.
Differentiation Versus the Crowd: Can Bioneedle Technology Stand Out?
Dermata contends with a fiercely competitive skincare market populated by legacy brands, celebrity lines, and emerging science-driven startups. Its moat is rooted in proprietary Bioneedle technology and exclusive supply agreements, enabling a unique ingredient story and potential for novel delivery mechanisms, including non-invasive intradermal therapies. However, the DTC and OTC skincare segments are characterized by rapid product proliferation and aggressive marketing from both large incumbents and digitally native brands.
Switching costs for consumers are low, and efficacy claims are often difficult to substantiate outside of prescription channels. Dermata’s planned professional certification network may provide some channel stickiness and credibility, but the ability to generate meaningful market share will depend on clear, demonstrable benefits and the translation of clinical trial results into compelling consumer experiences. Partnerships and licensing could open global markets, but these routes often come with margin trade-offs and execution complexity.
Dermata's ability to defend its market position depends not only on product differentiation but also on intellectual property protection and barriers to imitation. While proprietary Bioneedle technology offers a novel delivery mechanism, the skincare industry has a history of rapid replication and reformulation by competitors once a concept gains traction. The durability of Dermata's competitive advantage will hinge on the strength and breadth of its patents, trade secrets, and exclusive supply arrangements. Additionally, the company must anticipate potential regulatory scrutiny around novel delivery systems in OTC and cosmetic categories, which could affect time-to-market and marketing claims.
Moreover, consumer behavior in skincare is notably influenced by brand trust, social proof, and influencer endorsements. Dermata's professional certification network may help build credibility among dermatologists and estheticians, but translating this into sustained consumer loyalty requires a seamless omnichannel experience and effective community engagement. The low switching costs in skincare imply that even minor lapses in product efficacy or customer service could lead to churn. Therefore, Dermata's investment in customer education, transparent communication about Bioneedle benefits, and responsiveness to consumer feedback will be crucial to maintaining differentiation in a fragmented market.
How a Breakout Brand and Evidence-Based Skincare Could Fuel Rapid Growth
The most favorable scenario for Dermata envisions strong uptake of Tome products, driven by visible efficacy, positive consumer reviews, and endorsement by skincare professionals. The Bioneedle platform could prove to be a compelling differentiator, especially if clinical trial data for the Tome Clearing Treatment translate into superior real-world outcomes for acne and other conditions. If Dermata’s subscription and professional channels achieve rapid penetration, operating leverage could flip the company to profitability, enabling reinvestment in portfolio expansion and global licensing.
Evidence that would confirm this upside includes high initial subscription growth, robust reorder rates, favorable clinical trial readouts, and early traction in professional certification. Announcements of strategic partnerships or international expansion deals would further support a breakout trajectory.
Navigating Launch Uncertainties in a Crowded Skincare Market
The most plausible near-term path for Dermata is moderate adoption of its Tome products, with initial sales ramping slowly as the company builds brand awareness and professional networks. Bioneedle technology may provide some differentiation, but consumer skepticism and intense competition could limit pricing power and require ongoing marketing investment. The company may need to secure additional capital to fund operations as net losses persist, especially if customer acquisition proves more costly than anticipated.
Confirmation of this scenario would include steady but unspectacular subscription growth, continued net losses, and incremental expansion of the product portfolio. If professional channel uptake is gradual and clinical data drive only modest consumer conversion, Dermata may remain a niche player with potential for future inflection points if new indications or partnerships materialize.
If Adoption Stalls: Cash Burn, Competitive Squeeze, and Strategic Risk
An adverse outcome would see Dermata’s Tome launches fail to gain traction, either due to lackluster efficacy, poor consumer adoption, or failure to differentiate in a saturated market. High customer acquisition costs, low retention, or negative reviews could rapidly erode cash reserves, forcing the company to seek dilutive financing or consider asset sales. Regulatory or product development setbacks for future Bioneedle applications could compound the challenges.
Evidence of this downside would include disappointing initial sales, high churn rates, mounting losses, and adverse clinical or regulatory developments. If Dermata is unable to secure additional funding or strategic partners, the viability of the current business model would be in jeopardy.
Milestones That Will Reveal Dermata’s Real-World Traction and Risk
Monthly subscription growth and retention rates for Tome Foundational and Clearing Treatments, if disclosed, as a proxy for early consumer adoption.
Initial reorder rates and customer lifetime value (CLV) relative to customer acquisition cost (CAC), which would illuminate the sustainability of the DTC model.
Professional certification network expansion—number of certified skincare professionals and their engagement with Dermata’s products.
Clinical trial outcomes for the Tome Clearing Treatment and other Bioneedle-based products, especially real-world effectiveness versus competitors.
Cash burn rate and timing or terms of any additional financing rounds, as continued net losses may require further capital.
Product reviews and brand sentiment across digital platforms, as consumer perception will influence adoption velocity.
Progress toward partnerships or licensing agreements for international expansion or additional indications, which could alter the scale and economics of the business.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments