
Eaton’s Strategic Shift: Electrification, Acquisitions, and the Mobility Spin-Off Redefine Power Management Ambitions
Eaton’s surge in electrical and aerospace markets is fueled by infrastructure megatrends and recent acquisitions, but the pending Mobility spin-off/merger with Dana adds operational complexity and execution risk. The company’s ability to integrate new assets and deliver on its core power management vision will determine whether its recent growth is sustainable.
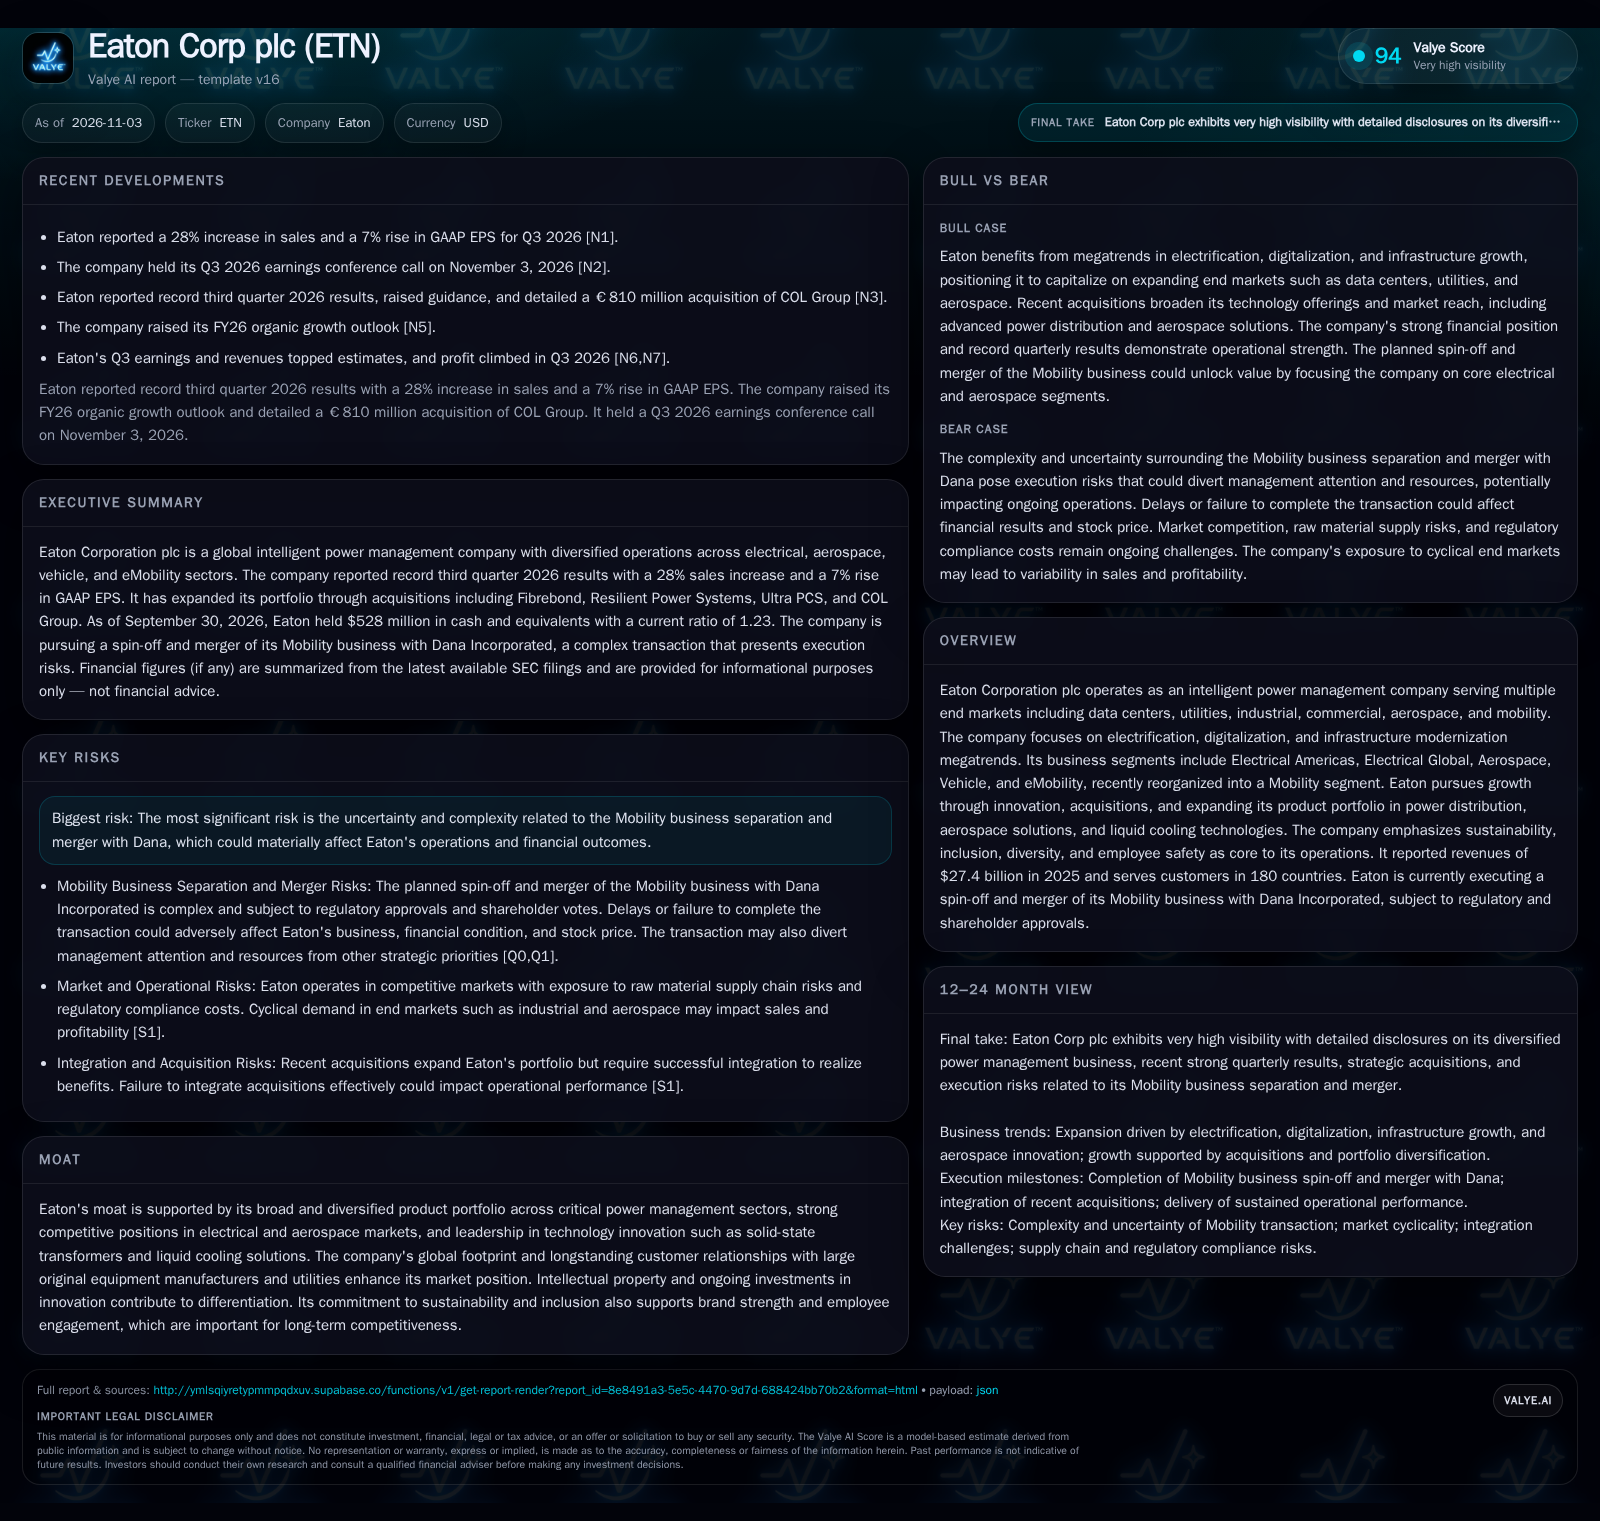
Eaton reported a 28% sales increase and record Q3 2026 results, driven in part by acquisitions and electrification momentum. The planned spin-off and merger of its Mobility business with Dana could sharpen its focus but introduces significant execution risk. Integration of new assets and ongoing margin expansion in core segments will be critical to sustaining Eaton’s growth trajectory. [S1] [N1] [N3]
Eaton Corporation stands at a strategic crossroads: its recent 28% sales surge and record quarterly results are powered by global trends in electrification, digital infrastructure, and aerospace modernization. Aggressive acquisitions and a sharpened product portfolio have placed Eaton in a position to benefit from expanding end markets, but the planned spin-off and merger of its Mobility business with Dana introduces significant complexity. The company’s next phase will hinge on its ability to integrate new assets, maintain operational discipline, and deliver on the core promise of intelligent power management without disruption from the pending separation.
Recent Performance Surges and Strategic Transactions Shape Eaton’s Outlook
Eaton reported a 28% increase in sales and a 7% rise in GAAP EPS for Q3 2026, marking a record quarter and prompting the company to raise its guidance for the year. This performance was supported by both organic growth and the impact of recent acquisitions, including the €810 million COL Group deal and agreements to acquire Boyd Thermal. At the same time, Eaton is preparing for a major structural shift: the planned spin-off of its Mobility business and subsequent merger with Dana Incorporated, targeted for early 2027, pending regulatory and shareholder approvals. The company’s recent acquisitions and the complex Mobility transaction are set to shape both its operational focus and risk profile in the coming quarters. [S1] [S2] [N1] [N3]
How Eaton’s Diversification and Scale Drive Economic Leverage
Eaton’s business model is built on diversification across end markets—data centers, utilities, industrial, commercial, aerospace, and mobility—each with different demand cycles and capital requirements. The Electrical Americas and Electrical Global segments deliver the majority of revenues and benefit from infrastructure modernization, grid upgrades, and electrification spending. These segments typically enjoy higher-margin, solutions-oriented sales, where integration of hardware, software, and services can create customer stickiness and pricing power, especially in mission-critical applications.
The Aerospace segment targets commercial, military, and space customers, where long-term contracts and aftermarket services can provide revenue visibility and higher incremental margins. Recent acquisitions (e.g., Ultra PCS, Resilient Power Systems) could further strengthen Eaton’s position in supplying more electric and sustainable aviation solutions.
Eaton’s ability to scale new acquisitions and integrate them into its product ecosystem is key to realizing operating leverage. Acquisitions like COL Group and Boyd Thermal may offer synergies in power distribution and data center cooling, but integration costs and execution complexity can weigh on near-term margins. The planned Mobility spin-off and merger with Dana, if completed, will shift Eaton’s capital intensity profile, potentially reducing exposure to more cyclical vehicle markets and freeing up capital for further investment in electrical and aerospace innovation.
The company’s moderate current ratio and reported cash ratio reflect a working-capital-focused balance sheet rather than an outsized cash position. Sustaining growth will require continued strong cash flow from operations and disciplined capital allocation, particularly given the demands of acquisition integration and the Mobility separation.
Can Eaton Defend Its Edge in a Crowded Power Management Landscape?
Eaton’s competitive strength lies in its broad portfolio and global reach, serving customers in 180 countries with solutions spanning the entire electrical value chain. In electrical and power management, the company competes with other diversified industrials and specialized electrical equipment firms. Its scale, systems integration capabilities, and deep relationships with OEMs and utilities provide some switching friction and pricing power, particularly for customers seeking end-to-end solutions or high reliability.
Recent acquisitions have targeted adjacent technologies—such as solid-state transformers, liquid cooling for data centers, and advanced aerospace systems—that could reinforce differentiation if successfully commercialized and integrated. However, the company faces persistent competition from global peers, emerging technology entrants, and low-cost providers, especially in commoditized hardware or geographies where brand is less differentiated.
The planned Mobility spin-off and merger may enhance focus and resource allocation in core segments, potentially sharpening Eaton’s competitive edge in electrical and aerospace markets. However, the separation also risks operational distraction, and the loss of cross-segment synergies could expose the remaining businesses to more direct competition.
If Integration Delivers and Electrification Accelerates, Margin Expansion Could Outpace Expectations
A favorable scenario for Eaton would see seamless integration of recent acquisitions, enabling the company to rapidly commercialize new technologies in power distribution, data center cooling, and aerospace electrification. If the Mobility spin-off and Dana merger close on schedule and with minimal disruption, Eaton could focus capital and management attention on its highest-margin, highest-growth segments. Infrastructure spending, grid modernization, and electrification tailwinds could drive sustained high-single-digit organic growth, while improved product mix and operating leverage expand margins.
Evidence confirming this scenario would include: successful and rapid revenue contribution from acquired businesses, above-peer margin expansion in electrical and aerospace segments, timely completion of the Mobility transaction, and continued upward revisions to organic growth guidance. Disconfirming evidence would be integration setbacks, delays in the Mobility spin-off, or signs that new acquisitions are dilutive to margins or cash flow.
Resilient Growth with Integration Friction and Transaction Drag
The most plausible outcome is that Eaton continues to benefit from electrification and infrastructure megatrends, with steady revenue growth in its electrical and aerospace businesses. However, the integration of multiple acquisitions and the execution burden of the Mobility spin-off/merger will likely create near-term friction, including incremental costs and management distraction. Margin expansion may moderate as integration expenses and transaction-related costs offset some operational efficiencies.
This scenario would be confirmed by stable, mid-single-digit organic growth, modest margin improvement, successful but not seamless contribution from new acquisitions, and incremental progress on the Mobility separation. Falsifying evidence would include major delays or cost overruns in integration, or a material drop in core segment profitability as management bandwidth is stretched.
Mobility Separation Stumbles and Acquisition Integration Falters
In a negative scenario, the Mobility spin-off and merger with Dana could face regulatory delays, execution missteps, or fail to close, forcing Eaton to retain a segment that diverts resources from its core. Simultaneously, if recent acquisitions prove difficult to integrate, operational complexity could erode margins and lead to missed synergy targets. Customer or supplier disruption from the transaction, or misalignment in acquired businesses, could weigh on both top-line growth and profitability.
Confirmation would come from public delays or withdrawal of the Mobility transaction, negative revisions to guidance, or evidence of margin compression and cost overruns in acquired segments. Disconfirmation would be smooth transaction execution and steady or improving segment profitability despite integration activity.
What Will Validate Eaton’s Strategic Realignment and Growth Thesis?
Progress and regulatory milestones toward the Mobility spin-off and merger with Dana; any announced delays, revised terms, or regulatory pushback will be critical.
Organic growth rates in Eaton’s core Electrical Americas, Electrical Global, and Aerospace segments, especially relative to end-market peers.
Contribution to revenue and margins from recent acquisitions (COL Group, Boyd Thermal, Fibrebond, Resilient Power Systems, Ultra PCS); a useful metric would be segment-level margin trends if disclosed.
Integration costs and synergy realization from acquired businesses; evidence of cost overruns or delayed synergies would test the expected benefits.
Changes in guidance for FY26 and beyond, particularly around organic growth, margin targets, and capital allocation priorities.
Liquidity and cash flow generation post-transaction, as measured by operating cash flow, free cash flow, or net leverage if disclosed.
Management commentary on operational focus and resource allocation, especially during the Mobility transaction period.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments