
Evolv Technologies: AI Security Screening Confronts Scale, Loss, and Control Dynamics
Evolv Technologies’ AI-powered security screening platform has gained traction across diverse venues with a subscription-based model, but persistent losses, internal control weaknesses, and execution risks loom over its path to sustainable profitability.
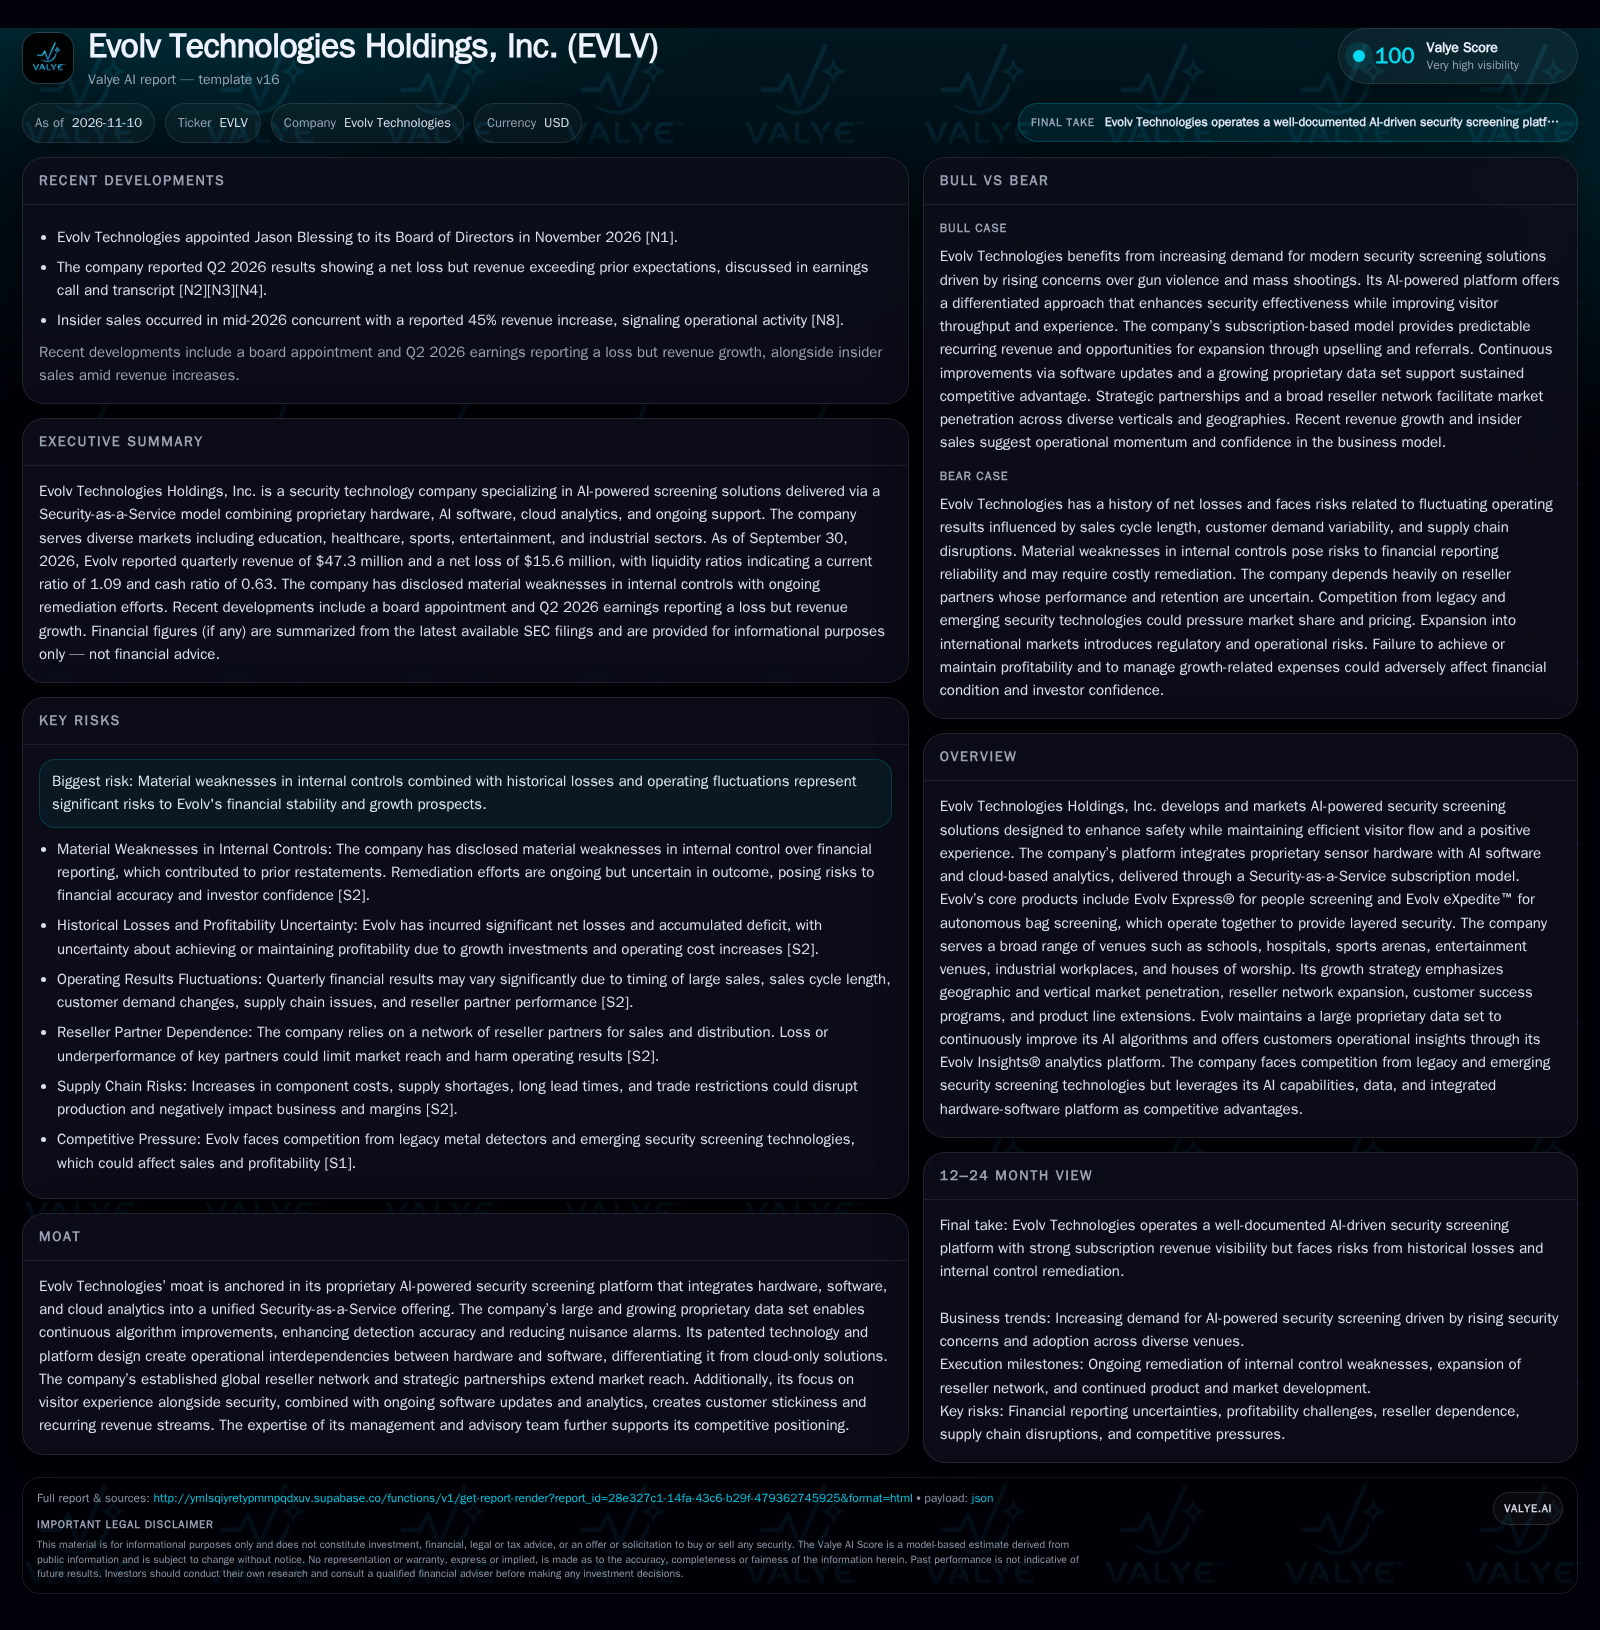
Evolv Technologies delivers AI-powered security screening solutions through a Security-as-a-Service model, targeting high-traffic venues with integrated hardware and software. While revenue growth has been robust—Q3 2026 saw $47.3 million in revenue and a 45% jump cited earlier—net losses persist, with a $15.6 million loss reported for the quarter and ongoing material control weaknesses. The company's competitive edge lies in its proprietary data, AI detection, and recurring revenue model, but path to profitability and operational reliability remain open questions. [S1] [S2] [N4] [N8]
Evolv Technologies Holdings, Inc. has positioned itself at the intersection of rising public safety concerns and the demand for seamless visitor experiences. Its AI-driven security screening solutions—delivered via a recurring subscription model—have helped it penetrate high-profile venues across education, healthcare, and entertainment. Yet, despite strong revenue growth and ambitious market claims, Evolv continues to operate at a loss and faces scrutiny over material internal control weaknesses. The question is whether its data-driven platform and expanding footprint can ultimately deliver sustainable economics, or if persistent execution and financial reliability challenges will constrain its long-term value.
Financial Results and Operational Advances Define Near-Term Prospects
Evolv Technologies reported Q3 2026 revenue of $47.3 million, marking continued top-line growth, while net losses persisted at $15.6 million for the quarter and an accumulated deficit of $417.7 million as of September 30, 2026. These losses highlight the company’s ongoing struggle to achieve profitability despite increasing sales. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2]
Material weaknesses in internal controls over financial reporting remain unresolved, with management indicating that remediation efforts are underway but not yet complete. This raises the risk of financial misstatements or reporting delays, which could undermine investor confidence and complicate future capital-raising or partnership efforts. [S2]
Operationally, Evolv claims to screen over four billion visitors worldwide since 2019 and asserts that it now screens more daily visitors than the TSA. The company’s reach includes major sports stadiums, healthcare facilities, schools, and other high-traffic venues, pointing to real-world scale, though the economics of these deployments remain under scrutiny. [S1]
Economics of the Subscription Model: Revenue Streams and Cost Implications
Evolv’s Security-as-a-Service model blends proprietary hardware, AI-powered software, cloud analytics, and ongoing support, with revenue generated through both pure subscription and purchase subscription contracts. This creates recurring revenue streams—typically valued by investors for their predictability—but also embeds significant fixed costs for hardware R&D, manufacturing, support, and continual AI/software updates. [S1]
The company’s economics hinge on customer adoption across thousands of high-traffic sites, with each contract combining hardware deployment and multi-year software/service subscriptions. If average deal sizes are meaningful and churn is low, operating leverage could improve as the installed base grows and marginal software/service revenues outpace incremental costs. However, the need to maintain and update hardware in the field, plus high-touch support, likely means a slower ramp to positive margins than pure SaaS models.
With an accumulated deficit of $417.7 million and ongoing net losses, Evolv must scale revenue faster than fixed and variable costs—while also managing working capital needs for hardware and inventory. [S2]
AI and Data Provide Edge Amid Established and New Competitors
Evolv’s core competitive advantage lies in its proprietary AI algorithms, sensor fusion, and the ability to continuously improve detection via a large, proprietary data set. This enables the company to offer higher throughput and lower nuisance alarms than traditional metal detectors, which is especially attractive to venues demanding both security and visitor experience. [S1]
The company’s integrated platform—combining hardware, software, cloud analytics, and ongoing support—creates switching frictions and the potential for high customer retention if performance matches claims. Ongoing software updates and analytics further embed Evolv’s systems in customer operations, though the extent of this stickiness depends on contract terms and operational dependencies, which are not fully disclosed.
However, Evolv faces competition from both legacy metal detector providers and newer entrants offering AI-enhanced or computer vision-based screening. Some rivals may attack on price or simplicity, while others may try to match Evolv’s data-driven approach. The company’s global value-added reseller network and strategic partnerships help extend reach, but also introduce channel dependency and potential margin pressure if reseller performance is uneven. [S1]
Platform Scale Could Drive Margin Gains and Enhance Customer Loyalty
A favorable trajectory for Evolv would see continued rapid adoption across high-value venues, with existing customers expanding deployments and new verticals—such as healthcare and industrial workplaces—accelerating uptake. If customer churn remains low and subscription contract values rise through upsell or product extensions, recurring revenue could scale faster than fixed costs, driving operating leverage.
The company’s ability to deliver continuous AI-driven improvements via software updates and leverage its growing data set could further differentiate performance, justifying premium pricing and cementing customer loyalty. Expansion of the reseller network and successful execution in international markets could add additional growth layers.
Confirmation would come from sustained double-digit ARR growth, gross margin expansion, and evidence of high contract renewal rates, as well as clear disclosure of positive operating cash flow or a credible path to break-even. Conversely, if customer churn rises or new deployments slow, the upside thesis would weaken.
Revenue Growth and Loss Reduction Depend on Execution and Transparency
The most plausible scenario is that Evolv continues to grow revenue at a healthy pace as security concerns drive adoption across its core verticals, but the path to profitability remains protracted. Gross margins may gradually improve as the installed base expands and software/service revenues rise, but hardware costs, ongoing support, and the need for continual R&D investment limit near-term margin expansion.
Internal control remediation likely progresses but may not be fully resolved in the next several quarters, keeping some overhang on financial reporting reliability. Supply chain and reseller partner performance remain variable, occasionally impacting quarter-to-quarter results.
This scenario is confirmed by continued revenue growth, modest improvements in net loss, and incremental disclosures about control remediation progress and customer retention. It would be falsified if losses widen, internal control issues persist without progress, or revenue growth stalls.
Sales Instability or Control Issues May Undermine Progress
A negative outcome for Evolv could stem from persistent or worsening material weaknesses in internal controls, leading to restatements or delays that erode investor and customer trust. If customer adoption slows—due to competitive pricing pressure, missed product expectations, or operational disruptions from supply chain issues—revenue growth could falter.
Heavy dependence on reseller partners exposes Evolv to risk if channel performance is uneven or if key partners are lost, potentially resulting in sales volatility and margin compression. Additionally, if hardware or support costs remain structurally high, the company may not achieve the operating leverage necessary for profitability, eventually forcing dilutive capital raises or strategic retrenchment.
Evidence of this scenario would include repeated financial reporting delays, deteriorating gross margins, a spike in customer churn, or negative operating cash flow with no clear improvement trajectory.
Key Developments Influencing Evolv’s Future Value Creation
Progress and transparency in remediating material weaknesses in internal controls, including timely updates on audit findings and any restatements.
Sustained growth in Annual Recurring Revenue (ARR) and Remaining Performance Obligation (RPO), as disclosed, to test the scale and durability of the subscription model.
Gross margin trends, especially as the installed base grows—any signs of margin expansion would support the operating leverage thesis.
Churn and renewal rates for subscription contracts, if disclosed, as a direct measure of customer stickiness and satisfaction.
Evidence of operating cash flow improvement or path to break-even, via quarterly cash flow statements.
Updates on reseller partner performance and expansion of the channel network, including any major partner losses or additions.
Deployment growth in key verticals (education, healthcare, sports, etc.) and success in expanding into new geographies or market segments.
Impact of supply chain disruptions or component cost inflation on hardware delivery and system deployment timelines.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments