
ExlService Holdings: AI Ambition, Diversification, and the Realities of Scaling Digital Solutions
Strong Q3 2026 results and a raised full-year outlook highlight ExlService’s momentum in data and AI-led services. The challenge now is to translate its diversified client base and recent acquisitions into sustained operating leverage and defendable growth as industry competition intensifies.
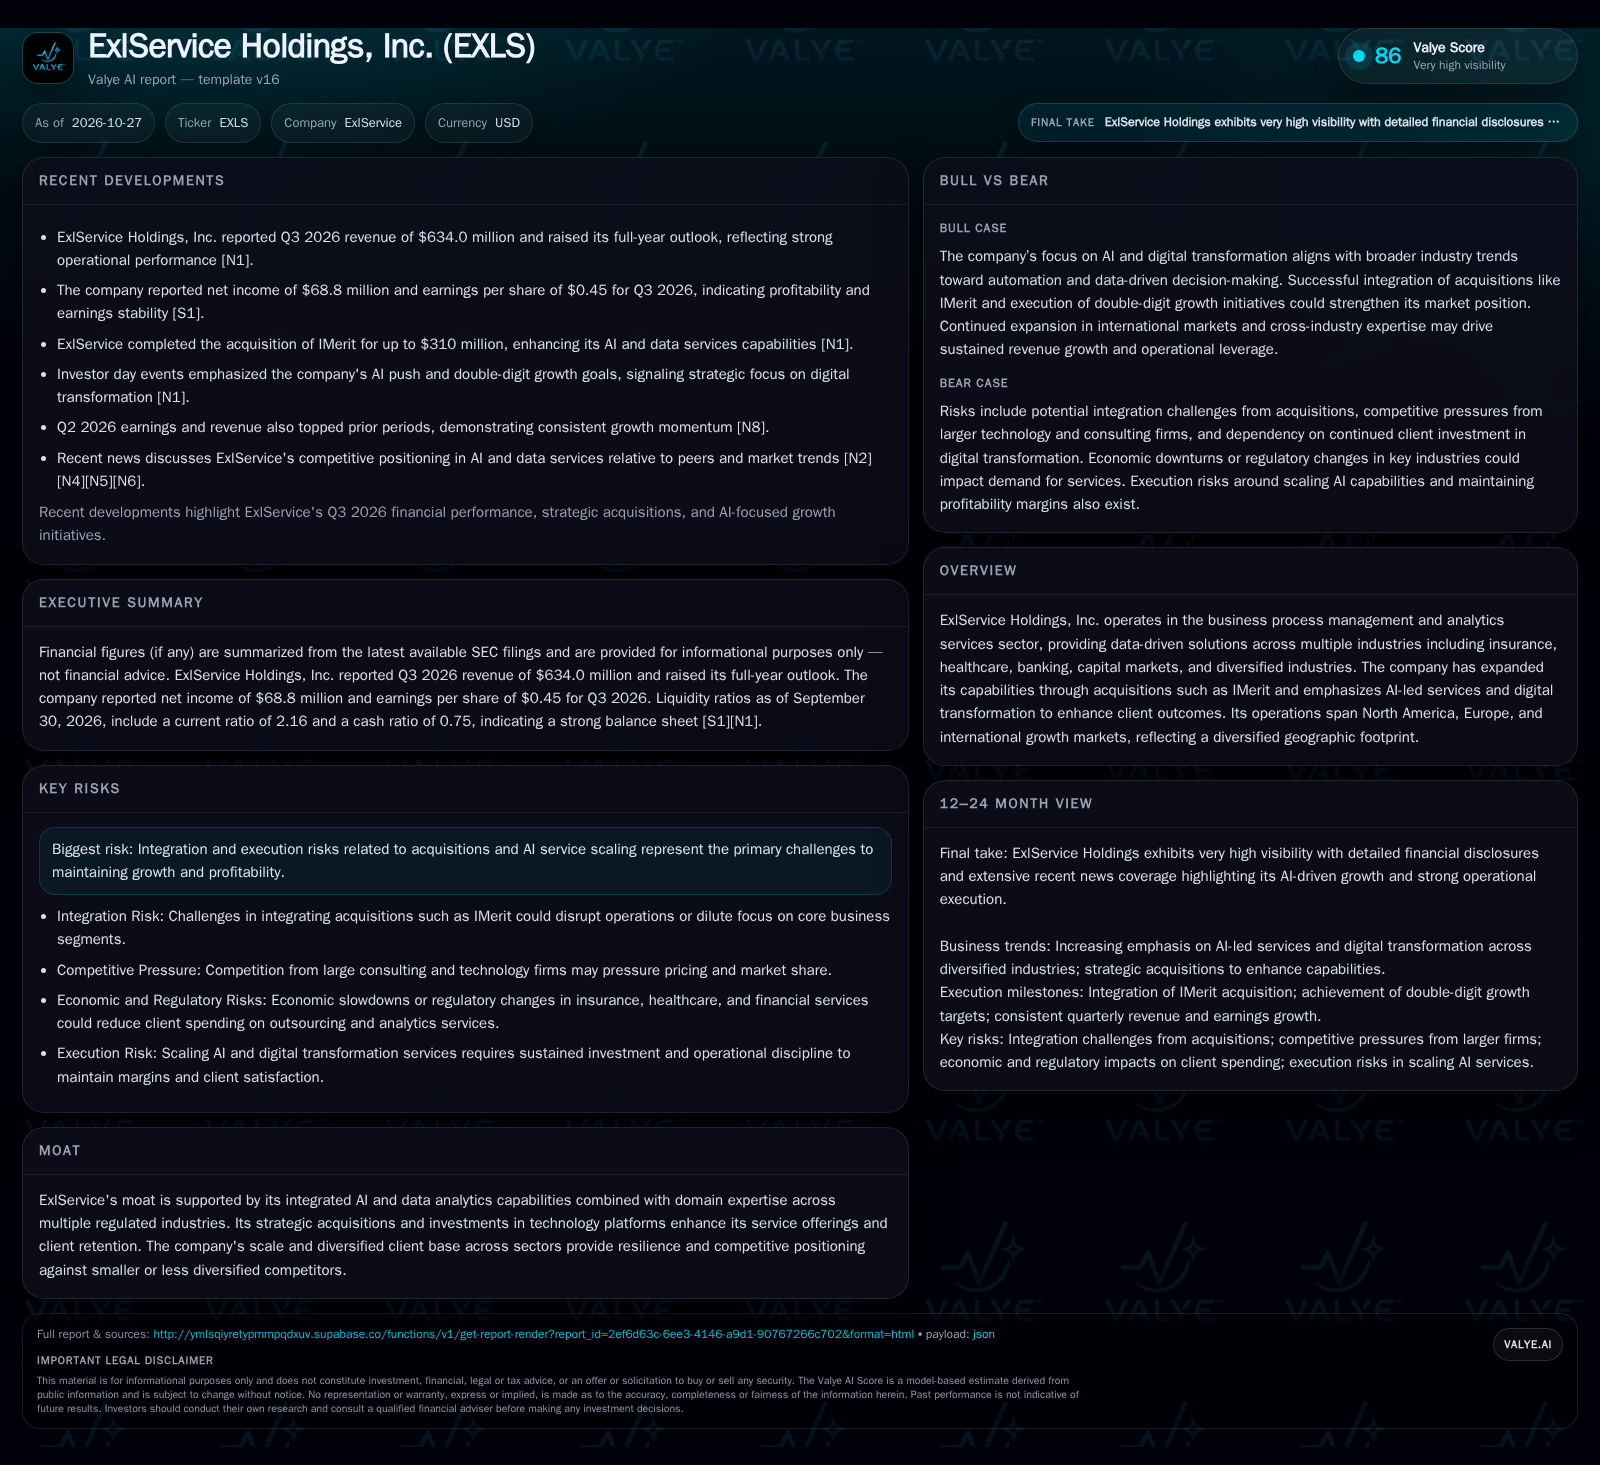
ExlService Holdings delivered robust Q3 2026 results, raising its outlook with $634 million in revenue and $68.8 million in net income. The company’s strategic emphasis on AI and digital transformation, combined with a diverse industry footprint and recent acquisitions, positions it well for continued growth. However, integration risks, execution on AI scaling, and competitive threats from larger technology and consulting firms remain critical variables for its long-term trajectory. Monitoring client adoption of new digital offerings, margin trends, and the success of cross-segment expansion will be key to evaluating the sustainability of current momentum. [S1] [N1] [N4] [N5] [N6]
ExlService Holdings, Inc. is riding a wave of strong operational performance, reporting $634 million in Q3 2026 revenue and lifting its full-year outlook. The company’s strategy hinges on expanding AI and data-driven services across a wide base of regulated industries, while leveraging acquisitions like IMerit to deepen technological capabilities. With a reported balance sheet position and clear emphasis on digital transformation, ExlService is seeking to convert its diversified footprint and sectoral expertise into enduring growth. The critical question is whether these investments and strategic bets can deliver sustainable competitive advantages amid intensifying industry competition and the inherent complexities of scaling AI-driven solutions. [S1] [N1] [N4] [N5] [N6]
Recent Results, Outlook, and Strategic Moves Shape the Investment Narrative
ExlService Holdings reported $634 million in revenue for Q3 2026, accompanied by net income of $68.8 million and earnings per share of $0.45. This performance prompted management to raise its full-year revenue outlook, marking another quarter of operational outperformance. The company’s liquidity position is notable, with $154.1 million in cash and $178.6 million in short-term investments, and a current ratio of 2.16 as of September 30, 2026. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. Recent acquisitions, such as IMerit, are designed to accelerate capabilities in AI and data-driven services, aligning with management’s push for double-digit growth and enhanced digital transformation offerings. The most material facts are the sustained top- and bottom-line growth, improved outlook, and the company’s emphasis on scaling AI-centric solutions to maintain momentum. [S1] [N1] [N4] [N5] [N6]
How ExlService Monetizes Data, AI, and Digital Transformation Across Verticals
ExlService generates revenue primarily by delivering business process management, analytics, and digital transformation solutions to clients across insurance, healthcare, banking, capital markets, and other industries. Its business model typically involves multi-year service contracts, project-based consulting, and increasingly, the deployment of AI-powered platforms and analytics services. As clients seek to automate processes and leverage data for decision-making, ExlService’s value proposition shifts from traditional labor arbitrage toward outcome-based and technology-enabled solutions.
Revenue mix is likely evolving toward higher-margin, IP-rich offerings as AI and automation gain traction, but the company still faces the challenge of balancing fixed investments in technology with variable client demand. Operating leverage could expand if ExlService successfully scales digital and AI-led services, as these tend to exhibit lower marginal costs compared to labor-intensive operations. However, capital needs remain significant, particularly for integrating acquired technology, developing proprietary platforms, and maintaining compliance in regulated sectors. Margin expansion will depend on the pace of client adoption, pricing power in differentiated services, and the ability to cross-sell digital solutions across its diversified client base.
Defending Share in a Crowded Field of Tech and Consulting Giants
ExlService operates in a highly competitive environment, facing direct competition from large global IT consultancies, business process outsourcing firms, and a growing cohort of specialized AI/data analytics providers. Its competitive advantages stem from domain expertise in regulated industries, integrated AI and data analytics capabilities, and a diversified client portfolio that provides resilience against sector-specific downturns.
However, the company is pressured by larger technology and consulting players with greater resources for R&D, broader solution portfolios, and deeper enterprise relationships. The ability to maintain pricing power, retain key clients, and stay ahead on technology adoption cycles will be tested as the market for AI-enabled services matures. Substitution risk also exists as clients weigh insourcing, automation, or alternative digital platforms. ExlService’s recent acquisitions and investments in proprietary technology are steps toward differentiation, but the sustainability of these advantages will hinge on execution and continued innovation. [N4] [N5] [N6]
AI-Led Transformation Gains Traction and Margin Expansion Follows
If ExlService successfully executes on its AI and digital transformation agenda, the company could capture a larger share of client spending as enterprises accelerate automation and data-driven decision-making. The integration of acquisitions like IMerit may enable ExlService to deliver more sophisticated, higher-value services, supporting both revenue growth and gross margin expansion. Successful cross-selling of AI-led offerings to legacy clients, combined with new client wins in international growth markets, could drive double-digit top-line growth and improved operating leverage.
Confirmation of this scenario would come from continued sequential revenue acceleration, disclosure of rising digital/AI revenue as a share of the mix (if provided), and sustained or expanding EBITDA margins. Additional evidence would include client case studies demonstrating successful digital transformations, and the announcement of new, large-scale contracts centered on AI or analytics solutions. Conversely, if revenue growth slows, digital/AI initiatives fail to scale, or margin improvement stalls, this would falsify the bull case.
Diversification Offsets Headwinds, but Margin Gains Remain Incremental
The most plausible outcome is that ExlService maintains steady growth by leveraging its diversified industry exposure and expanding AI-led offerings, but faces ongoing integration and competitive challenges that limit outsized margin expansion. Revenue growth may remain in the high single to low double digits as existing clients incrementally adopt new digital services, while traditional BPO contracts provide a stable base.
Margins could improve modestly as the mix shifts toward higher-value digital and analytics services, but wage inflation, technology investment, and integration costs from recent acquisitions may temper gains. Evidence supporting this scenario would include continued quarterly revenue and earnings growth, stable or modestly rising operating margins, and successful but gradual expansion of digital service adoption. Signs that would challenge this scenario include abrupt margin compression, integration setbacks, or a slowdown in new business wins.
Integration Pains, Competitive Losses, and Slower Digital Adoption Undercut Growth
In an adverse case, ExlService could face meaningful setbacks if recent acquisitions prove difficult to integrate, leading to operational disruption and diluted focus on core business lines. Heightened competition from larger technology and consulting firms could erode pricing and market share, particularly if clients consolidate spending with broader solution providers or accelerate insourcing.
A macroeconomic slowdown or regulatory change in key verticals such as insurance or healthcare could dampen client demand for outsourced and digital services, exposing the company’s cost base and pressuring margins. Early warning signs for this scenario would include missed revenue or earnings targets, negative client retention trends (if disclosed), or publicized integration failures.
Testing the Durability of ExlService’s Digital Ambitions and Industry Diversification
The share of revenue derived from AI-led and digital transformation services (if disclosed), to assess progress on strategic priorities.
Client retention rates and renewal trends, especially in insurance, healthcare, and banking verticals—a useful metric if provided.
Gross and operating margin progression, as an indicator of successful migration toward higher-value, technology-enabled offerings.
Integration milestones and realized synergies from recent acquisitions such as IMerit; disclosures on cost savings or cross-selling success would help test the thesis.
Pace of new client wins and expansion into international growth markets, as evidence of competitive positioning and geographic diversification.
Level and growth of R&D or technology investment, to evaluate the sustainability of innovation and digital capability development.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments