
Femasys: Regulatory Advances and Commercial Partnerships Reshape the Fertility Care Landscape
With recent FDA milestones and European expansion, Femasys is positioned at the intersection of innovation and execution risk in reproductive health.
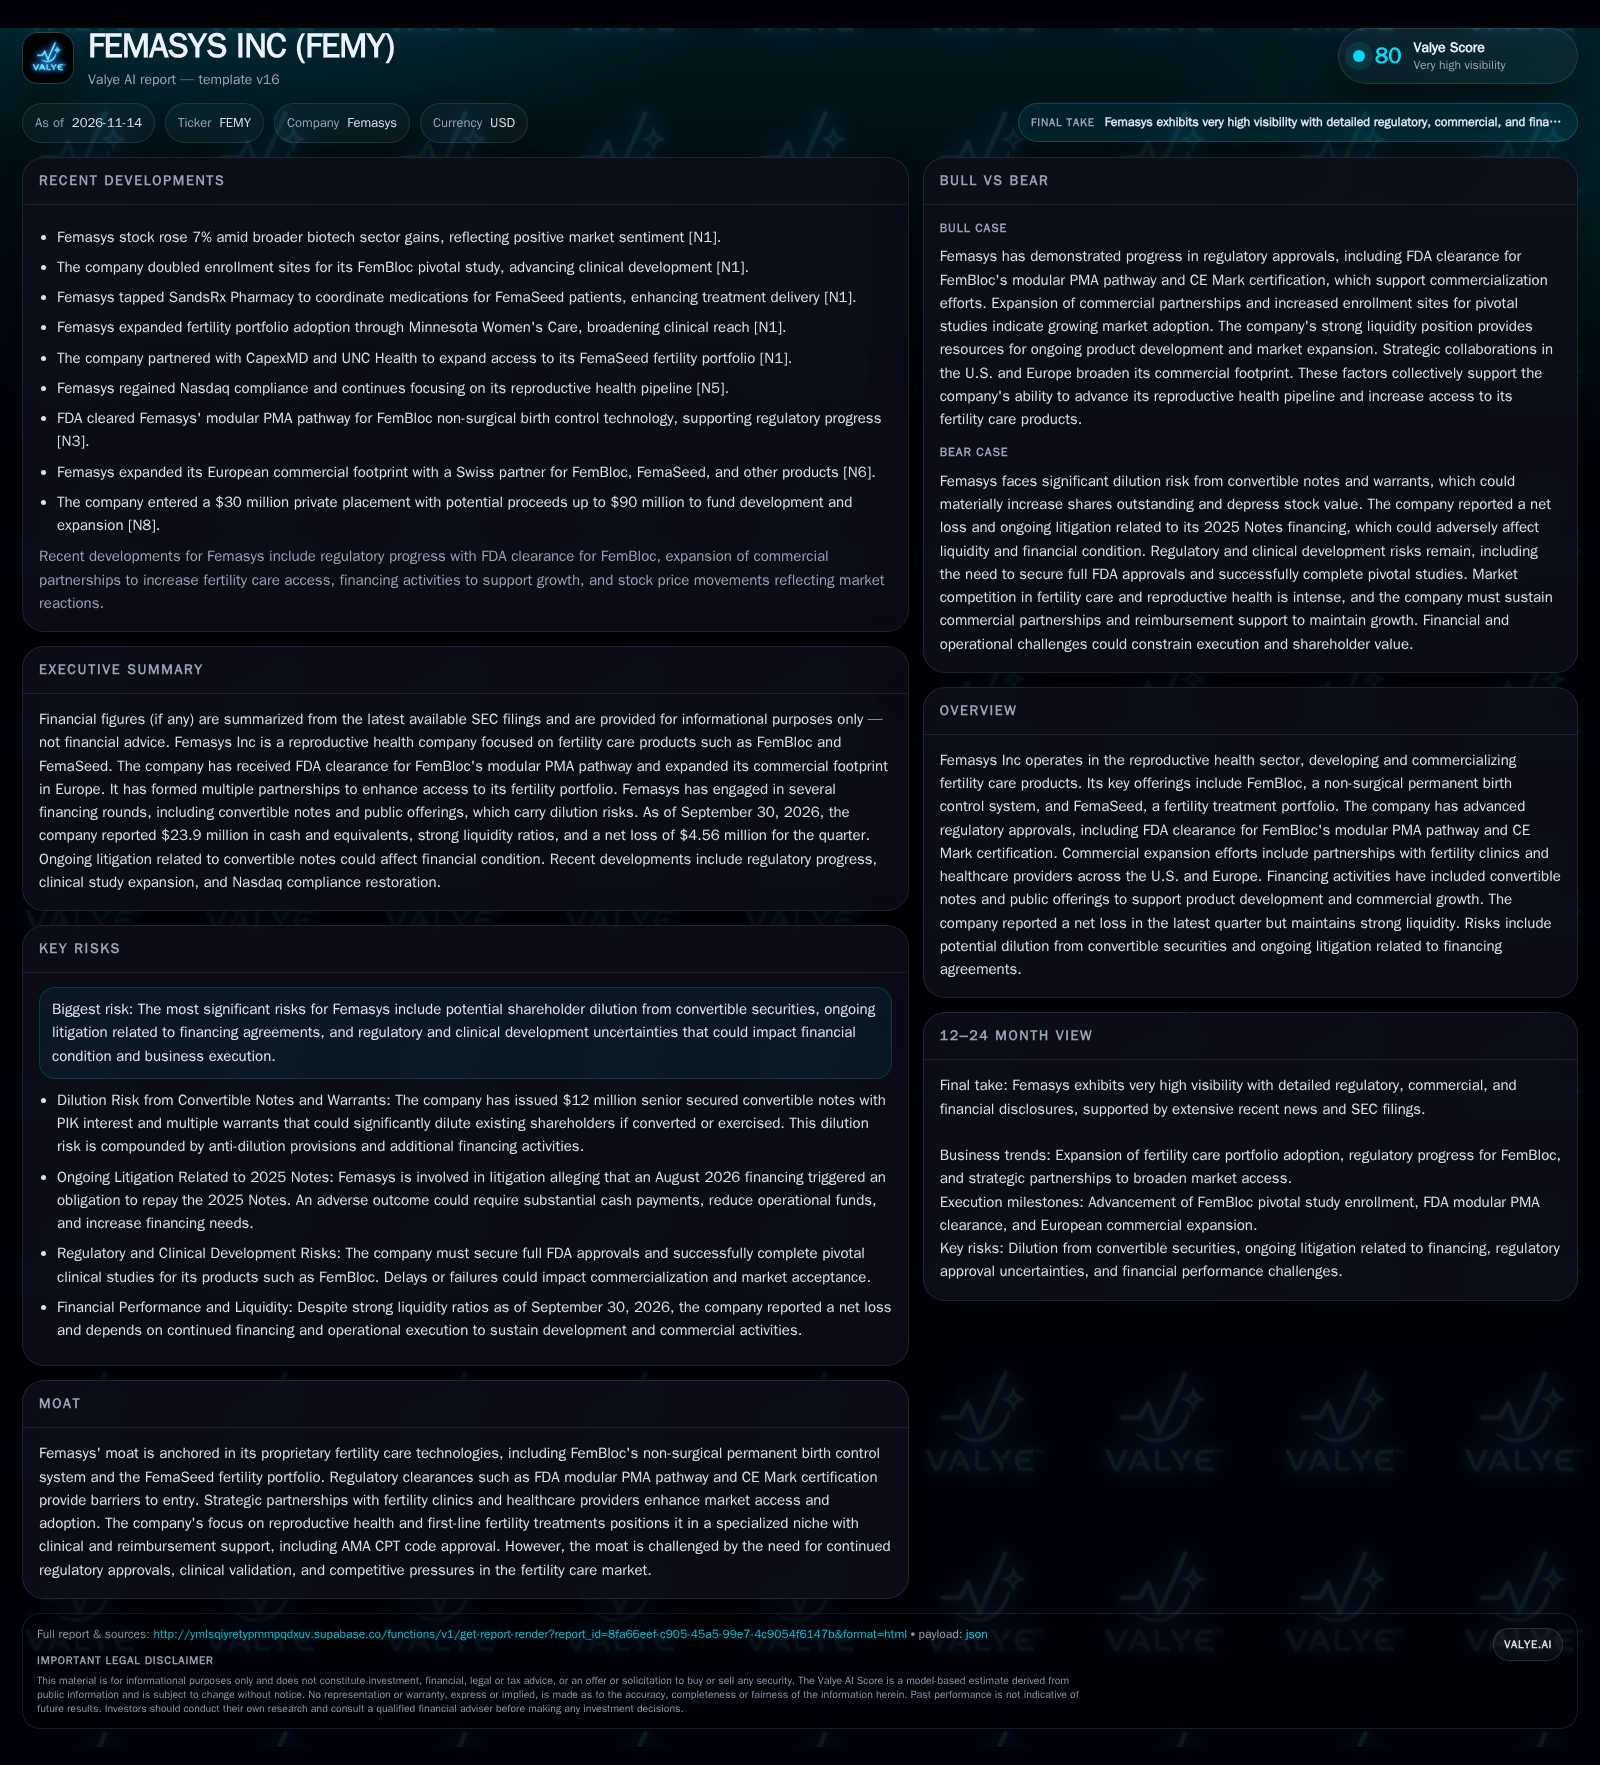
Femasys has secured FDA clearance for FemBloc’s modular PMA pathway and expanded its commercial footprint in Europe and the U.S. through new partnerships. The next phase will test whether Femasys can convert its pipeline and partnerships into sustainable commercial traction and defend its niche against entrenched rivals.
Femasys Inc. stands at a crucial inflection point in reproductive health, leveraging regulatory progress and commercial partnerships to drive adoption of its FemBloc and FemaSeed portfolios. The company’s recent FDA clearance for FemBloc’s modular PMA pathway and expanded European presence via a Swiss partner highlight its momentum and ambition. Yet, with persistent net losses, looming dilution from convertible notes, and pending litigation, Femasys must now prove that its innovation and access strategy can translate into commercial durability and defendable market share in an increasingly competitive fertility care sector.
Recent FDA Clearance, European Expansion, and Clinical Progress Define the Current Moment
Femasys recently secured FDA clearance for the modular PMA pathway for FemBloc, its non-surgical permanent birth control technology, marking a significant milestone toward potential U.S. approval and commercialization [S2]. The company has also expanded its commercial footprint in Europe through a partnership with a Swiss distributor, providing access to new markets for FemBloc, FemaSeed, and related products [N6]. [N1] These developments collectively put Femasys in a position to potentially transition from technology validation toward commercial scaling, but the next phases will test both its execution capacity and its ability to convert regulatory and partnership momentum into revenue traction.
How Femasys’ Business Model Could Capture Value in Reproductive Health
Femasys’ economics are shaped by the interplay of regulatory milestones, clinical adoption, and channel partnerships. The company’s core products—FemBloc and FemaSeed—address high-need niches: non-surgical permanent contraception and fertility enhancement, respectively. If FDA approval for FemBloc is achieved, Femasys could tap a large addressable market of women seeking alternatives to surgical sterilization or hormonal birth control. Commercialization would likely follow a B2B2C model, with sales to fertility clinics, OB/GYN practices, and potentially direct-to-patient distribution via specialty pharmacies. Pricing for such innovative procedures is typically at a premium to legacy offerings, but payer reimbursement is essential to drive adoption beyond cash-pay segments. The recent AMA CPT code approval for FemaSeed ITI could support reimbursement, but payer uptake and procedure coding lags are common hurdles.
Femasys’ cost structure is expected to be fixed-heavy in the near term, given R&D, regulatory, and clinical trial investments. As the installed base of clinics and providers grows, operating leverage could emerge, especially if manufacturing is scalable and distribution is partner-driven. However, gross margins will depend on product mix (devices, consumables, procedure kits), pricing discipline, and potential volume-based discounts to large clinic networks. The need for ongoing clinical evidence and education may keep SG&A elevated relative to mature medtech peers. Capital needs remain material, as evidenced by recent financings and the use of convertible notes. Dilution from convertible securities and warrants presents a structural cost to equity holders and could weigh on per-share economics if revenue inflection is delayed.
Defending a Niche: Femasys’ Edge and the Pressures of a Crowded Fertility Market
Femasys operates in a highly competitive reproductive health landscape, where both device manufacturers and pharmaceutical companies vie for clinic shelf space and procedural volume. The company’s advantage lies in its proprietary, non-surgical approach with FemBloc and its targeted fertility solutions with FemaSeed. Regulatory clearances (including the modular PMA pathway and CE Mark) create temporary barriers, while AMA CPT code approval could facilitate payer adoption and provider interest.
However, counterforces are formidable: established device makers offer proven sterilization and fertility products, many with entrenched clinical relationships and reimbursement histories. Substitutes include surgical sterilization, hormonal contraceptives, and assisted reproductive technologies—each with its own adoption inertia. Femasys’ position will hinge on demonstrating clinical efficacy, safety, provider ease-of-use, and cost-effectiveness. The company’s partnerships with clinics, specialty pharmacies, and financing providers are a route to distribution breadth, but sustaining and expanding these relationships, especially in the face of larger competitors with broader portfolios, will be a constant challenge. Switching costs for clinics can be moderate if training and workflow integration are streamlined, but payer policies and patient acceptance will ultimately determine the pace of adoption.
If Regulatory Wins and Partnerships Drive Revenue Inflection
The most favorable scenario for Femasys unfolds if FemBloc achieves full FDA approval and FemaSeed realizes broad payer reimbursement on the back of its new CPT code. In this case, early clinical sites would validate strong efficacy and safety, fueling positive word-of-mouth and additional clinic adoption. European expansion through the Swiss partner could accelerate, leveraging regulatory harmonization and local KOL advocacy. Commercial partnerships with leading U.S. fertility centers would enable rapid scaling, and specialty pharmacy channels could facilitate direct patient access for FemaSeed.
Evidence confirming this scenario would include accelerating sequential revenue growth, a rising installed base of provider customers, and positive clinical data from pivotal studies. Additional signals might be announcements of new payer coverage or inclusion in major clinical guidelines, as well as expansion of international distribution partnerships. If cash burn moderates alongside revenue growth, the risk of further dilution would recede, strengthening the long-term equity case.
Execution Challenges and a Gradual Climb Toward Commercial Validation
The most plausible outcome is a period of incremental progress, with Femasys advancing regulatory filings and clinical data for FemBloc, while seeking to convert initial partnerships into repeat revenue. Adoption may be slow as clinics evaluate real-world outcomes and payers assess coverage policies for both FemBloc and FemaSeed. The company’s reported liquidity position provides time to reach key milestones, but recurring net losses are likely until a critical mass of provider adoption is achieved.
Confirmation of this scenario would be steady—but not accelerating—growth in the number of clinical sites, modest sequential revenue gains, and continued news of regulatory or reimbursement advances. Signs that would challenge this base case include delays in pivotal study completion, adverse clinical outcomes, or material setbacks in payer coverage or provider partnership retention. Dilution from convertible securities may continue if revenue momentum lags funding needs.
Dilution, Litigation, and Regulatory Setbacks Could Derail Commercial Momentum
In a negative scenario, Femasys could face significant dilution as convertible notes and warrants are exercised to fund ongoing losses, depressing per-share value and potentially undermining market confidence [S2]. If ongoing litigation over the 2025 Notes results in a material cash outflow or impairs the company’s ability to raise additional capital, operational flexibility could be compromised. Delays or negative outcomes from the FemBloc pivotal study, or failure to secure final FDA approval, would stall commercialization and erode the company’s competitive position.
Evidence supporting this scenario would include persistent or widening net losses, an adverse litigation outcome requiring a cash payment, sequential declines in cash or liquidity ratios, or a lack of new clinical or commercial partnerships. Regulatory setbacks—such as FDA requests for additional data or safety concerns—would further impede adoption. In this environment, Femasys could be forced to seek dilutive financing or strategic alternatives.
Milestones That Will Determine Whether Femasys Can Sustain Its Momentum
Pivotal study enrollment rates and progress toward completion for FemBloc—if disclosed—will be critical for timing regulatory submissions and approval.
FDA approval status and feedback on FemBloc’s modular PMA pathway will confirm regulatory risk and timeline.
Trends in sequential revenue growth, especially from new clinic partnerships and European sales, would help test commercial adoption.
Updates on payer reimbursement for FemaSeed and FemBloc, including payer coverage decisions and actual procedure claims, would clarify the path to broader adoption.
Material developments in ongoing litigation related to the 2025 Notes, including any required cash payments or settlements, could impact operational runway.
Conversion activity or exercises of convertible notes and warrants—a useful metric would be the change in fully diluted share count over time.
Retention and expansion of key commercial partnerships, such as with SandsRx Pharmacy, CapexMD, and European distributors, will indicate the stickiness and scalability of the distribution model.
Gross margin trends—if disclosed—would reveal the impact of scaling, product mix, and pricing discipline as commercialization advances.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments