
Gevo’s Carbon Credit-Driven Model: Incentive Leverage, Execution Risks, and the Path to Scalable Profitability
Gevo, Inc. is navigating the renewable fuels sector by tightly integrating government incentives—especially carbon credits and 45Z tax credits—into its business model. While the company posts positive net income and maintains reported liquidity position, its long-term trajectory remains highly sensitive to regulatory frameworks and operational scaling.
Gevo’s latest financials show positive net income and reported liquidity position, but its future hinges on the continued availability and value of carbon credits and 45Z tax incentives. The company’s strategy involves leveraging these government programs to drive EBITDA, yet its limited recent revenue disclosure signals ongoing commercialization challenges. Execution on scaling production and monetizing carbon markets—not just incentive capture—will determine whether Gevo can move from policy-dependent profitability to more durable, market-driven growth.
Gevo, Inc. stands at the intersection of renewable fuels and carbon market monetization, posting a positive net income in its latest quarter and maintaining a reported liquidity position. The company’s near-term profitability and EBITDA guidance, however, are fundamentally anchored to government incentives—most notably the 45Z tax credit and carbon credits. With a newly appointed Chief Carbon Officer and a clear strategic tilt toward carbon markets, Gevo’s model is both differentiated and exposed: regulatory shifts or execution setbacks could rapidly alter its financial outlook. The core question is whether Gevo can convert incentive-driven gains into lasting market-driven profitability.
Recent Financials and Strategic Moves Define Gevo’s Present Outlook
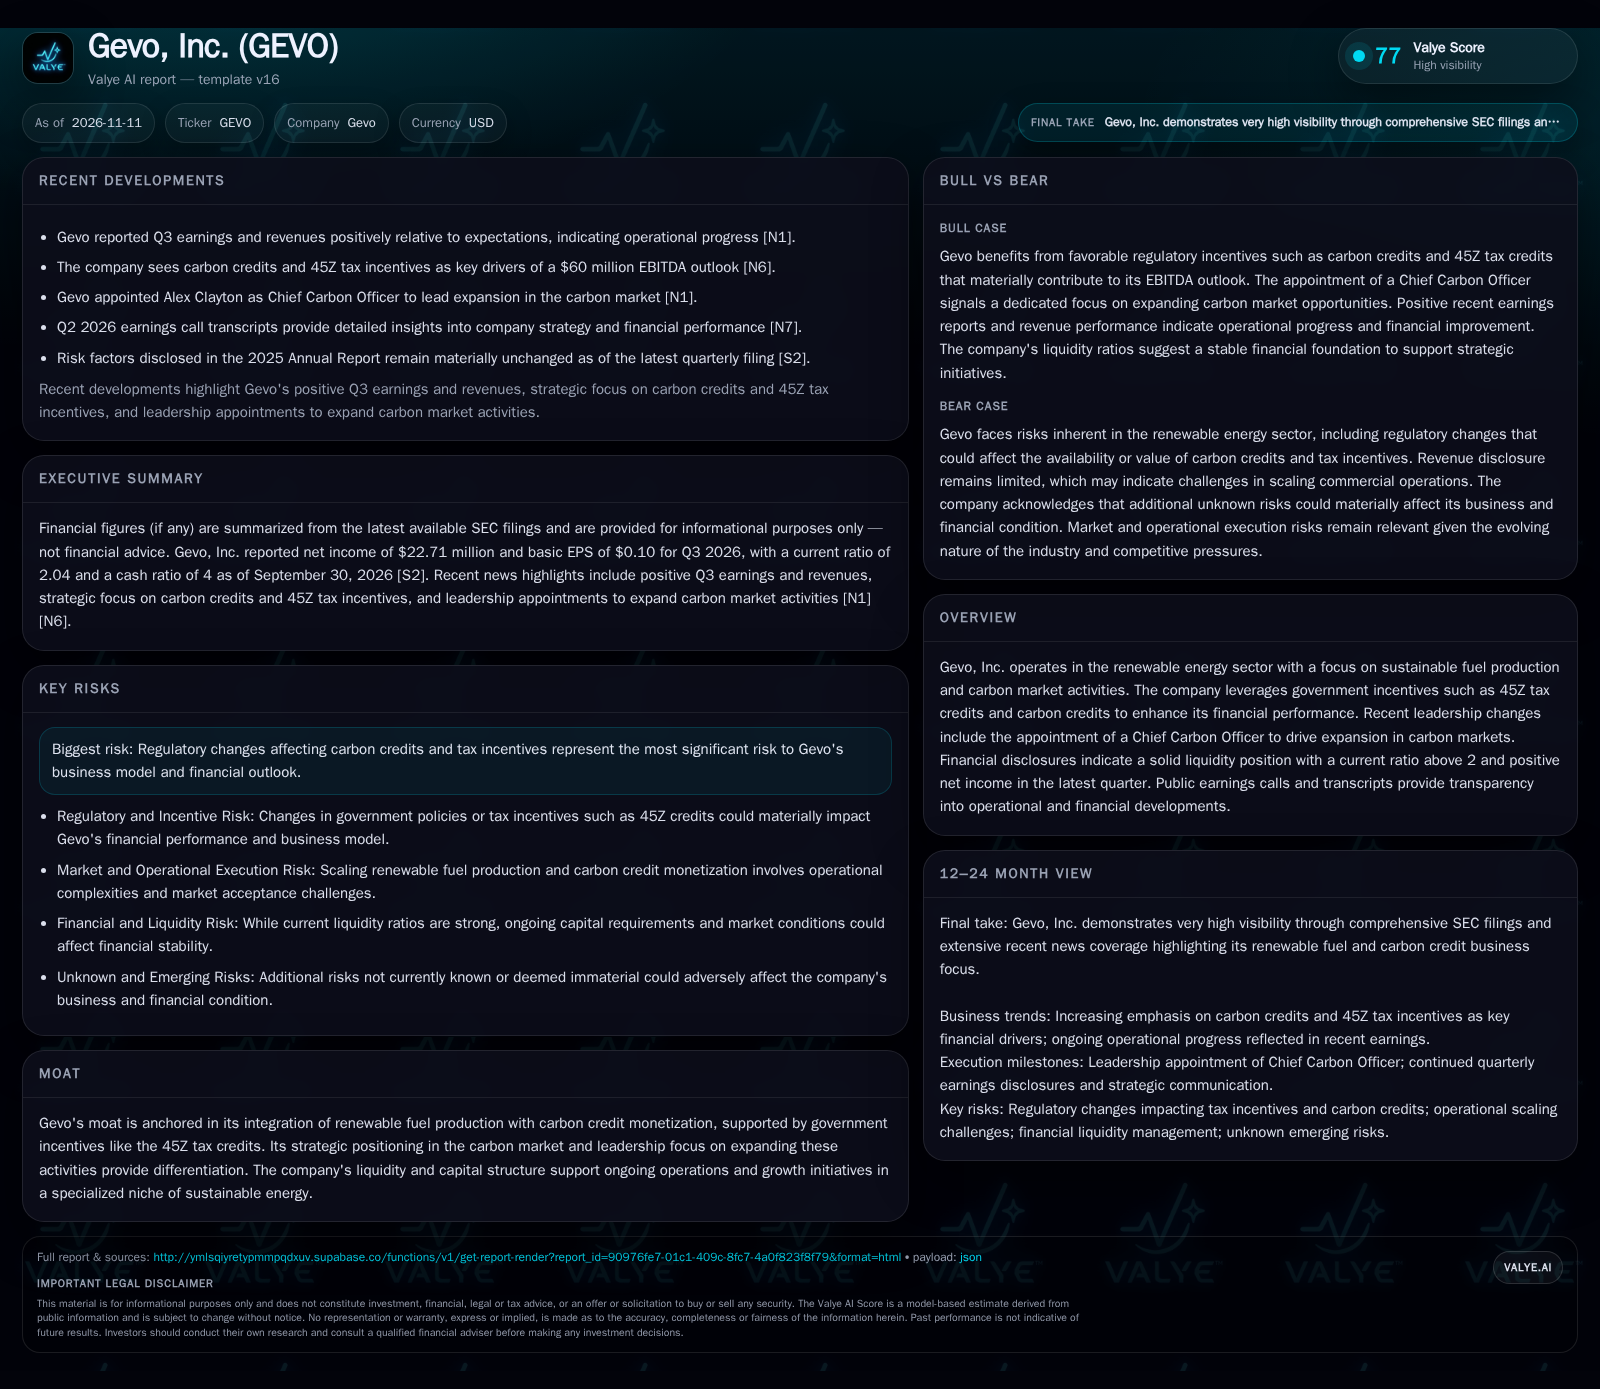
Gevo reported net income of $22.71 million and basic earnings per share of $0.10 for the quarter ending September 30, 2026, with a current ratio of 2.04 and a cash ratio of 4, indicating a reported liquidity position at the end of Q3 [S2]. This is a notable financial improvement for a company in the capital-intensive renewable fuels space, where positive net income is relatively rare among peers at this stage. However, revenue disclosure remains limited, with the most recently reported figure ($309,000 in Q3 2022) highlighting either early-stage commercialization or a reliance on nontraditional revenue streams [S2].
A major development is Gevo’s explicit focus on carbon credits and 45Z tax incentives, which are now central to its EBITDA outlook—a $60 million figure was recently referenced in this context [N6]. The appointment of a Chief Carbon Officer signals a strategic commitment to expanding activities in carbon markets, reinforcing the company’s alignment with regulatory and incentive-driven value creation.
How Incentives and Carbon Markets Shape Gevo’s Revenue Model
Gevo’s business economics are defined by the interplay between renewable fuel production and the monetization of carbon credits and tax incentives. The company’s positive net income and EBITDA guidance appear to be driven less by large-scale fuel sales and more by the successful capture and monetization of government incentives, such as the federal 45Z tax credits and state/federal carbon credit programs [N6]. This structure means that Gevo’s revenue mix is likely heavily weighted toward high-margin, policy-driven streams rather than traditional, volume-based fuel sales.
The economics of this model are attractive as long as incentives persist: carbon credits can provide outsized returns relative to the actual volume of renewable fuels produced, while 45Z credits directly bolster EBITDA. Fixed costs, including plant operations and compliance, are significant, but the incremental profit from credits/tax incentives can drive operating leverage if production scales. However, scaling production to meaningfully increase fuel sales and recurring credit generation would require substantial capital investment and operational execution. The model’s capital needs are thus twofold: ongoing working capital for operations and larger, episodic investments for capacity expansion—both of which are at risk if incentives change or expire.
Strategic Differentiation Amid Policy-Driven Competition
Gevo’s competitive positioning is tightly linked to its ability to extract value from regulatory incentives and carbon markets. In the renewable fuels landscape, competitors include both specialized biofuel startups and established energy firms diversifying into low-carbon fuels. Many of these peers are also seeking to maximize carbon credit and tax incentive monetization, making the competitive field highly sensitive to regulatory arbitrage and innovation in credit generation.
Gevo’s appointment of a Chief Carbon Officer and its explicit strategy around carbon credits suggest a more aggressive approach than some traditional biofuel players, potentially allowing it to capture a larger share of available incentives or to innovate in credit stacking and market participation. However, this focus also exposes Gevo to substitution risk if competitors develop more cost-effective or scalable pathways to the same credits, or if technological advances (such as direct air capture or next-gen synthetic fuels) shift the credit allocation landscape. The company’s moat is thus more regulatory and process-driven than rooted in proprietary technology or irreplaceable assets.
Accelerated Credit Monetization and Policy Tailwinds Drive Outsized Profitability
In a favorable scenario, Gevo successfully scales renewable fuel production and deepens its integration with carbon markets, allowing it to maximize the volume and value of both carbon credits and 45Z tax incentives. Policy support remains stable or improves, creating a multi-year runway for high-margin, incentive-driven EBITDA. The appointment of a Chief Carbon Officer leads to innovative credit trading strategies and new market access, while operational execution keeps costs in check.
Confirmation of this scenario would come from several sources: a visible ramp-up in disclosed revenues from fuel sales and credit trading, consistent positive net income and high EBITDA margins, and further expansion of capacity or new long-term offtake agreements tied to credit monetization. Evidence would also include management commentary highlighting new or expanded regulatory programs, and possibly the announcement of multi-year contracts or strategic partnerships to secure feedstock and market access.
Sustained Incentive Reliance and Gradual Commercial Progress
The most plausible path is that Gevo continues to generate positive net income primarily through carbon credits and 45Z tax incentives, with slow but steady improvement in renewable fuel production and revenue disclosure. The regulatory environment remains broadly supportive, but incremental growth in fuel sales is constrained by capital requirements, operational complexity, or market adoption hurdles.
Confirmation would include stable or modestly increasing net income and EBITDA, continued reported liquidity position, and periodic updates on production milestones or new incentive programs. However, a lack of material growth in fuel sales, recurring limited revenue disclosure, or stagnation in new project announcements would suggest that the business remains fundamentally policy-dependent.
Regulatory Disruption or Execution Missteps Undermine the Model
A negative outcome could be triggered by adverse changes to 45Z tax credits, carbon credit valuation, or broader policy frameworks—whether through legislative action, administrative reinterpretation, or market-driven credit price declines. If incentive values fall or eligibility criteria tighten, Gevo’s main sources of profitability could erode rapidly, exposing the company’s limited underlying commercial scale.
Operationally, delays or failures in scaling fuel production, technology setbacks, or rising costs could further impair the ability to generate credits or meet incentive requirements. Evidence of this scenario would include a sharp reduction in net income, negative revisions to EBITDA outlook, explicit management warnings about policy risk, or a cash burn that outpaces available liquidity. Early warning signs might also be seen in sector-wide regulatory developments or credit-market volatility.
Milestones and Metrics That Will Test Gevo’s Incentive-Driven Thesis
Quarterly disclosure of renewable fuel production volumes—if disclosed—would clarify the extent to which operational scale is improving.
Breakdown of revenue sources, specifically the split between fuel sales, carbon credits, and tax incentives, would help test the sustainability of earnings.
Updates on the regulatory environment for 45Z tax credits and major carbon credit programs, including any legislative or administrative changes.
Announcements of new offtake agreements, long-term customer contracts, or strategic partnerships in carbon markets.
Visible increases in capital expenditures or project development activity, indicating a credible plan for expansion beyond current scale.
Earnings call commentary on the durability and predictability of carbon credit and tax incentive flows.
Material changes in liquidity or net income trends that would signal either positive operating leverage or emerging financial strain.
Appointment of additional specialized leadership (beyond the Chief Carbon Officer) or board members with expertise in carbon markets or regulatory affairs.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments