
Goldman Sachs’ Strategic Refocus: Institutional Strengths, Consumer Retrenchment, and the Stakes for Margin Resilience
Goldman Sachs is pivoting away from mass-market consumer finance to sharpen its focus on institutional banking, market-making, and wealth management.
The firm’s competitive advantage lies in global scale, integrated technology platforms, and deep client relationships, but it faces risks from market volatility, regulatory demands, and fintech disruption. The next phase hinges on execution in core segments and adapting to rapid changes in financial technology and regulation.
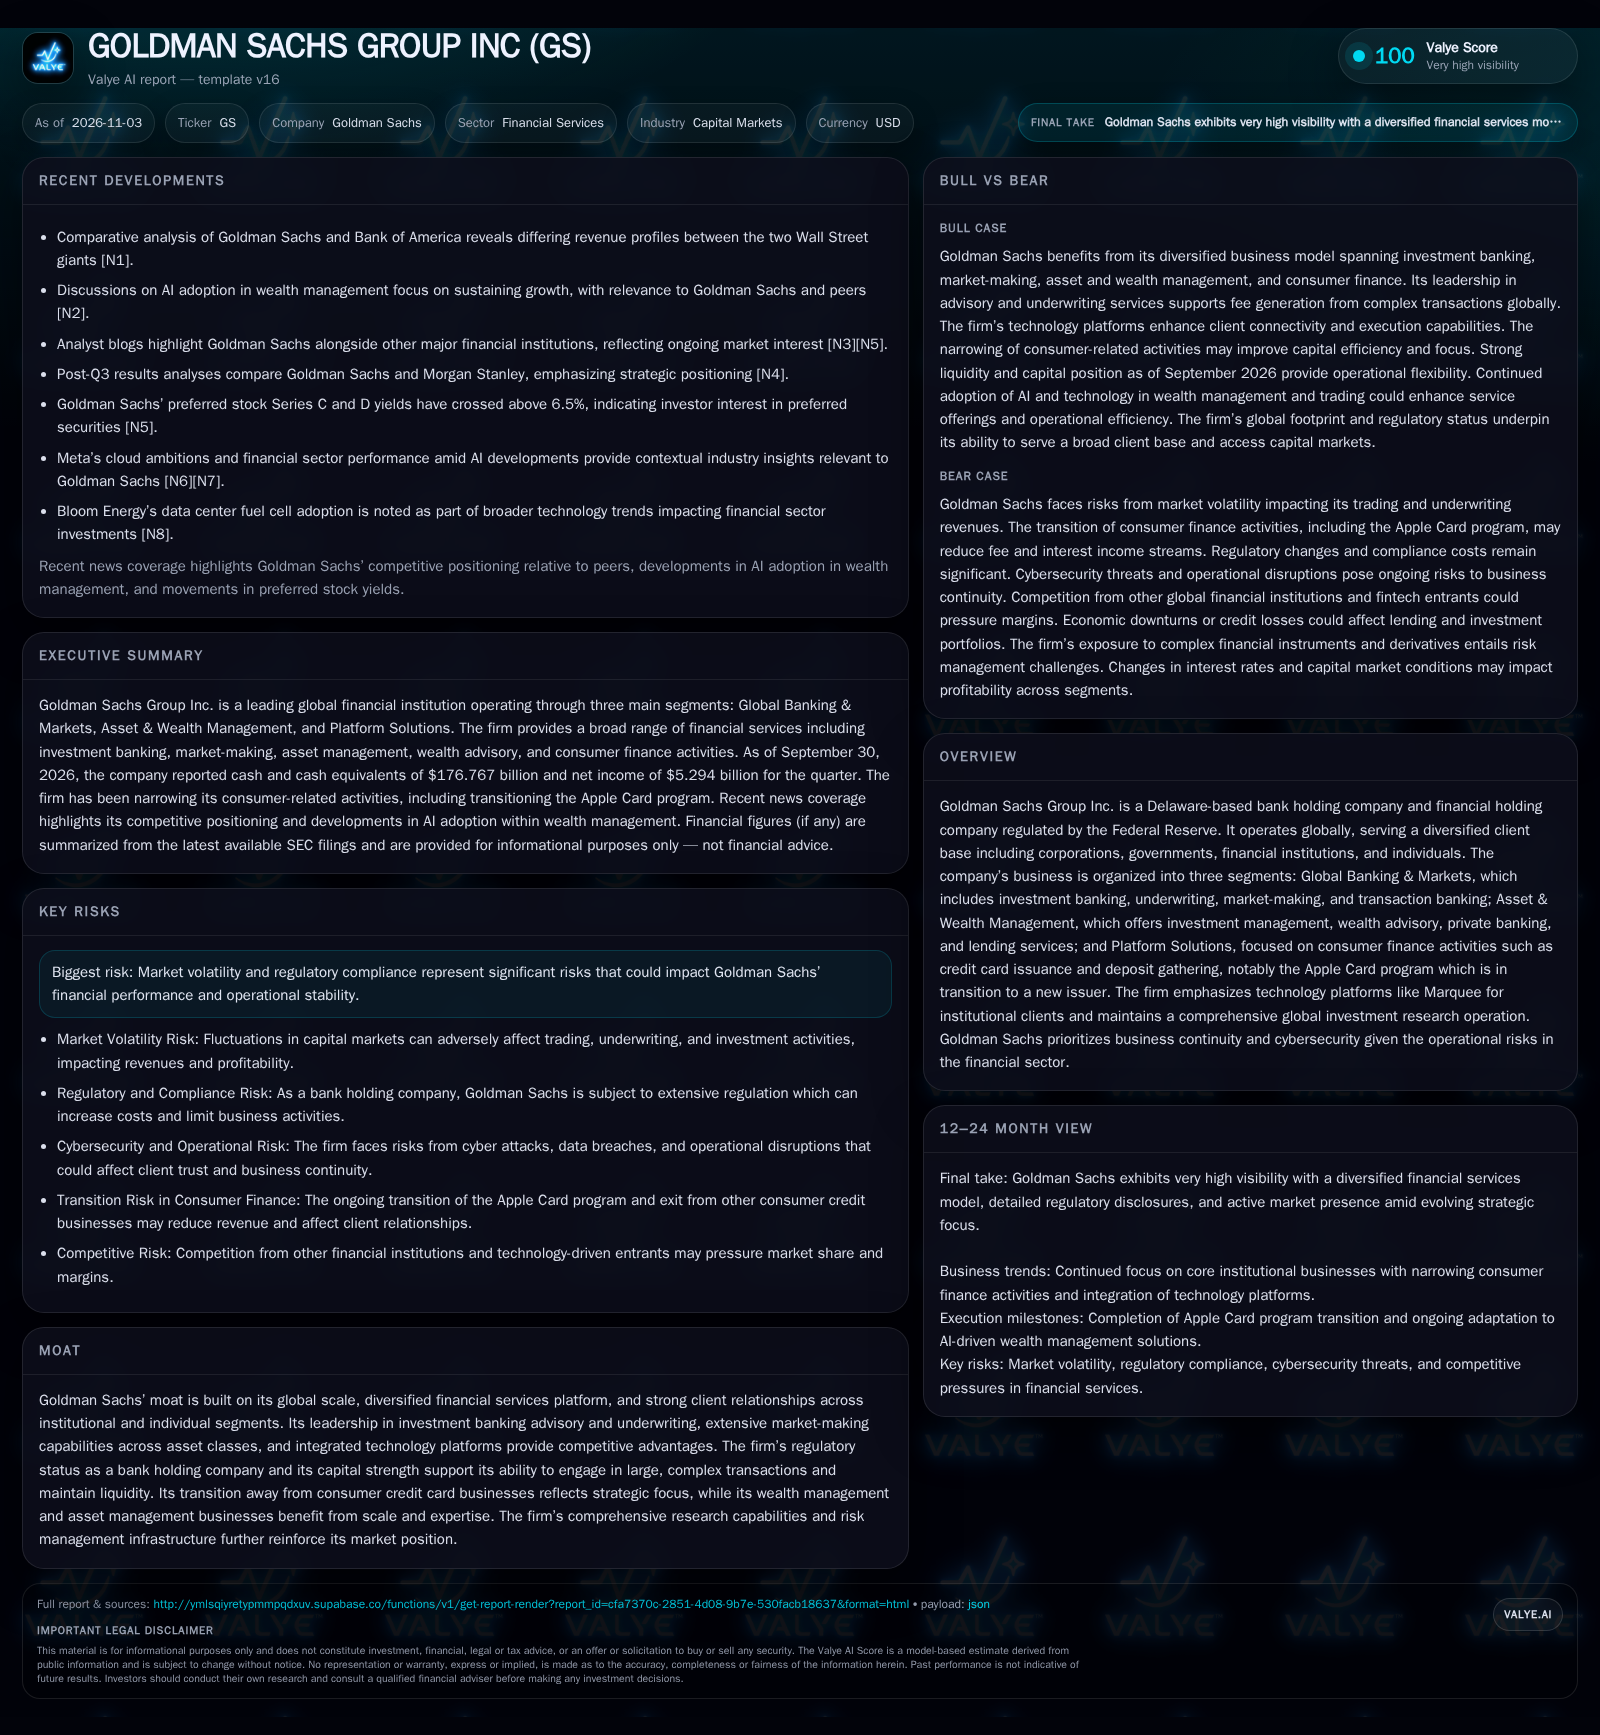
Goldman Sachs’ third quarter 2026 results underscore its enduring power as a global financial behemoth, even as it withdraws from direct consumer finance and doubles down on its institutional core. The firm’s $5.3 billion quarterly net income and nearly $177 billion in cash and equivalents highlight both operational resilience and a formidable war chest for navigating market turbulence. Yet, its retreat from the Apple Card and related consumer credit operations marks a pivotal shift in business model, raising questions about the durability of its competitive advantages as technology, regulation, and new entrants transform the financial landscape.
Goldman Sachs’ Latest Moves: Earnings Strength, Consumer Exit, and Capital Market Signals
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2] At the same time, Goldman is actively transitioning out of its mass-consumer credit card businesses—most notably, the Apple Card program, which is expected to be fully handed off to a new issuer within approximately 24 months from December 2025 [S1]. The firm’s preferred stock yields rising above 6.5% have also drawn attention, suggesting shifts in investor appetite for risk and the cost of capital [N5]. These developments collectively signal a decisive pivot toward institutional strengths while raising the stakes for execution in the core segments that now drive the business.
How Goldman Sachs Generates Value: Segment Economics and the Impact of Strategic Repositioning
Goldman Sachs’ business model is anchored in three main segments: Global Banking & Markets, Asset & Wealth Management, and, for the time being, Platform Solutions. Global Banking & Markets generates revenue through advisory fees, underwriting, market-making (spreads and commissions), and financing activities. These are typically high-margin, fee-based businesses but are sensitive to market volumes, volatility, and risk appetite. Asset & Wealth Management provides management and performance fees, earnings from proprietary investments, and lending income, offering a more recurring and less cyclical revenue stream, especially from ultra-high-net-worth and institutional clients. Platform Solutions—primarily consumer credit card issuance and deposit gathering—is in wind-down, which may reduce fee and interest income but could also improve capital efficiency and risk-adjusted returns.
Fixed costs in technology, compliance, and risk management are substantial, but the business is highly scalable, with incremental revenue often dropping meaningfully to the bottom line during periods of elevated activity. The firm’s ability to allocate capital dynamically across these segments is a source of potential operating leverage. However, as Goldman exits consumer finance, it will have to offset lost volume with deeper penetration and pricing power in institutional and wealth businesses, where competition—especially from larger banks and technology-driven players—is intense. Capital and funding requirements are significant, given regulatory constraints and the need to maintain liquidity buffers. The ability to monetize technology platforms like Marquee could open new, higher-margin revenue streams, but their commercial impact is still evolving.
Defending the Franchise: Institutional Moats, Digital Disruption, and Peer Pressures
Goldman Sachs’ competitive edge has historically rested on global reach, deep client relationships, and an integrated platform spanning advisory, trading, and asset management. Its technology investments—such as the Marquee platform for institutional analytics and execution—may provide some insulation against commoditization, but the firm faces formidable rivals among global banks, asset managers, and an expanding field of fintechs. The retreat from mass-market consumer finance removes a potential avenue for cross-selling and data acquisition but reduces exposure to lower-margin, higher-risk activities.
The firm’s scale and regulatory status enable it to participate in large, complex transactions that smaller or less well-capitalized competitors cannot match. However, regulatory compliance and capital requirements also act as a drag on returns and add complexity. Meanwhile, the adoption of AI and digitization by both incumbents and new entrants is eroding traditional moats in trading and wealth management. In this environment, Goldman’s ability to deliver differentiated advice, liquidity, and platform solutions—while managing risk—will be central to sustaining its franchise value.
Scenario: Technology-Enabled Advisory and Wealth Management Drive Margin Expansion
A favorable trajectory for Goldman Sachs would see its institutional and wealth management franchises deepening client penetration, increasing fee-based revenue, and leveraging technology to reduce costs and create new product offerings. AI-driven analytics and digital platforms could enhance both client service and operational efficiency, allowing Goldman to win share from less sophisticated peers and to command premium pricing for differentiated capabilities. If the transition out of consumer credit is managed smoothly, capital could be redeployed into scalable, high-return advisory, trading, and asset management activities.
Evidence for this scenario would include sustained or rising advisory and asset management fee growth, improved expense ratios despite ongoing technology investment, and successful commercialization of platforms like Marquee. Additional confirmation would come from client win disclosures, new mandates, or platform adoption metrics (if disclosed). This scenario could be falsified if fee revenue stagnates, technology spend fails to yield margin improvement, or if client attrition accelerates as digital competitors gain ground.
Institutional Core Delivers Solid Results, but Margin Gains Are Moderated by Market and Regulatory Headwinds
The most plausible outlook is that Goldman Sachs continues to generate strong, if volatile, earnings from its core Global Banking & Markets and Asset & Wealth Management segments. The exit from consumer finance trims some non-core revenues and risks, but the benefits to capital efficiency are offset by persistent market volatility, margin pressure from competitors, and the ongoing cost of regulatory compliance and technology upgrades. Trading and underwriting income will remain cyclical, wealth management will provide a more stable foundation, and fee growth will be solid but not explosive.
Confirmation of this scenario would be quarterly earnings that remain within recent historical ranges, margin trends that are stable or improving modestly, and limited signs of either major client attrition or disruptive new entrants capturing share. On the other hand, a sharp deterioration in fee revenue, inability to restrain expense growth, or major regulatory setbacks would challenge the base case.
Market Dislocation or Execution Missteps Erode Profitability
The adverse scenario centers on a combination of external shocks—such as a severe market downturn, credit events, or a regulatory clampdown—and internal execution risks, including a disorderly exit from consumer finance or failed technology investments. Under this scenario, trading and underwriting revenues could collapse, asset management flows reverse, and the firm could face rising credit losses or litigation costs. Increased capital requirements or cyber incidents could further constrain operational flexibility.
This scenario would be confirmed by sharply falling earnings, significant outflows from asset management, loss of major institutional mandates, or disclosure of regulatory or cyber events with material financial impact. Early warning signs might include spiking expense ratios, declining client engagement, or rising funding costs as reflected in preferred stock yields.
What Will Determine Goldman Sachs’ Long-Term Edge in a Shifting Financial Landscape?
Sustained advisory, underwriting, and trading fee growth in Global Banking & Markets—especially relative to peers—would indicate franchise resilience and pricing power.
Net asset flows and fee growth in Asset & Wealth Management are critical for recurring revenue and platform strength; a useful metric would be segment-level net new assets (if disclosed).
Progress on the transition and eventual exit from the Apple Card and other consumer credit programs will affect capital redeployment and risk profile; timely completion and minimal loss of deposit/funding relationships would be a positive signal.
Expense trends, particularly related to technology and compliance, should be monitored for evidence of operating leverage versus cost overruns.
Adoption rates and commercial traction for proprietary platforms such as Marquee—client usage metrics, transaction volumes, or new product launches—would help test the thesis that technology can drive differentiation.
Preferred stock and other funding cost metrics may offer early warning of market sentiment shifts or perceived risk in the capital structure.
Regulatory developments, enforcement actions, or material cyber events could rapidly alter the risk/return profile and should be closely watched.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments