
HNO International: Hydrogen Ambition Meets Acute Liquidity Pressure and Commercialization Hurdles
The company’s ability to transition from prototype deployments to commercial scale will depend on capital infusions, customer adoption, and the pace of hydrogen infrastructure buildout.
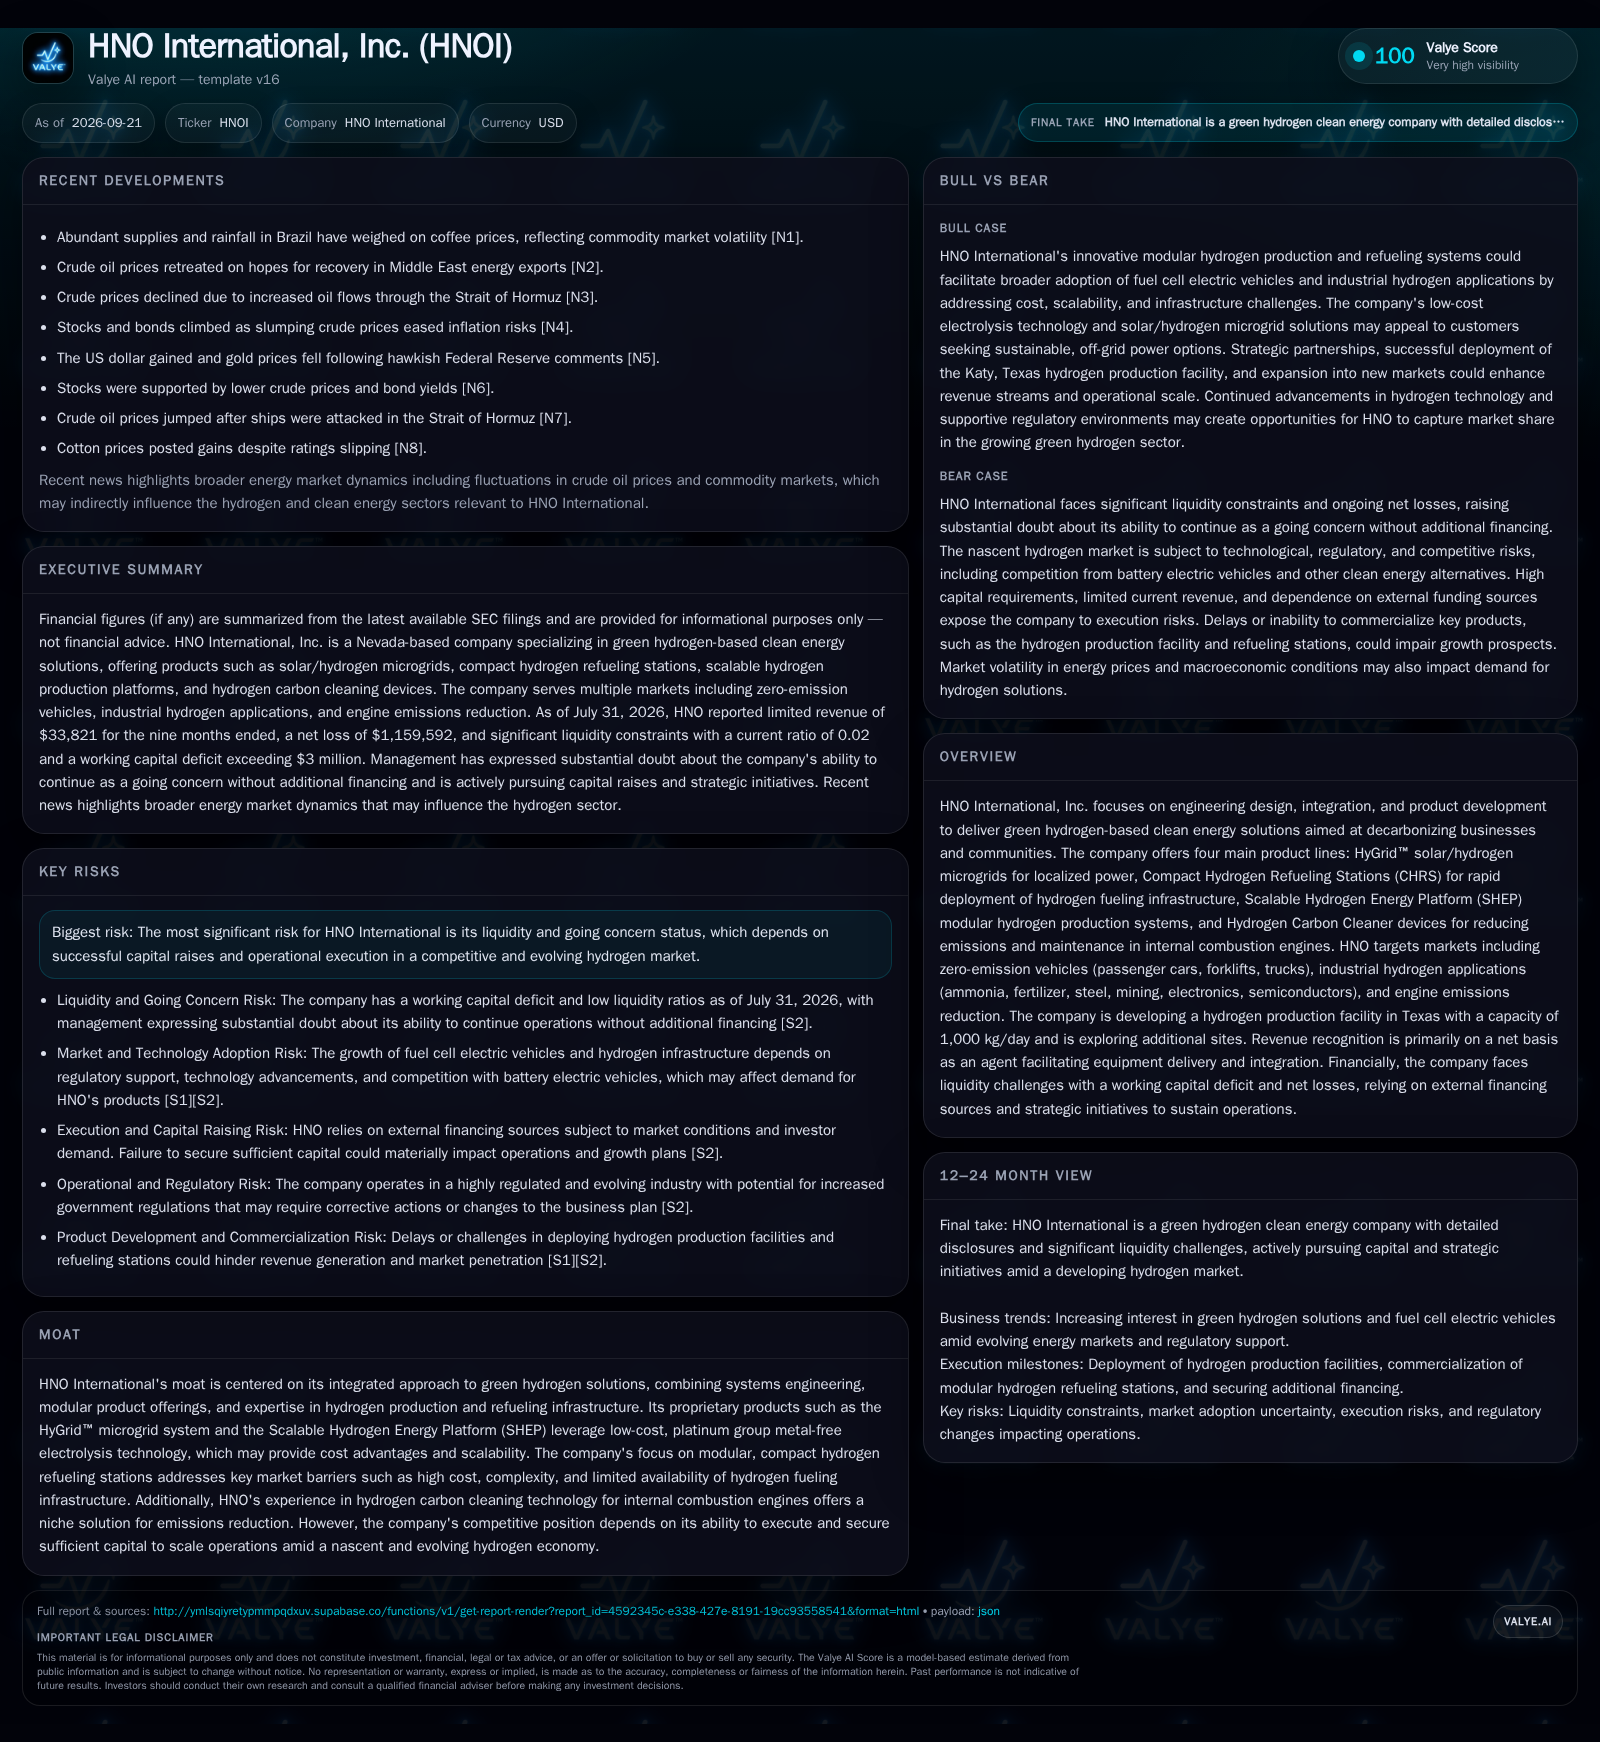
HNO International develops green hydrogen-based energy solutions, with a product portfolio spanning microgrids, modular refueling stations, and hydrogen engine cleaners. Despite technical expertise and a pipeline project in Texas, the company’s working capital deficit, minimal realized revenue, and explicit going-concern warning put its future in the balance. The critical question is whether HNO can secure the capital and partnerships needed to commercialize its offering before liquidity runs out [S2].
HNO International is betting on modular green hydrogen solutions—microgrids, refueling stations, and engine decarbonization devices—to capitalize on the global push for decarbonization. However, with minimal revenue, a large working capital deficit, and an explicit going-concern warning, HNO’s survival hinges on urgent capital raising and the ability to turn technical promise into commercial traction. The company’s future will be shaped by its success in deploying its Texas hydrogen facility, securing new customers, and navigating a competitive, capital-intensive hydrogen market.
Liquidity Crisis and Commercialization Imperative Define HNO’s Present
HNO International’s most material current facts are its precarious financial position and minimal commercial traction. For the nine months ended July 31, 2026, the company generated just $33,821 in revenue, recognized on a net basis due to its role as an agent in hydrogen equipment delivery, and reported a net loss of $1,159,592 [S2]. Liquidity is acute: cash and equivalents stood at $145,670, with a working capital deficit of $3,031,505 and a current ratio of 0.02 [S2]. Management has formally acknowledged substantial doubt about the company’s ability to continue as a going concern without new financing [S2].
The company’s most tangible near-term project is a planned hydrogen production facility in Katy, Texas, designed for up to 1,000 kg/day output, with commercial production targeted for early 2026 [S1]. HNO is actively seeking capital through an Equity Purchase Agreement, Regulation A offering, and convertible notes, but market conditions and investor appetite are uncertain [S2]. These facts frame a business at the edge: technical expertise and product development are present, but the lack of operational revenue and balance-sheet strain mean that execution and solvency are now the central questions.
Revenue Recognition, Margins, and the Challenge of Scaling Hydrogen Solutions
HNO’s business model centers on systems engineering for green hydrogen, with revenue recognized primarily on a net basis as an agent for equipment delivery and integration support [S2]. This means the company retains only a margin—rather than full gross proceeds—on sales, which could limit the immediate operating leverage and make substantial revenue growth harder to translate into profitability unless volume or service mix shifts materially.
The company’s product set spans capital-intensive infrastructure (microgrids, hydrogen refueling stations, modular production plants) and lower-complexity devices (engine carbon cleaners). The economics of hydrogen infrastructure are traditionally characterized by high up-front capital expenditure and long payback periods, with potential for recurring revenue if service, maintenance, or hydrogen sales are bundled. HNO’s ability to capture recurring revenue streams may depend on structuring long-term service contracts or hydrogen offtake agreements—mechanics not yet established by available disclosures.
Operating leverage is likely low at this stage, as modest agent-based revenues are dwarfed by fixed costs in engineering, development, and SG&A. Capital needs are acute: deploying a hydrogen plant or expanding product deployment requires significant funding, and the current balance sheet cannot support these investments without external capital. The company’s cost-saving initiatives and search for strategic partners highlight the challenge of scaling in a sector where infrastructure buildout is both capital- and credibility-intensive.
Hydrogen Integration: Differentiation, Substitution, and the Evolving Competitive Set
HNO’s approach—integrating modular hydrogen production and refueling systems with solar microgrids—targets pain points in early-stage hydrogen infrastructure: cost, scalability, and deployment complexity. The company’s focus on platinum group metal-free electrolysis and modularity could offer cost advantages if the technology proves reliable at scale.
However, the competitive landscape is intense. Large industrial gas companies, oil & gas majors, and well-funded clean energy startups are all vying for share in hydrogen generation, distribution, and fueling infrastructure. Battery electric vehicles remain the dominant zero-emission alternative in transportation, and hydrogen’s adoption curve outside of heavy-duty, industrial, or remote applications remains uncertain.
Switching frictions for customers—such as infrastructure compatibility, total cost of ownership, and regulatory incentives—may slow adoption. HNO’s ability to win share depends on demonstrating reliability, cost-competitiveness, and integration value, but its lack of operational scale and financial resources puts it at a disadvantage relative to larger, capitalized competitors. The company’s engine carbon cleaning device addresses a niche, but this market is likely limited and may face substitution as fleets transition to electric or hydrogen powertrains.
From Survival to Scale: How Rapid Execution and Capital Could Unlock Growth
The positive scenario for HNO hinges on three interlocking developments: securing sufficient capital to sustain operations and complete the Texas hydrogen facility, achieving technical and commercial milestones in production and deployment, and riding a wave of regulatory and customer adoption of green hydrogen solutions.
If HNO successfully raises funds through its Equity Purchase Agreement, Regulation A, or strategic partnerships, it could bring the Katy facility online on schedule. Early operational success—demonstrated by reliable, cost-effective hydrogen production and customer uptake—would provide proof points to unlock further commercial contracts and potentially higher-margin service revenue. Expansion into new deployments, or strategic alliances with established industry players, could accelerate adoption and provide access to broader markets.
Evidence confirming this scenario would include: (1) timely completion and commissioning of the Texas plant, (2) multi-year offtake or supply agreements with industrial or mobility end-users, (3) recurring revenue from service or hydrogen sales, and (4) successful, non-dilutive capital raises that strengthen the balance sheet. Falsification would be signaled by continued delays, inability to secure meaningful contracts, or failed capital-raising efforts.
Commercial Progress Constrained by Funding Gaps and Market Uncertainty
The most plausible outcome is that HNO experiences incremental progress—possibly bringing the Texas facility to operational status—but remains constrained by limited working capital and slow customer adoption. Revenue growth may be modest, reflecting agent-based margins and a gradual ramp in infrastructure deployment. Cost-saving measures and attempts at partnership may provide some runway, but the company will likely face ongoing dilution or unfavorable financing terms as it seeks to bridge funding gaps.
The hydrogen market itself is developing, but widespread adoption remains dependent on policy incentives, cost competitiveness, and customer willingness to experiment with new suppliers. HNO’s lack of scale and limited track record could make it difficult to secure large contracts, and competition from larger or more established players may squeeze margins further.
Evidence confirming this scenario would include continued reliance on small, periodic capital raises; slow but positive revenue growth; and incremental customer wins or pilot deployments. Falsification would be a sudden, transformative contract win, strategic acquisition, or a liquidity crisis leading to insolvency or forced asset sales.
Liquidity Exhaustion and Execution Stumbles Could Lead to Restructuring or Dissolution
The adverse scenario is driven by HNO’s inability to secure sufficient new capital before its cash runs out, compounded by delays or failures in deploying its core hydrogen facility or signing material contracts. In this scenario, the company would be forced to curtail operations, delay or abandon projects, and potentially enter restructuring or dissolution.
Potential triggers include deterioration in capital markets, investor fatigue with early-stage hydrogen projects, or technical setbacks at the Texas facility. Even with product readiness, lack of customer adoption or regulatory support could prevent revenue from scaling quickly enough to offset fixed costs.
Evidence confirming this scenario would be missed construction or operational milestones, default on current liabilities, disclosure of failed financing efforts, or management signals of asset sales or shutdowns. Falsification would require clear demonstration of new funding, operational milestones achieved, and customer contracts locked in.
Milestones and Metrics That Will Determine HNO’s Viability and Trajectory
Progress on the Katy, Texas hydrogen production facility—specifically, achieving commercial operations and hitting targeted output levels.
Disclosure of new multi-year customer contracts or offtake agreements for hydrogen supply, if announced.
Actual cash inflows from the Equity Purchase Agreement, Regulation A offering, or other external financings—as opposed to just facility availability.
Demonstrated recurring revenue from service, maintenance, or hydrogen sales, if disclosed.
Gross and net margin trends as agent-based revenue ramps, to test whether scale improves profitability or if margins remain structurally thin.
Deployment numbers or utilization rates for Compact Hydrogen Refueling Stations and HyGrid™ microgrid systems.
Cost structure evolution—specifically, any evidence of fixed cost reduction or operating leverage as volumes increase.
Regulatory or incentive changes that materially affect hydrogen infrastructure economics or market adoption rates.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments