
Disc Medicine at a Crossroads: Clinical Execution, Regulatory Hurdles, and the Stakes of Hematology Innovation
Disc Medicine’s pivotal Phase 3 data for bitopertin and a substantial capital raise set the stage for a high-stakes push toward its first commercial product—yet regulatory doubts and the challenges of translating rare-disease science into market adoption remain central to the story.
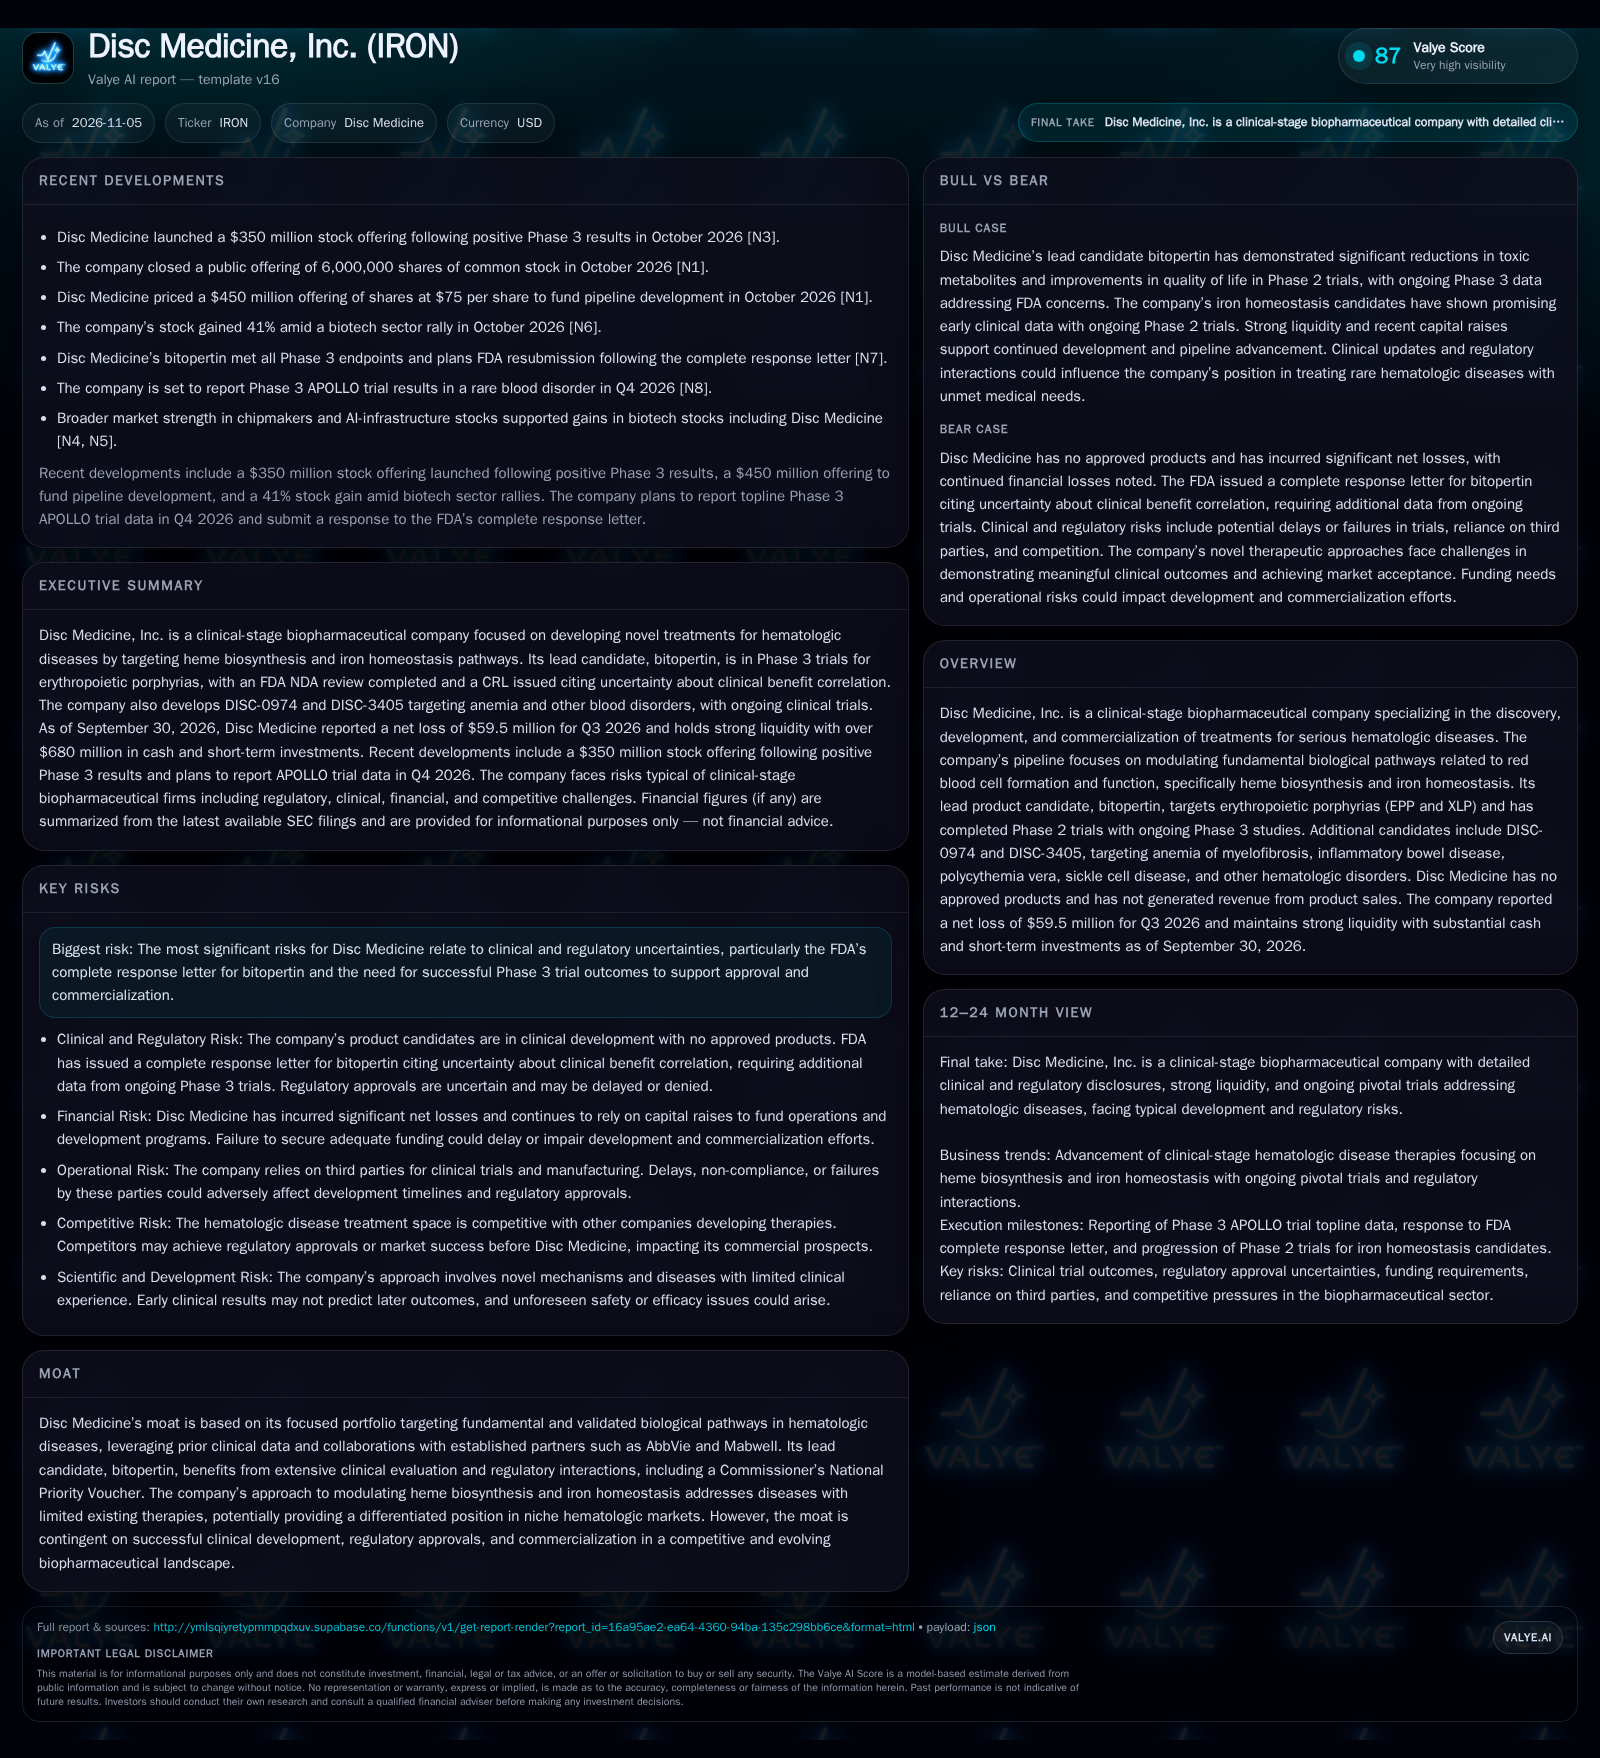
Disc Medicine is approaching a critical inflection point: it has announced positive Phase 3 results for its lead candidate, bitopertin, and raised $350 million in new equity, but the FDA’s complete response letter underscores persistent regulatory uncertainty.
Disc Medicine, Inc. stands at a pivotal moment: its lead candidate, bitopertin, has delivered positive Phase 3 results in rare hematologic diseases, prompting a major capital raise and fueling hopes for its first commercial approval. Yet, the FDA’s recent complete response letter—citing uncertainties around clinical benefit—casts a shadow over the path to market. With more than $680 million in cash and several late-stage programs advancing, Disc faces both the opportunity to define a new standard of care in underserved blood disorders and the familiar perils of clinical-stage biotech: regulatory setbacks, ongoing losses, and the challenge of proving real-world value.
Recent Clinical and Financial Developments Redefine Disc Medicine’s Strategic Position
Disc Medicine’s business outlook has shifted markedly in recent months. The company announced that bitopertin, its lead candidate for erythropoietic porphyrias, met all primary endpoints in a pivotal Phase 3 trial—a milestone that triggered a planned resubmission to the FDA after a prior complete response letter (CRL) raised doubts about the clinical significance of its results [N7]. Shortly after reporting these positive data, Disc executed a $350 million stock offering, boosting its cash and short-term investments to over $680 million as of September 2026 [N3] [S2]. Despite this progress, the company remains pre-revenue, having reported a net loss of $59.5 million in Q3 2026 [S2]. The next major catalysts include the FDA’s reaction to its NDA resubmission and the Q4 2026 readout of the APOLLO Phase 3 trial in another rare blood disorder [N8].
How Disc Medicine’s Model Could Translate Innovation into Revenue
Disc Medicine’s economics are currently defined by investment rather than revenue generation. As a clinical-stage biopharmaceutical company, its primary expenditures are R&D, regulatory submissions, and clinical trial operations—costs that are largely fixed in the short term but may scale with expanded trials. The recent $350 million capital raise extends its ability to fund these efforts without near-term commercial cash flows [N3] [S2].
If bitopertin secures FDA approval, Disc’s revenue model would likely hinge on specialty pricing for rare-disease therapeutics. In orphan indications like erythropoietic porphyrias, approved drugs frequently command high per-patient prices due to the lack of alternatives and the severity of disease. However, actual pricing power will depend on demonstrated clinical benefit, payor acceptance, and the drug’s value proposition in real-world settings. Volume is inherently limited by the rarity of target conditions, but mix could be enhanced if bitopertin is approved for multiple porphyria subtypes or other indications.
Operating leverage could be substantial post-approval: R&D costs may stabilize or decline relative to revenue, while SG&A would likely ramp to support commercialization. However, the company’s pre-commercial status means that fixed costs and negative operating margins are likely to persist until regulatory milestones are achieved. Future capital needs will be dictated by the pace of pipeline expansion, additional trial requirements, and the timing of potential product launches.
Positioning in Rare Hematology: Differentiation, Counterforces, and the Competitive Set
Disc Medicine’s core differentiation lies in its targeted approach to heme biosynthesis and iron homeostasis, addressing rare hematologic diseases where few approved therapies exist. This focus potentially grants the company a first-mover or best-in-class advantage in indications like erythropoietic porphyrias if bitopertin is approved. However, the competitive landscape is not static: several other biopharmaceutical firms, both large and small, are pursuing therapies for rare anemias and iron disorders, often leveraging different mechanisms of action or gene therapies.
A key counterforce is the regulatory bar for demonstrating meaningful clinical benefit in rare diseases, especially where surrogate endpoints are less clearly correlated with patient outcomes. The FDA’s recent CRL for bitopertin explicitly cited uncertainty about the linkage between biomarker reduction and tangible clinical improvement, highlighting a hurdle that both Disc and its competitors must overcome.
Switching costs for patients could be high if bitopertin becomes the first approved therapy, given the lack of alternatives and the chronic nature of these conditions. However, payors may scrutinize pricing and require robust evidence of benefit. Disc’s competitive position could be further strengthened by successful expansion into broader indications for its iron homeostasis pipeline, but this will depend on clinical results and the speed of competitor development.
Regulatory Clarity and Commercial Uptake Could Unlock Significant Value
A favorable scenario for Disc Medicine would see the company successfully address the FDA’s concerns in its NDA resubmission for bitopertin, leading to approval in erythropoietic porphyrias. This would enable Disc to capture first-mover advantage in a rare-disease segment with high unmet need and limited competition, supporting premium pricing and rapid uptake among eligible patients. Additional upside could come from positive APOLLO trial data, which might expand the addressable market or further validate the platform’s clinical benefit.
Evidence that would support this scenario includes: clear FDA guidance on the clinical endpoints required for approval; a successful NDA resubmission resulting in approval without additional large-scale trials; strong APOLLO data showing not only biomarker improvement but also meaningful patient outcomes; and early signals of payor acceptance or patient advocacy support. Expansion of bitopertin into other rare hematologic disorders or positive Phase 2/3 results for DISC-0974 and DISC-3405 would further enhance the long-term revenue potential.
Disc Medicine’s Most Plausible Trajectory: Incremental Progress Amid Persistent Uncertainties
The most likely near-term scenario is that Disc Medicine continues to advance its clinical programs while working through regulatory challenges. The company may secure FDA approval for bitopertin after providing additional evidence from ongoing or completed trials, but the process could involve delays or requests for further data. If approved, initial commercial uptake may be gradual as physicians and payors assess real-world outcomes.
Pipeline programs in iron homeostasis and anemia may yield promising data, but are likely to remain in the clinic for several years before contributing materially to revenue. Falsification would be signaled by prolonged regulatory standoffs, failed trials, or rapid depletion of cash without clear advancement.
Setbacks in Clinical Validation or Regulatory Approval Could Undermine the Investment Case
The most adverse scenario for Disc Medicine would involve failure to resolve the FDA’s concerns over bitopertin’s clinical benefit, resulting in additional complete response letters, requirements for new trials, or outright rejection. Such outcomes would delay or preclude commercialization, leading to extended periods of cash burn without offsetting revenue. Negative or inconclusive results from the APOLLO trial or from ongoing studies of DISC-0974 and DISC-3405 would further erode confidence in the pipeline.
This scenario could be confirmed by regulatory announcements indicating the need for new pivotal studies, negative trial data, increasing operating losses, or a need for further dilutive capital raises before any clear path to approval is established. If competitors achieve approval or market traction first, Disc’s commercial prospects could also be impaired, particularly if alternative therapies demonstrate superior efficacy or convenience.
Milestones and Metrics to Track as Disc Medicine Confronts Regulatory and Clinical Pivots
FDA feedback and timing on the NDA resubmission for bitopertin: Approval, additional information requests, or new trial requirements will be pivotal.
Topline results from the APOLLO Phase 3 trial in Q4 2026: Both biomarker and patient-reported outcome data will be informative.
Cash burn rate and projected runway as development progresses, particularly if disclosed in future filings.
Initial commercial uptake, pricing, and payor coverage for bitopertin if approved—a useful metric would be early prescription trends or formulary wins.
Pipeline advancement for DISC-0974 and DISC-3405: Entry into late-stage trials or new indication expansions would help test the long-term thesis.
Competitive developments in rare hematologic and iron disorders, including new approvals or clinical breakthroughs by peers.
Any changes in regulatory guidance or rare disease policy that could affect approval standards or market access.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments