
Incannex Healthcare: Clinical Milestones, Capital Strategy, and the Stakes for Novel Combination Therapies
Incannex Healthcare’s progress with IHL-42X for obstructive sleep apnea and PSX-001 for anxiety has been marked by clinical wins and regulatory tailwinds, but persistent losses and dilution events highlight the critical importance of trial outcomes and capital discipline as the company advances toward pivotal studies.
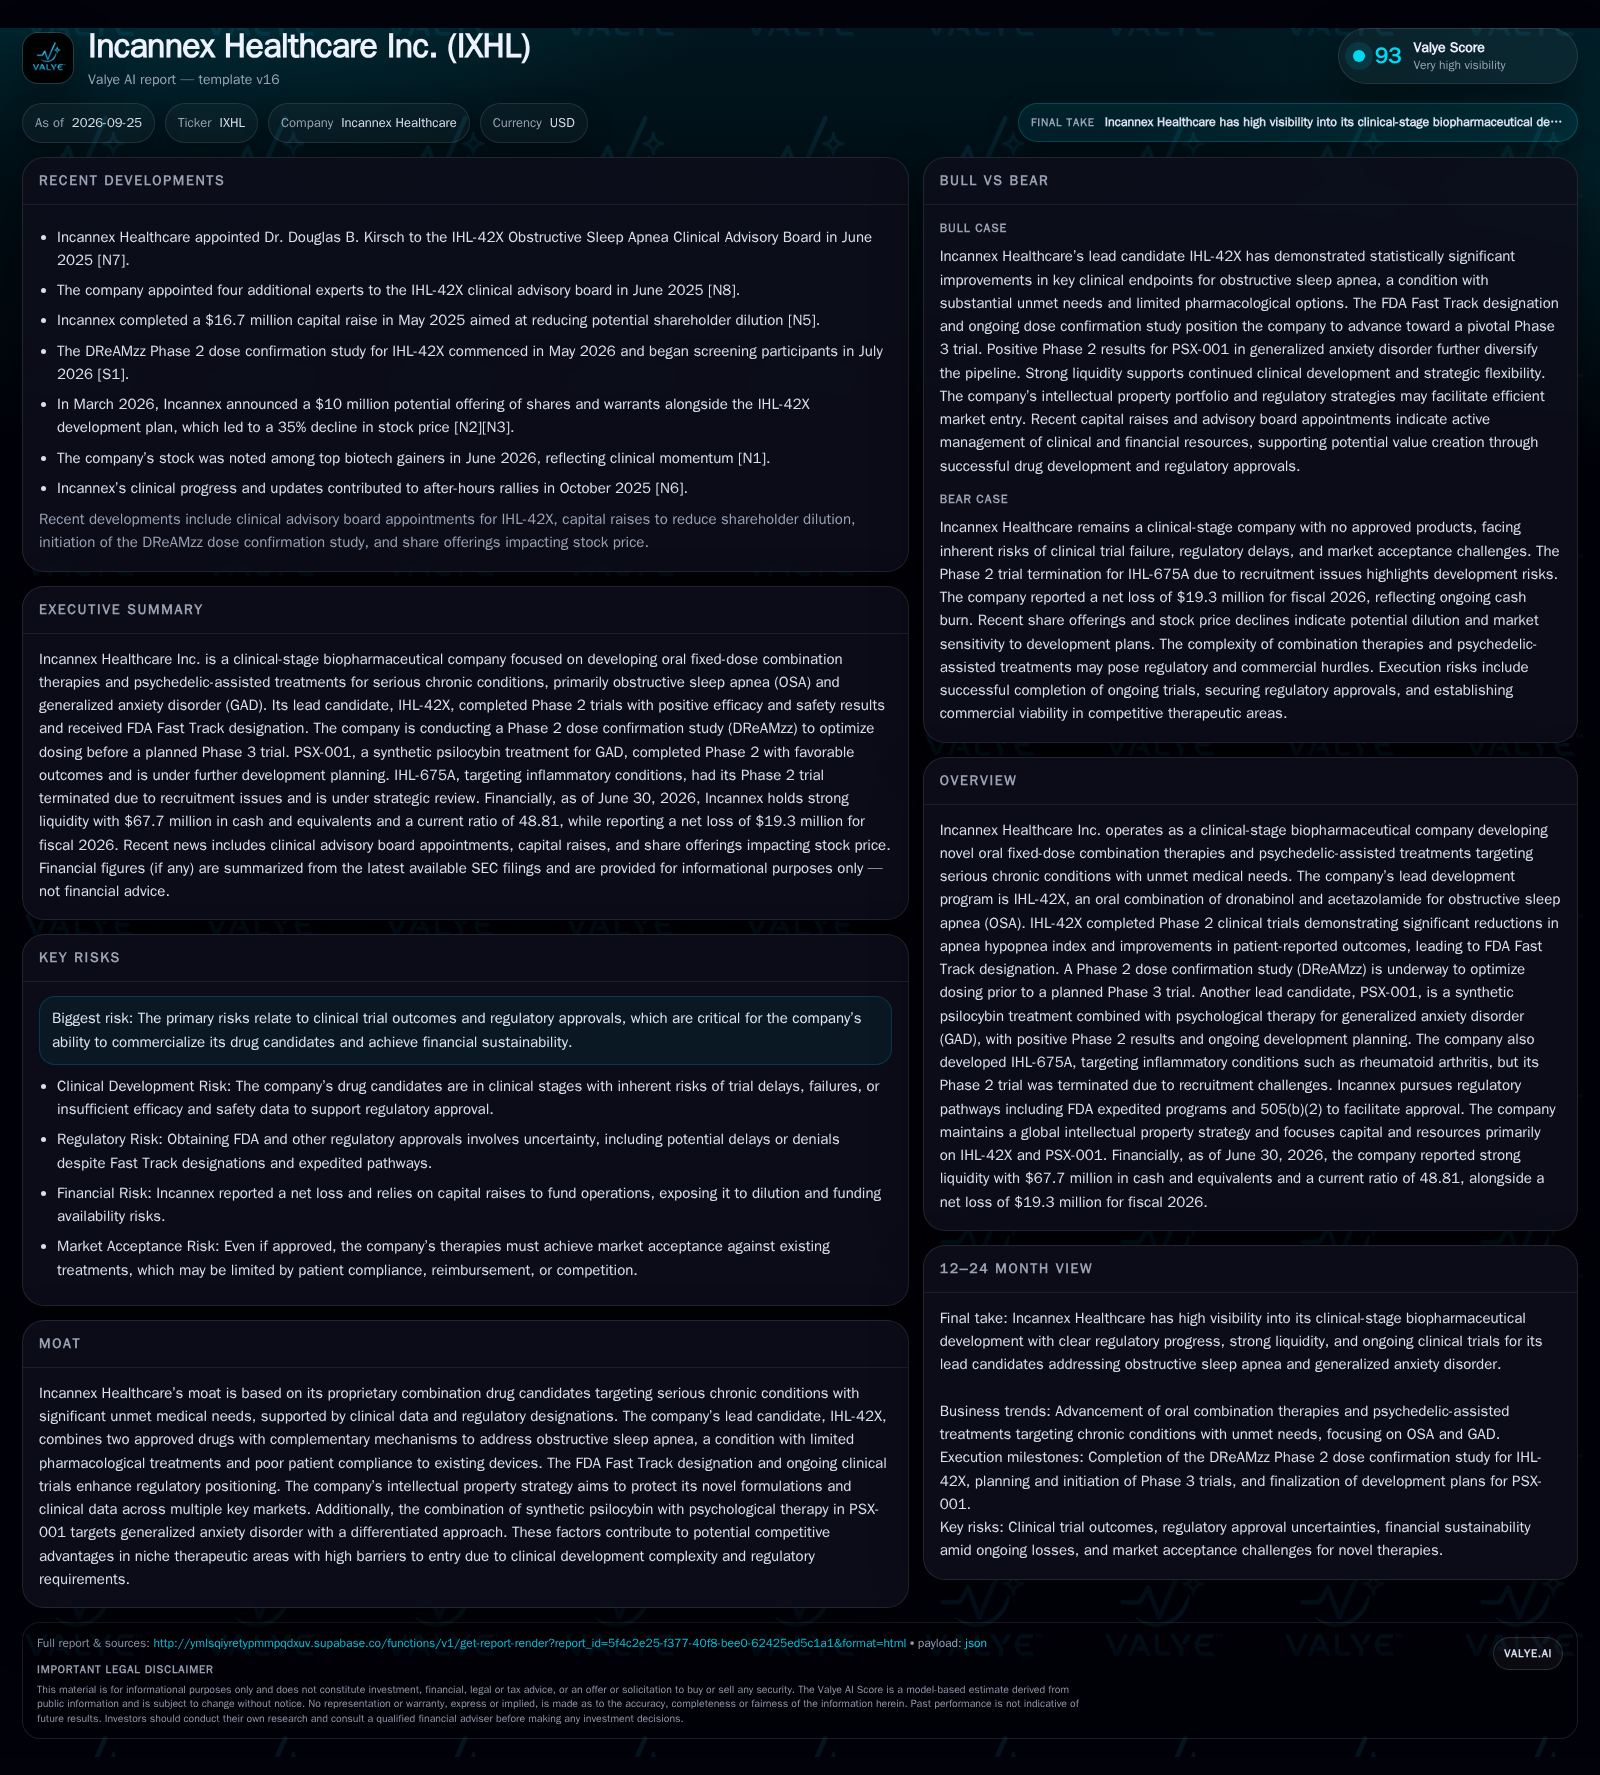
Incannex Healthcare is advancing two lead clinical-stage drug candidates—one for obstructive sleep apnea (IHL-42X) and one for generalized anxiety disorder (PSX-001)—with recent Fast Track designation, ongoing Phase 2/3 trials, and reported liquidity position of $67.7 million as of June 2026. However, the company remains pre-revenue, reported a $19.3 million net loss in 2026, and experienced a 35% stock drop after announcing a $10 million equity offering. The next 12-24 months will likely hinge on IHL-42X’s dose confirmation results, regulatory clarity, and management’s ability to balance capital needs with dilution risk. [S1] [N2] [N3]
Incannex Healthcare stands at a pivotal moment in its evolution as a clinical-stage biopharmaceutical company. With two lead programs—one targeting obstructive sleep apnea (IHL-42X) and another targeting generalized anxiety disorder (PSX-001)—the company has recently secured regulatory momentum and posted strong clinical results. Yet, the realities of persistent net losses, reliance on capital markets, and the inherent risks of drug development weigh heavily on the path ahead.
Recent Clinical Advances and Capital Moves Define the Current Operating Environment
As of June 30, 2026, Incannex Healthcare reported $67.7 million in cash and equivalents, a current ratio of 48.81, and a net loss of $19.3 million for the fiscal year, highlighting both reported liquidity position and ongoing cash burn as the company advances its clinical programs. [S1]
IHL-42X, the company’s lead candidate for obstructive sleep apnea, completed a Phase 2 trial demonstrating reductions in apnea hypopnea index and improved patient-reported outcomes, leading to FDA Fast Track designation in December 2025. A Phase 2 dose-confirmation study (DReAMzz) began in May 2026 and is set for completion in mid-2027, with a Phase 3 trial planned thereafter. [S1]
In March 2026, Incannex announced a $10 million potential offering of shares and warrants to support IHL-42X development, which precipitated a 35% drop in the company’s stock price. This event underscores the market’s acute sensitivity to dilution and the critical importance of capital management at this stage. [N2] [N3]
How Incannex Could Capture Value: Commercial and Cost Dynamics in a Pre-Revenue Biotech
Incannex’s business model centers on developing novel, fixed-dose combination drugs and psychedelic-assisted therapies for chronic conditions with limited treatment options. The economics, if clinical and regulatory hurdles are cleared, could be attractive: approved drugs for obstructive sleep apnea and generalized anxiety disorder often command premium pricing due to the severity and prevalence of these conditions.
For IHL-42X, the cost structure is currently dominated by R&D, clinical trial expenses, and regulatory submissions. If approved, commercialization would likely require a specialty sales force, partnerships, or licensing arrangements—each with distinct margin implications. Fixed costs are currently high, but successful approval could introduce meaningful operating leverage as revenues scale without a commensurate rise in overhead.
The company’s reliance on equity financing, as evidenced by its $10 million offering, reflects the capital intensity and cash-burn profile typical of clinical-stage biotech. Until product revenue materializes, ongoing capital raises are likely, making prudent allocation and timing essential to minimize shareholder dilution.
If IHL-42X or PSX-001 reaches market, pricing power will depend on clinical differentiation, payer willingness to reimburse, and the degree to which these therapies can replace or complement existing standards of care. The use of the 505(b)(2) pathway could expedite approval and reduce costs relative to new molecular entities, but the commercial mechanics—such as gross-to-net discounts and patient access barriers—will only become clear at launch.
Assessing Incannex’s Prospects in Crowded and Evolving Therapeutic Markets
Incannex operates in therapeutic areas with significant unmet needs but also growing competitive activity. In obstructive sleep apnea, the dominant intervention remains CPAP (continuous positive airway pressure) devices, which suffer from low patient adherence. Pharmacological options are limited, and IHL-42X’s oral fixed-dose combination could address compliance gaps if efficacy and safety are proven.
Psychedelic-assisted therapies for psychiatric disorders, such as generalized anxiety, are attracting increasing investment and regulatory attention. PSX-001’s synthetic psilocybin approach, combined with structured psychological therapy, positions it within a field that includes both traditional SSRIs and emerging psychedelic competitors. The outcome will depend on comparative efficacy, safety, and the ability to integrate into clinical practice.
The company’s proprietary formulations, FDA Fast Track status, and global intellectual property strategy offer some barriers to entry, but these advantages will be tested as other biotech and pharmaceutical firms race to develop both combination therapies and next-generation psychedelics. Without robust data and clear regulatory wins, any first-mover or differentiation advantage could prove fleeting.
Ultimately, the competitive moat will rely not only on clinical outcomes, but also on the ability to secure payer coverage, influence treatment guidelines, and execute on commercial partnerships or licensing agreements.
What Could Unlock Major Value: Clinical Success and Efficient Capital Deployment
The most compelling upside scenario is driven by IHL-42X’s successful completion of the DReAMzz Phase 2 study, followed by a robust Phase 3 trial that confirms efficacy and safety in obstructive sleep apnea. FDA approval—potentially accelerated by Fast Track designation and the 505(b)(2) pathway—would open a large, underpenetrated market. PSX-001’s further advancement, especially with IND clearance and additional positive clinical data, would diversify the pipeline and enhance the company’s profile.
Efficient use of cash, supported by the current balance, could reduce the need for near-term dilutive financings. Strategic partnerships or licensing deals—particularly if struck after pivotal data—could provide non-dilutive capital and accelerate commercialization.
Evidence confirming this scenario would include: (1) positive top-line results from the DReAMzz study; (2) clear regulatory guidance supporting a rapid Phase 3 timeline; (3) initiation of business development discussions or partnership announcements; (4) limited or well-timed equity raises that do not materially depress the share price.
Most Likely Outcome: Gradual Progress, Ongoing Cash Burn, and Event-Driven Volatility
The most plausible path is that Incannex continues to advance IHL-42X through its ongoing Phase 2 and planned Phase 3 studies, with incremental clinical updates driving episodic stock volatility. PSX-001 may advance more slowly, given the need for further planning and regulatory engagement.
Market sentiment will remain closely tied to clinical milestones, regulatory news, and the cadence and terms of new financings.
Confirmation of this scenario would come from steady trial enrollment and data readouts, continued net losses offset by periodic capital raises, and the absence of transformative partnership or acquisition activity.
Where the Thesis Could Break: Clinical Setbacks, Regulatory Delays, and Accelerated Dilution
The risk scenario is defined by one or more clinical disappointments—such as inconclusive or negative results from the DReAMzz Phase 2 study, safety concerns, or setbacks in the regulatory process for IHL-42X or PSX-001. Regulatory delays, especially if the Fast Track or 505(b)(2) pathways fail to yield expedited review, could extend the cash burn timeline.
In the absence of positive clinical or regulatory news, the company could be forced to raise capital on increasingly unfavorable terms, compounding dilution and further eroding investor confidence—much as the March 2026 offering did. If cash balances fall below a critical threshold before pivotal data is available, Incannex may need to scale back programs or seek a strategic alternative under duress.
Evidence that would validate this scenario includes: missed trial enrollment targets or data milestones, unexpected adverse events or efficacy failures, regulatory setbacks, or a rapid acceleration in equity issuance amid a declining share price.
Milestones and Metrics That Will Define Incannex’s Next Chapter
Top-line results and safety data from the DReAMzz Phase 2 dose confirmation study for IHL-42X, expected by mid-2027, will be the primary inflection point for the lead program.
Regulatory feedback from the FDA regarding the timing and design of the planned Phase 3 trial for IHL-42X will clarify the path to potential approval.
Cash burn rate and quarterly operating loss trends, if disclosed, will be critical in assessing the timing and magnitude of future capital needs.
Updates on partnership, licensing, or co-development discussions—particularly following positive clinical data—would help test the company’s ability to access non-dilutive funding.
Progress on PSX-001’s U.S. development pathway, including new clinical trial initiations, IND amendments, or regulatory guidance, will signal whether the pipeline can deliver diversification value.
Any changes in the competitive landscape for OSA or GAD—such as new drug approvals, payer coverage decisions, or guideline updates—could materially affect Incannex’s addressable market and commercial prospects.
Announced or completed equity offerings, including their size, timing, and impact on the share price, will continue to serve as a barometer for market confidence and capital discipline.
If disclosed, patient adherence and retention data from IHL-42X trials would clarify the real-world differentiation from device-based OSA therapies.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments