
ST JOE Co: Diversification, Capital Structure, and the Durability of Regional Real Estate Economics
Recent results show ST JOE Co balancing growth in hospitality and leasing with traditional real estate sales, supported by a sizable investment property base and increased dividends. The core question is whether its multi-pronged model can withstand credit concentration risk and cyclical headwinds while maintaining capital flexibility.
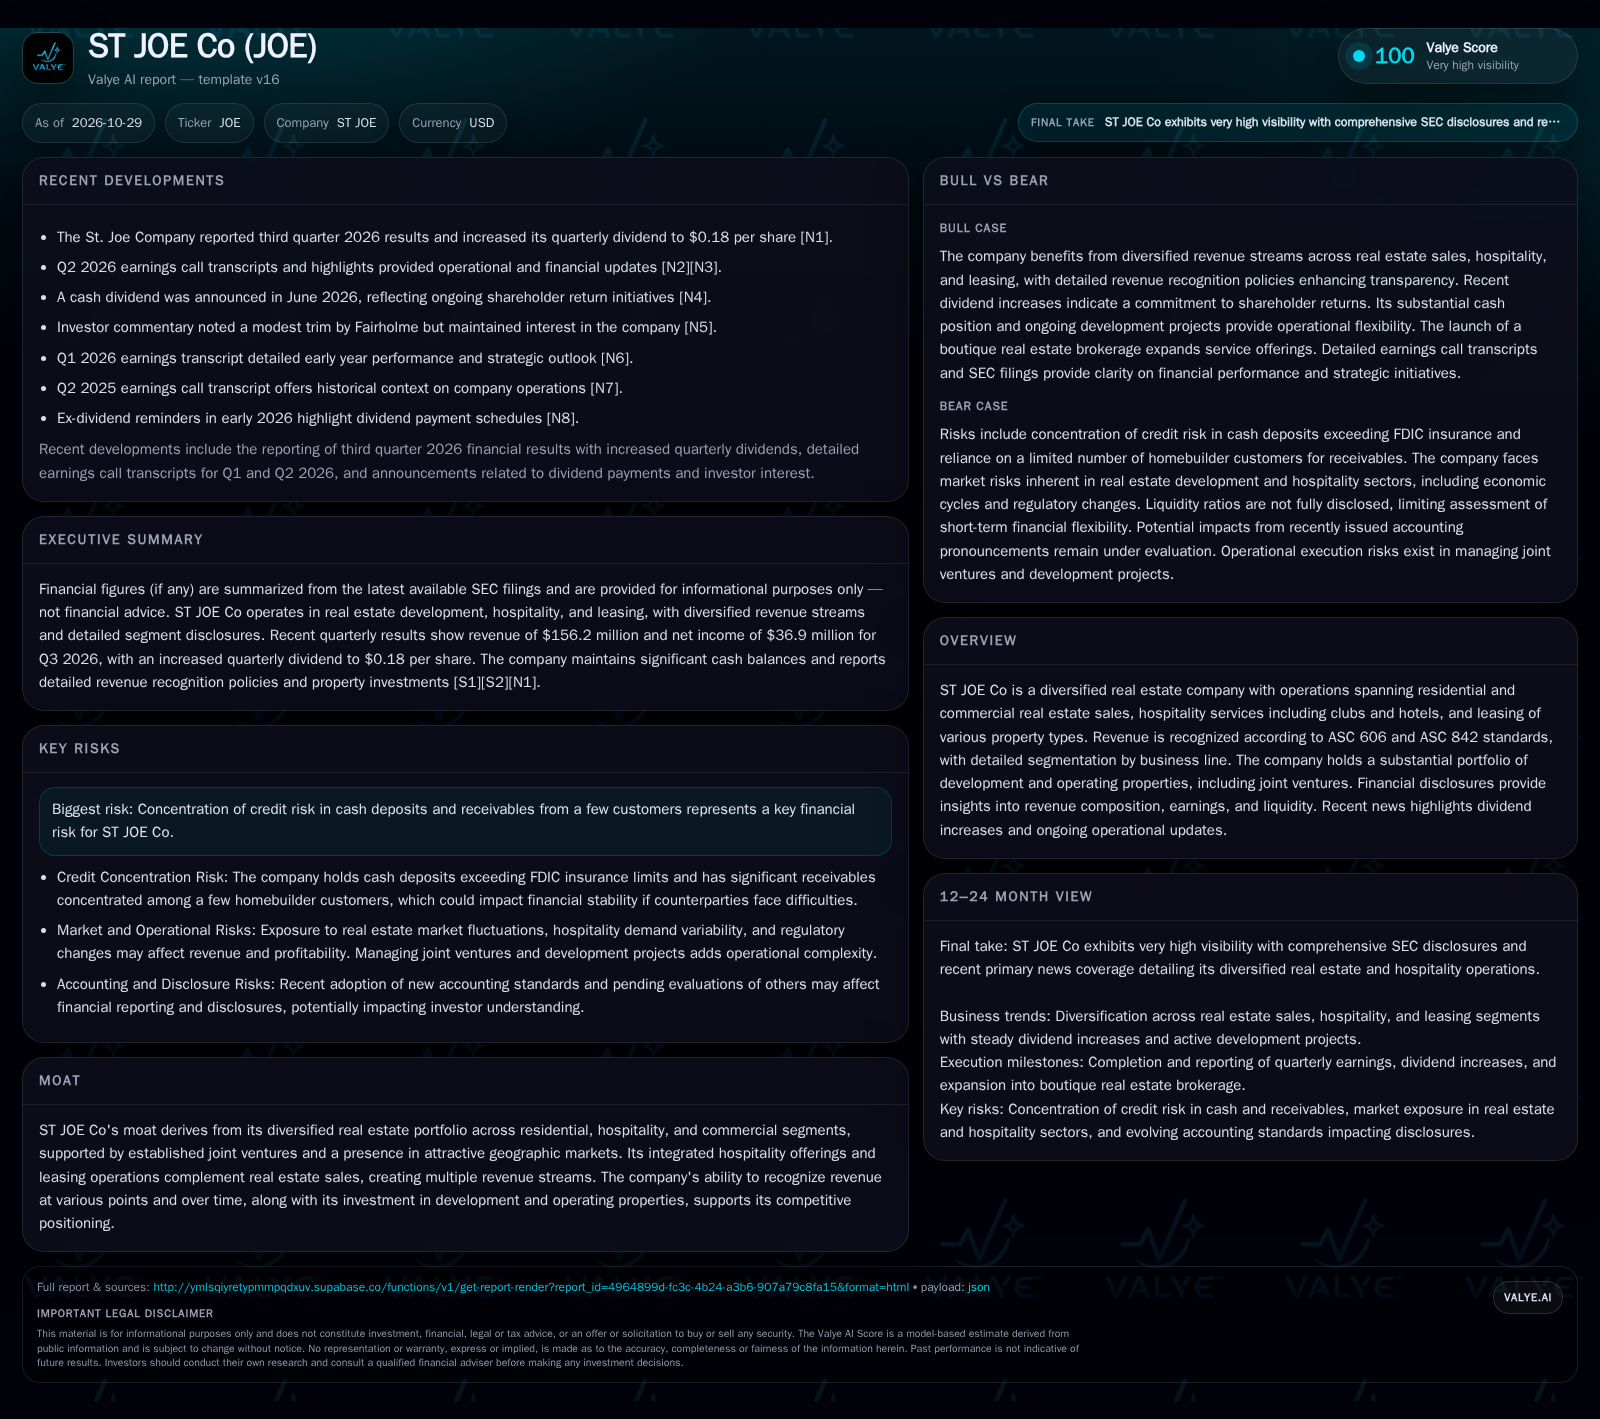
ST JOE Co reported Q3 2026 revenue of $156.2 million, net income of $36.9 million, and raised its quarterly dividend to $0.18 per share. The firm’s revenue mix spans real estate sales, hospitality, and leasing, with a $1.0 billion net investment in properties and $117.9 million in cash as of late September 2026. While diversification and recurring income streams help stabilize performance, concentration risks in receivables and deposits, along with sector cyclicality, remain the key thesis tests.[S1] [S2] [N1]
ST JOE Co’s latest financials illustrate a business straddling multiple real estate verticals—residential sales, hospitality operations, and leasing—each contributing meaningfully to a $513 million annual revenue base. The company’s $1.0 billion net real estate investment and increased dividend underscore both asset depth and a willingness to return capital. Yet, with notable credit risk concentration and sector cyclicality, the company’s ability to sustain growth and margin stability hinges on operational execution, capital allocation, and the resilience of its regional end markets.
Recent Results Highlight Diversification and Capital Return Initiatives
For the third quarter of 2026, ST JOE Co reported revenue of $156.2 million and net income of $36.9 million, translating to $0.65 per share.[S2] [N1] The company’s annual revenue for 2025 reached $513 million, with hospitality ($221 million), real estate sales ($165 million), and leasing ($119 million) as major contributors.[S1] Cash and cash equivalents totaled $117.9 million at the end of Q3 2026.[S2] The quarterly dividend was raised to $0.18 per share in October 2026, continuing a pattern of shareholder return.[N1]
These facts matter because they demonstrate not only the breadth of ST JOE’s revenue streams, but also a willingness to deploy capital toward dividends, indicating management’s confidence in near-term cash flows. The substantial property base ($1.0 billion net investment) provides the asset backing for these activities, while the credit concentration in both deposits and receivables points to a potential vulnerability if counterparties or market conditions deteriorate.[S1]
How ST JOE Co’s Multi-Segment Model Shapes Profitability and Cash Flow
ST JOE Co generates revenue through three primary channels: real estate sales, hospitality operations, and leasing. Real estate sales typically yield lumpier, transaction-driven income, recognized at the point of sale. Hospitality revenue is more recurring, tied to the ongoing provision of services at clubs, hotels, and golf courses, and is recognized at the point of service. Leasing revenue, derived from retail, office, and multi-family properties, is recognized on a straight-line basis over lease terms, providing a degree of revenue visibility and smoothing cash flow volatility.[S1]
This structure creates a blend of fixed and variable economics. The hospitality and leasing segments, while capital intensive (requiring investment in land, buildings, and amenities), have the potential to generate recurring income and operating leverage as occupancy and utilization rates rise. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. The company’s $1.0 billion in net real estate investment as of year-end 2025 reflects a commitment to asset-backed income streams, though this also ties up capital and exposes the business to market cycles.[S1]
Capital needs are ongoing, particularly for development and hospitality upgrades, and the company’s ability to recycle capital from property sales or joint ventures will be a critical determinant of future economics.
Regional Scale, Asset Integration, and the Challenge of Replicability
ST JOE Co’s competitive position is anchored in its diversified portfolio of residential, hospitality, and commercial properties, along with established joint ventures in high-profile developments like Watersound and Pier Park.[S1] This integration allows the company to capture multiple revenue streams from overlapping customer bases—residents, tourists, and businesses—within its regional footprint.
The company’s moat is further supported by its land holdings and the ability to influence local development patterns, which can be difficult for new entrants to replicate. However, the competitive landscape in real estate and hospitality is fragmented and includes regional developers, national REITs, hotel operators, and alternative lodging providers. The rise of short-term rental platforms and shifting consumer preferences could erode pricing power or occupancy in hospitality. In leasing, alternative work and shopping patterns may pressure office and retail demand, while multi-family remains supported by demographic trends.
ST JOE’s position is defensible if it can maintain high utilization of its properties, offer differentiated experiences, and manage development risk. However, execution complexity in joint ventures and exposure to local market cycles introduce counterforces that could compress margins or slow growth if not managed proactively.
Unlocking Value Through Asset Monetization and Hospitality Expansion
A favorable scenario would see ST JOE Co accelerating asset monetization—selling developed lots or stakes in joint ventures at attractive prices—while simultaneously increasing occupancy and average daily rates in its hospitality portfolio. This could be driven by strong in-migration to its core markets, robust demand for leisure travel, and successful repositioning of select properties to capture premium customers.
The combination of recurring hospitality and leasing income with periodic windfalls from real estate sales would allow the company to both reinvest in development and increase dividends. Announcements of new joint ventures or property sales at premium valuations would further validate this pathway.
This scenario would be falsified by stagnating hospitality metrics, weak absorption of new residential or commercial projects, or an inability to sell assets at target margins.
Sustaining Mixed-Segment Growth Amid Cyclical Headwinds
The most plausible outlook is that ST JOE Co continues to generate stable, if unspectacular, earnings growth by balancing recurring income from hospitality and leasing with opportunistic real estate sales.
This scenario assumes that regional demand for residential, hospitality, and commercial properties remains healthy, but that macroeconomic or sector-specific headwinds (such as higher interest rates or slower home sales) temper the pace of project launches and sales. The company’s credit concentration risk—particularly with homebuilders and cash deposits—remains contained as counterparties remain solvent and no major defaults occur.
Confirmation would come from quarterly reports showing steady occupancy and leasing spreads, stable or slightly rising dividends, and a continued mix of real estate, hospitality, and leasing revenue. Falsification would involve a sharp drop in homebuilder health, rising receivable write-offs, or unexpected stress in hospitality occupancy or rates.
Credit Concentration and Market Shocks as Catalysts for Earnings Volatility
In an adverse scenario, a downturn in regional real estate or hospitality markets—possibly triggered by macroeconomic weakness or a specific shock to homebuilder customers—could expose ST JOE Co’s credit concentration risks.
Such a scenario would likely manifest as declining real estate sales, a drop in hospitality utilization, and pressure on leasing spreads. Dividend growth would stall or reverse, and management could be forced to prioritize liquidity over expansion. The capital-intensive nature of the business would amplify the impact of any revenue shortfall, particularly if asset sales become more difficult or must occur at distressed prices.
This scenario would be confirmed by rising receivable allowances, negative surprises in quarterly cash flow, or dividend cuts. It would be further corroborated by a sudden shift in management tone regarding development pace or capital allocation priorities.
Testing the Durability of ST JOE Co’s Multi-Segment Model: What to Track
Quarterly trends in hospitality occupancy and average daily rate—if disclosed—as indicators of recurring income health.
Receivables concentration and aging: monitoring for any increases in overdue balances or allowances tied to homebuilder customers would help test credit risk.
Pace and margin of real estate sales, including lot sales and joint venture transactions, as signs of asset monetization effectiveness.
Leasing occupancy and rent spreads across multi-family, retail, and office properties, particularly in light of changing tenant demand.
Capital expenditures and development commitments: a useful metric would be the ratio of new project outlays to operating cash flow.
Liquidity movements: changes in cash and equivalents, especially in relation to major development milestones or potential asset sales, would help test potential financial flexibility.
Updates on adoption or impact of new accounting standards, especially if they materially affect reported earnings or expense disclosures.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments