
MediaAlpha: Platform Scale Meets Execution Risk in the Digital Insurance Acquisition Race
MediaAlpha’s technology-driven insurance customer acquisition platform is scaling rapidly amid digital migration tailwinds, but recent leadership changes and evolving market dynamics sharpen the focus on execution, partner stickiness, and regulatory adaptation.
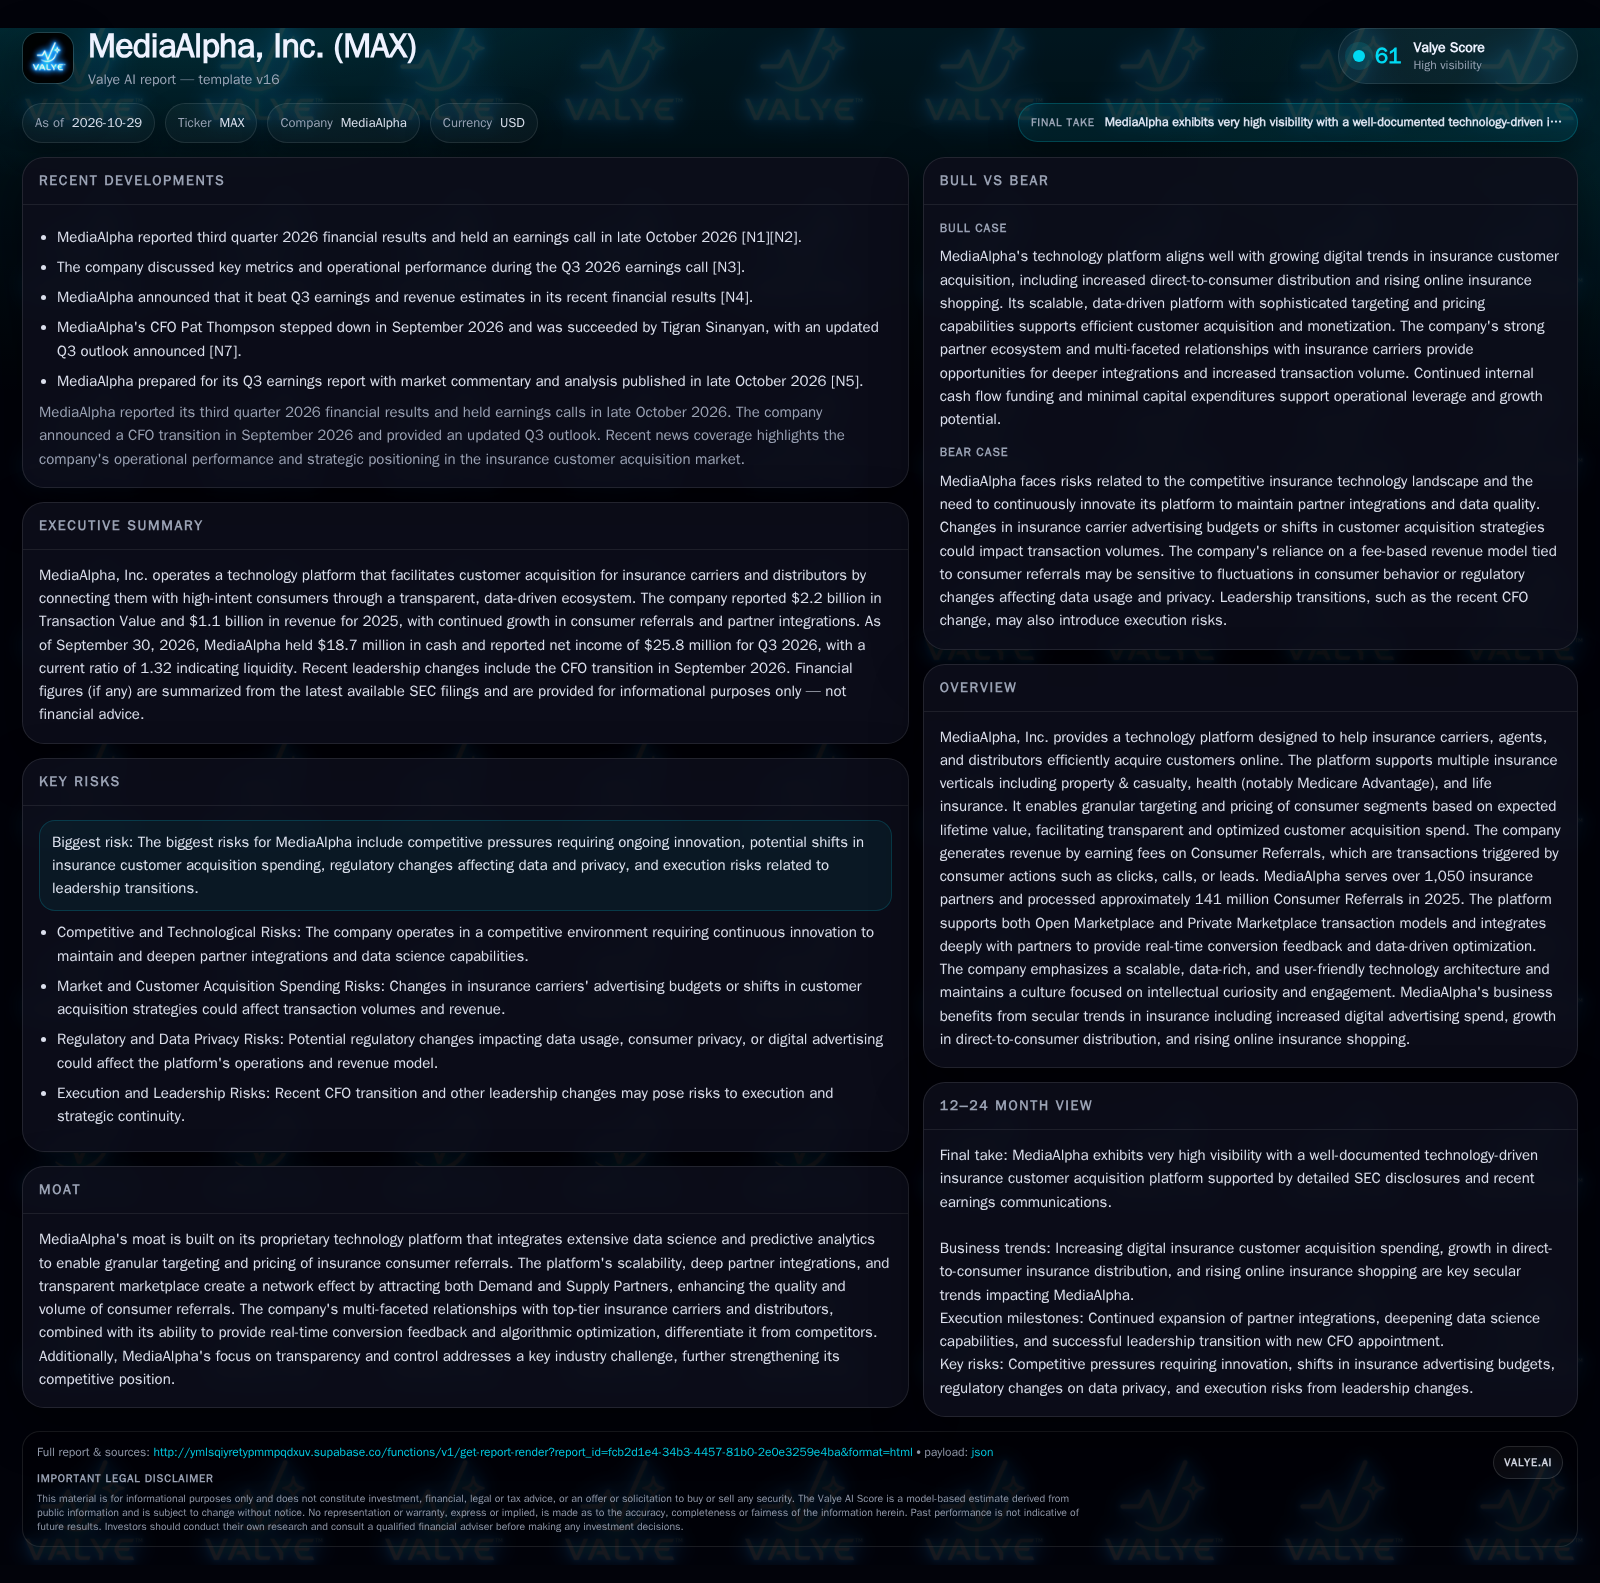
MediaAlpha processed 141 million consumer referrals and generated $1.1 billion in revenue in 2025, confirming its central role in digital insurance distribution. The platform’s real-time data integration and granular targeting support a fee-based model with operational leverage. However, the recent CFO transition and dependence on carrier ad budgets introduce new execution and market risks. The next phase will test MediaAlpha’s ability to deepen partner integrations, sustain innovation, and navigate regulatory headwinds as insurance shopping continues its digital shift. [S2] [N2] [N7]
MediaAlpha, Inc. sits at the intersection of digital marketing and insurance distribution, operating a data-rich platform that connects over 1,050 insurance partners with high-intent consumers. The company’s ability to process more than 140 million consumer referrals annually has solidified its role as a key infrastructure player in the migration of insurance customer acquisition online. However, as the sector’s digital transformation accelerates, MediaAlpha must navigate new execution risks—highlighted by a recent CFO transition—and ongoing uncertainties in carrier advertising budgets, regulatory policies, and technological arms races. The next chapter will test whether MediaAlpha can convert its scale and integration depth into durable, high-margin growth.
Recent Financial Performance and Organizational Shifts Reshape the Strategic Outlook
MediaAlpha processed approximately 141 million consumer referrals in 2025, supporting $2.2 billion in transaction value and generating $1.1 billion in revenue, which demonstrates the company’s scale and relevance in the insurance customer acquisition value chain. [S2] [N2] [S2] The company also reported Q3 2026 net income of $25.8 million, indicating continued profitability. [S2]
A significant organizational development was the CFO transition in September 2026, with Pat Thompson stepping down and Tigran Sinanyan taking the role. [N7] This leadership change introduces potential uncertainty around financial strategy and execution during a period of ongoing platform evolution and competitive pressure.
How MediaAlpha’s Platform Model Translates Scale into Margins
MediaAlpha’s core economics are built around a fee-for-referral model, in which the company earns revenue each time a consumer action—such as a click, call, or qualified lead—connects an insurance partner to a potential customer. This model is highly sensitive to both transaction volume and pricing, but benefits from the platform’s ability to segment, target, and price referrals based on expected lifetime value and real-time conversion data.
The dual Open and Private Marketplace structures allow MediaAlpha to serve a broad spectrum of insurance partners, with deep integrations enabling dynamic bidding and data feedback loops. Fixed costs are driven primarily by technology development, partner support, and data science investments, while variable costs scale with transaction volume. This structure creates potential for operating leverage: as referral volume and partner integrations grow, incremental technology costs rise modestly while gross profit per referral can increase if pricing power or efficiency improves.
Capital requirements are modest, as the business is not capital-intensive and does not require large working capital outlays or inventory. However, ongoing investment in data infrastructure, analytics, and compliance is necessary to sustain differentiation and adapt to regulatory changes. If carrier ad budgets contract or regulatory constraints limit targeting, MediaAlpha’s top-line could prove more cyclical than it appears.
Barriers and Vulnerabilities in Digital Insurance Distribution
MediaAlpha’s platform is differentiated by its scale, data integration, and real-time optimization capabilities, supporting granular targeting and transparent ROI measurement for insurance partners. These attributes help create switching frictions, as partners benefit from algorithmic optimization and deep process integration.
However, the insurance lead-generation and digital marketing landscape is crowded, with both established players and new entrants investing heavily in data science and automation. Competitors—including other insurance technology platforms, digital marketing firms, and direct carriers with in-house acquisition capabilities—can pressure margins and challenge partner loyalty. The most relevant substitutes are alternative digital acquisition channels and emerging data ecosystems that promise lower costs or better targeting.
MediaAlpha’s moat is reinforced by network effects: as more carriers and distributors participate, data quality and transaction volume improve, making the platform more attractive to all parties. Yet, this advantage is only durable if MediaAlpha maintains its lead in data science, partner integration, and regulatory compliance. If competitors close the technology gap or offer more favorable terms, MediaAlpha could face pricing pressure or volume attrition.
What Sustained Innovation and Deeper Integration Could Unlock
If MediaAlpha continues its pace of partner integration and data science innovation, the platform could capture a growing share of the insurance digital acquisition market, especially as direct-to-consumer distribution expands and carriers demand more measurable ROI from their marketing spend. The most favorable scenario would see increasing transaction volume, improved pricing power via enhanced targeting, and higher partner retention driven by superior outcomes.
Evidence confirming this scenario would include: accelerating consumer referral growth above sector averages; expansion in high-value verticals like Medicare Advantage and life insurance; visible increases in partner wallet share; and public disclosures of new, multi-year integration agreements or exclusive partnerships. Margin expansion—driven by operating leverage and improved referral pricing—would further validate the upside thesis.
Falsification would occur if referral growth stalls, partner churn rises, or if new regulatory constraints materially limit data-driven targeting and pricing, eroding MediaAlpha’s differentiation.
Incremental Gains Amid Competitive and Regulatory Flux
The most plausible path is that MediaAlpha continues to benefit from secular digital migration in insurance distribution, but faces periodic headwinds from carrier ad budget volatility and competitive pressure. Referral volume would grow in line with overall online insurance shopping trends, but pricing and margins could fluctuate as partners test alternative channels or negotiate terms.
Continued investment in technology and compliance would support gradual improvement in targeting and partner value delivery, but operating leverage may be tempered by the need to reinvest in data infrastructure and regulatory adaptation. The new CFO’s ability to maintain financial discipline and continuity will be important, but the leadership transition may have minimal operational impact if core processes are robust.
Confirmation would come from steady referral and revenue growth, stable or improving partner retention rates (if disclosed), and evidence that MediaAlpha is maintaining or modestly expanding its share of key insurance verticals. A negative surprise would be a sudden drop in referral volume, loss of major partners, or regulatory actions materially impacting data usage.
Where Platform Vulnerability Meets External Shocks
MediaAlpha’s business could come under pressure if insurance carriers pull back on digital ad budgets in response to macroeconomic stress, sector profitability challenges, or regulatory uncertainty. In this scenario, referral volumes and transaction values would contract, and the company’s fee-based revenue would decline disproportionately due to high operating leverage.
Execution risk from the CFO transition could be amplified if it coincides with strategic missteps—such as underinvestment in technology, failure to keep pace with regulatory changes, or loss of key partner integrations. Intensifying competition could drive down referral fees or prompt partners to shift spend to rival platforms or direct channels.
Confirmation of this scenario would be a multi-quarter decline in consumer referrals, shrinking revenue, rising partner churn (if disclosed), or public evidence of major carriers or distributors exiting the platform. Regulatory actions restricting data collection, targeting, or fee structures would also signal downside risks.
Milestones and Metrics That Will Shape MediaAlpha’s Competitive Durability
Quarterly growth (or decline) in consumer referral volume relative to sector digital ad trends.
Changes in the number and concentration of active insurance partners—especially top carriers and distributors—on the platform.
Partner retention and churn metrics, if disclosed, to gauge stickiness and switching risk.
Gross profit per referral and operating margin trends, as indicators of pricing power and leverage.
Public disclosures of multi-year or exclusive integration agreements with key partners.
Evidence of successful adaptation to regulatory changes in data privacy or digital advertising.
Impact of the CFO transition on financial reporting quality, capital allocation, and strategic execution.
Expansion into new insurance verticals or geographies, which could diversify revenue and reduce concentration risk.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments