
Vertiv’s Backlog Surge: Navigating Demand, Delivery, and Competitive Complexity in Digital Infrastructure
Vertiv Holdings’ explosive backlog growth and robust Q3 performance underscore the surging global need for critical digital infrastructure—but the company’s future returns hinge on order realization, margin discipline, and its ability to manage operational risks amid intense competition and contractual constraints.
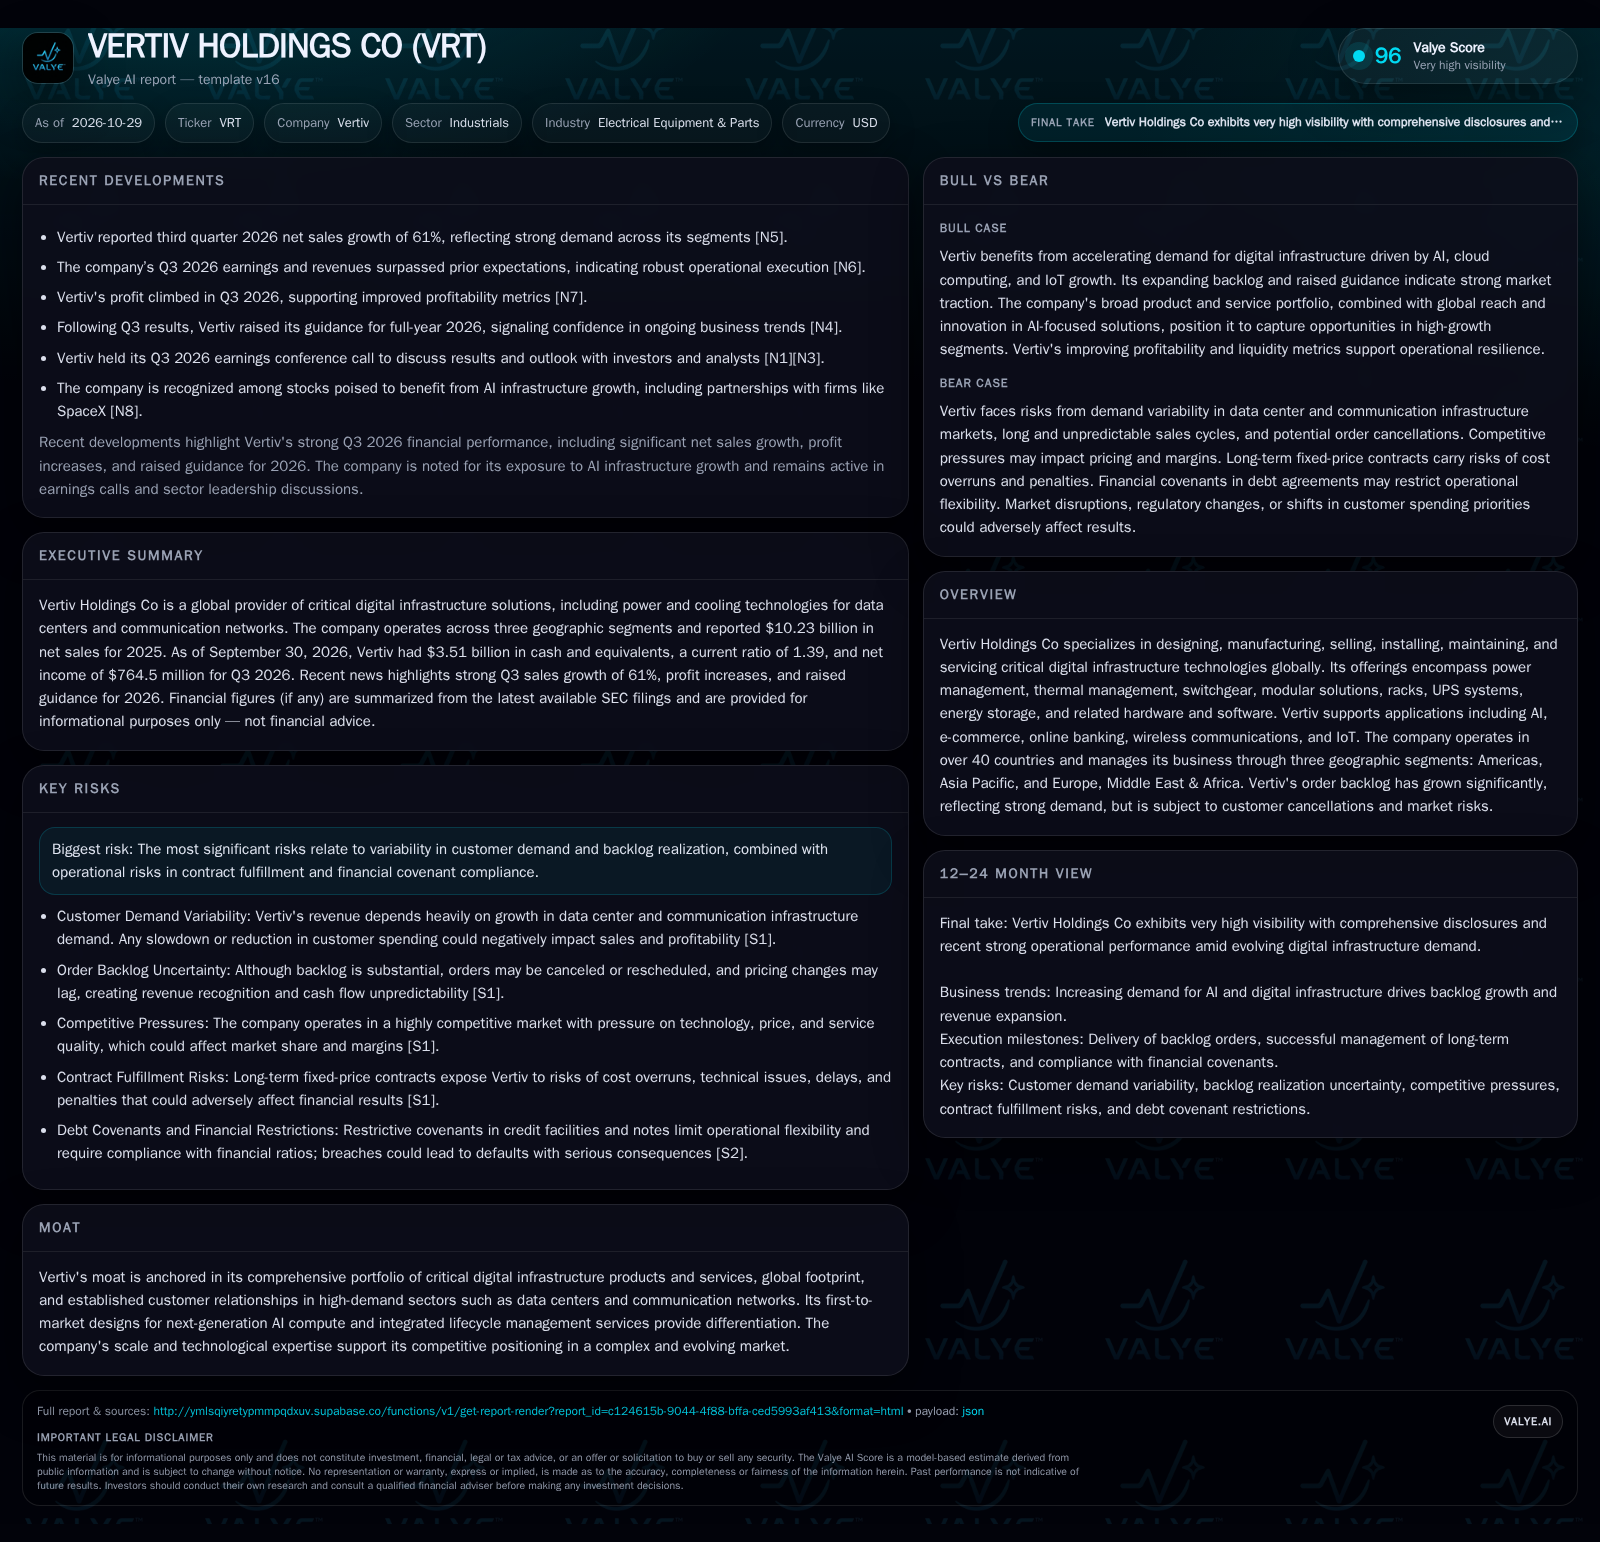
Vertiv Holdings reported a dramatic increase in order backlog and 61% Q3 sales growth, highlighting powerful demand tailwinds from AI and data center expansion. While elevated backlog and raised guidance support a bullish near-term outlook, the company faces significant risks from order volatility, contract execution, and competitive pricing. The next phase will test Vertiv’s ability to deliver on commitments and defend profitability as industry dynamics and customer priorities continue to evolve. [S1] [N4] [N5]
Vertiv Holdings is riding an unprecedented wave of demand for digital infrastructure, driven by the global proliferation of data centers, AI computing, and cloud services. The company’s Q3 2026 results—headlined by a 61% sales surge and sharply higher profits—have propelled expectations and nearly doubled its order backlog to $15 billion. Yet beneath these headline numbers lies a more complex reality: Vertiv’s future will be determined not just by how much business it books, but by its ability to deliver on those commitments, manage cost and execution risks, and defend its position in a fiercely competitive, rapidly evolving market. The next phase will test Vertiv’s operational resilience and strategic agility as much as its ability to ride the digital infrastructure boom.
Backlog Expansion and Record Sales: Vertiv’s Moment of Opportunity—and Challenge
Vertiv reported a dramatic increase in its order backlog to $15.0 billion at the end of 2025, up from $7.2 billion a year prior, with most of these commitments expected to ship over the next 12–18 months. This surge reflects a powerful uptick in global demand for critical digital infrastructure supporting AI, cloud, and communication networks. Q3 2026 net sales jumped 61%, with net income of $764.5 million, both exceeding expectations and prompting management to raise full-year guidance. However, the company acknowledges that backlog orders remain subject to cancellation or rescheduling, introducing an element of revenue and cash flow unpredictability. The immediate context is thus defined by exceptional top-line momentum, robust reported profitability, and an unusually high degree of order visibility—tempered by the inherent risks of large, complex project delivery and evolving customer priorities. [S1] [S2] [N4] [N5] [N6] [N7]
How Vertiv Monetizes the Digital Infrastructure Boom
Vertiv generates revenue through the sale, installation, and servicing of a broad array of power and thermal management products, modular solutions, software, and lifecycle services for data centers and communication networks. Its economics are shaped by a mix of high-value engineered systems, recurring service contracts, and, increasingly, integrated solutions for next-generation AI and hyperscale workloads. Pricing power is typically strongest for differentiated, mission-critical products with high switching costs, but the industry’s competitive intensity often limits margin expansion, especially in commoditized hardware segments.
The company’s revenue mix is geographically diversified, with the Americas contributing 62% of 2025 net sales, followed by Asia Pacific (20%) and EMEA (18%). The growing backlog suggests a favorable near-term volume outlook. However, many contracts—especially large, fixed-price, turnkey projects—introduce significant execution risk. Cost overruns, supply chain constraints, or technical setbacks can erode project-level profitability. Vertiv’s scale and broad portfolio should enable some operating leverage as volumes rise, but the extent of margin expansion will depend on the balance of project versus service revenue, the company’s ability to manage input costs, and its success in converting backlog without excessive concessions or penalties. [S1]
Defending Share in a Crowded, Innovation-Driven Market
Vertiv competes in a global market for critical digital infrastructure where barriers to entry are moderate but sustained leadership depends on technological innovation, reliability, and global service reach. Its peer set includes diversified electrical equipment giants, specialized data center solution providers, and emerging players targeting AI and edge computing deployments. The company’s moat rests on a comprehensive portfolio, integrated lifecycle services, and established relationships with major data center operators and telecommunications providers.
However, the sector is characterized by aggressive price competition, rapid technology cycles, and customer demands for ever-greater energy efficiency and scalability. Substitution risk is real, especially as hyperscale operators consider in-house solutions or shift toward modular, software-defined architectures. Vertiv’s ability to maintain share and pricing will depend on continued product innovation—especially for AI-ready cooling and power systems—and the company’s agility in customizing offerings for global and regional requirements. Scale advantages in procurement and service infrastructure provide some defense, but are not insurmountable for well-capitalized rivals.
Order Conversion Drives Sustained Growth and Margin Expansion
The most optimistic scenario sees Vertiv successfully converting its $15 billion backlog into revenue over the next 12–18 months, with minimal cancellations and strong incremental margins. This would be enabled by continued robust demand for data center and AI infrastructure, effective supply chain management, and project execution discipline. If the company can leverage its scale to negotiate favorable input costs and expand service and software revenue, operating leverage could drive outsized earnings growth.
Evidence supporting this scenario would include steady or rising backlog realization rates, increased service and software attach rates, and gross margin improvement even as volumes accelerate. Additional confirmation would come from new customer wins in AI and hyperscale verticals, positive customer references for execution, and the absence of major project delays or cost overruns.
Delivering on Commitments Amid Order Volatility and Margin Pressure
The most plausible trajectory is that Vertiv delivers the majority of its backlog as planned, but with a moderate rate of order rescheduling or cancellation and some margin compression as competitive pressures and project complexity rise. Demand for AI and cloud infrastructure remains strong but is subject to cyclical or regional pauses, and the mix of fixed-price contracts and service revenue leads to stable but only modestly expanding profitability.
This scenario would be confirmed by a backlog conversion rate broadly in line with historical averages, steady revenue growth, and gross margins that remain flat or improve only slightly despite higher sales volumes. Any uptick in project-related charges or customer concessions would reinforce the middle-of-the-road outcome. Monitoring the cadence of new order intake relative to backlog burn will also be critical to this scenario.
Backlog Attrition and Execution Stumbles Erode Momentum
An adverse scenario would play out if a meaningful portion of Vertiv’s backlog is delayed, rescheduled, or canceled—whether due to shifts in customer budgets, project reprioritization, or broader economic headwinds. Such an outcome would expose the company to revenue shortfalls, underutilized capacity, and potential working capital stress. Further, if fixed-price projects encounter significant cost overruns or delays, profitability could deteriorate sharply, potentially putting compliance with debt covenants at risk.
Evidence for this scenario would include a material reduction in backlog conversion rates, rising project write-downs, negative revisions to guidance, or warnings about covenant headroom. Increased customer concentration or exposure to distressed end-markets would heighten the risk. Any signal of tightening liquidity or new operational restrictions stemming from credit agreements would be a strong negative.
Milestones That Will Shape Vertiv’s Trajectory in the Digital Infrastructure Race
Quarterly backlog conversion rates: Tracking the percentage of backlog orders recognized as revenue each quarter would provide a direct read on demand realization and execution quality.
Gross margin trends: Sustained or improving gross margins as volumes rise would indicate effective cost management and pricing discipline in the face of competitive and input cost pressures.
Project-level loss or write-down disclosures: Any uptick in project cost overruns, penalties, or delays—if disclosed—would signal execution risk and margin vulnerability.
Service and software attach rates: The proportion of sales derived from higher-margin services and software, if disclosed, would test the thesis that Vertiv can move up the value chain.
Order cancellations or rescheduling: Monitoring the frequency and scale of order modifications would help assess backlog quality and revenue visibility.
Compliance with debt covenants: Updates on leverage ratios and covenant headroom would clarify operational flexibility and financial resilience.
Customer concentration and vertical mix: Shifts in exposure to hyperscale, AI, or regional data center customers could affect both opportunity and risk profiles.
New product launches or major customer wins: Announcements of next-generation offerings or large-scale deployments in AI/cloud verticals would validate Vertiv’s innovation edge and market relevance.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments