
Kustom Entertainment’s Twin-Engine Strategy: Video Tech Meets Ticketing Ambition Amid Capital and Execution Pressures
With a recent exit from healthcare, Kustom Entertainment now leans on patented law enforcement video systems and the TicketSmarter ticketing platform.
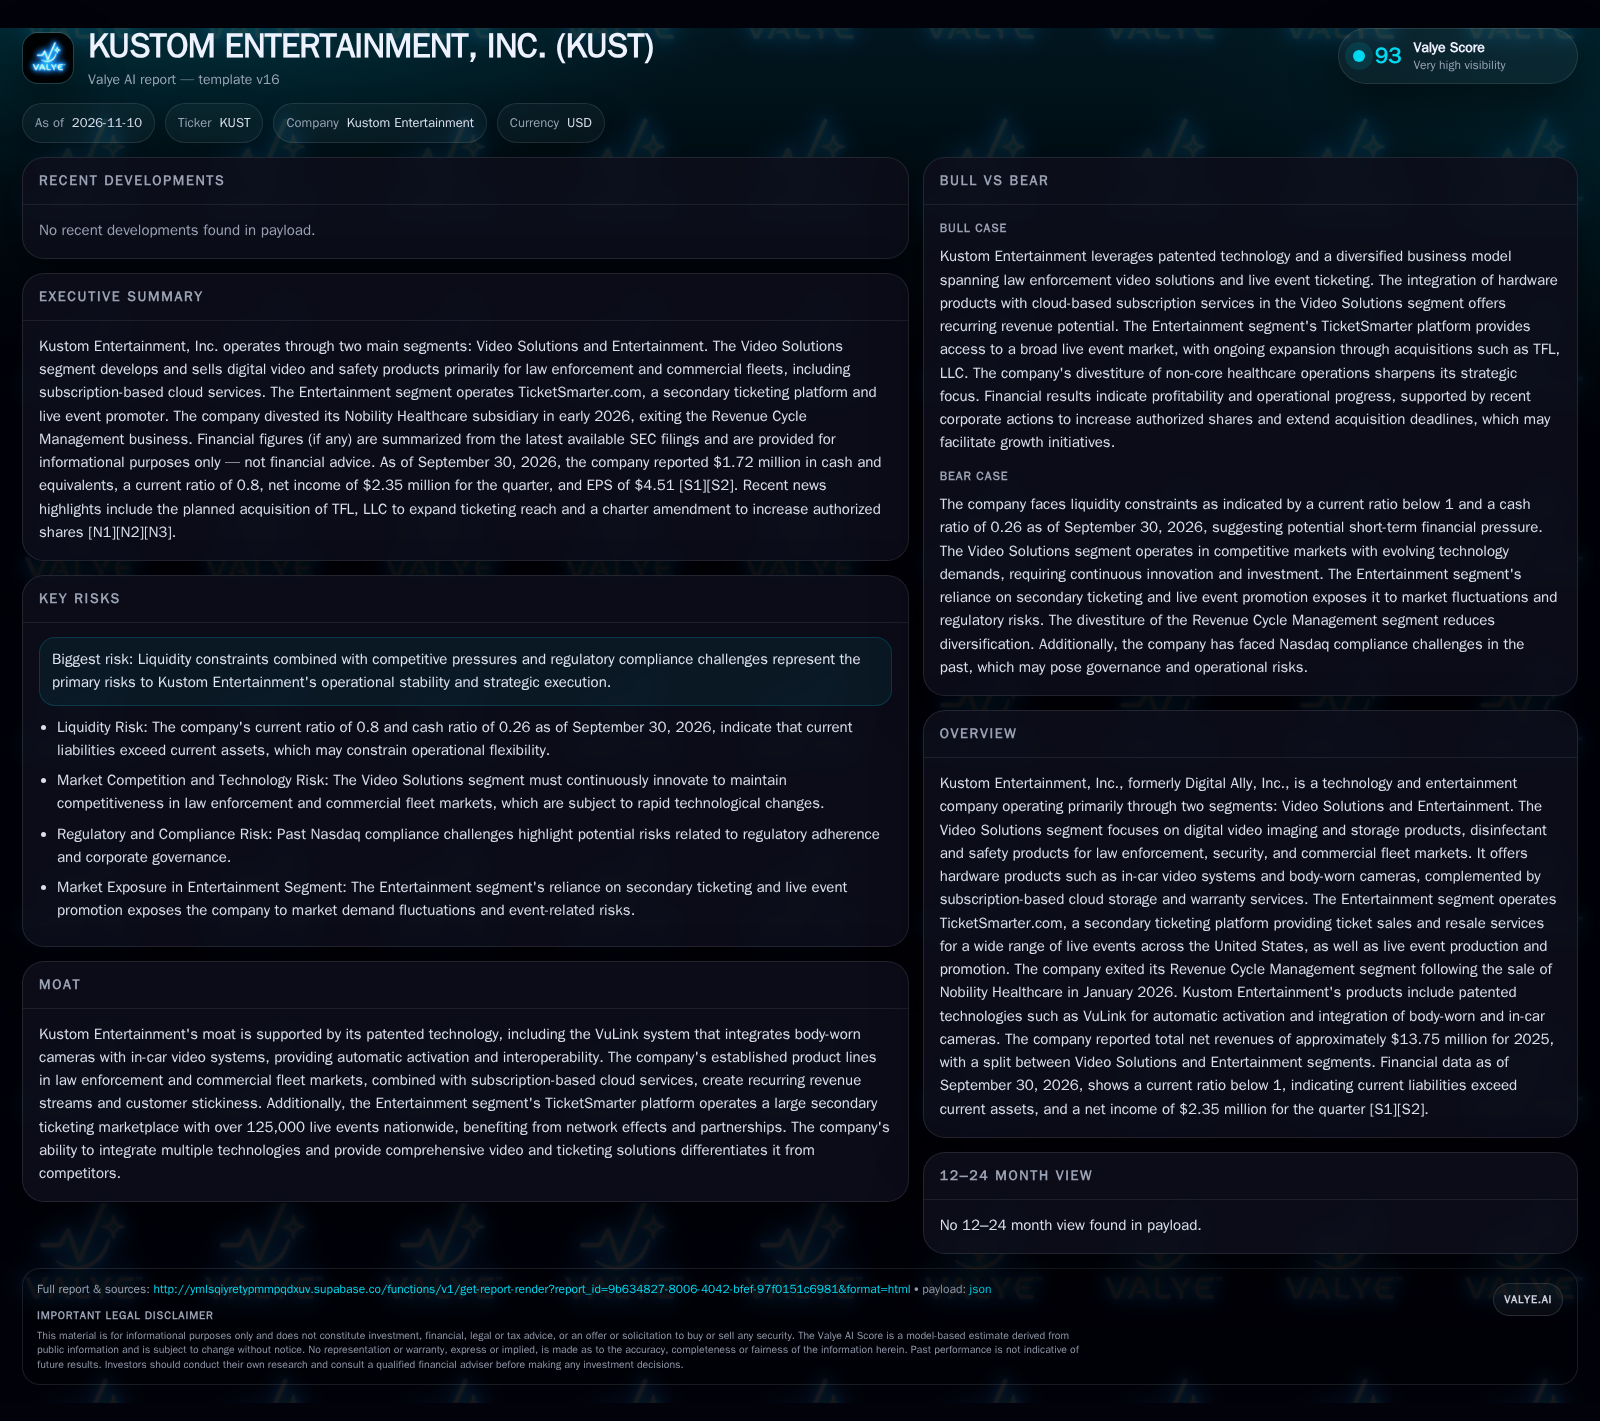
Kustom Entertainment, Inc. has repositioned itself as a focused two-segment business: Video Solutions (digital video and safety systems for law enforcement and fleets) and Entertainment (TicketSmarter ticketing platform and live event promotion). The company posted net income of $2.35 million for Q3 2026 despite a current ratio of 0.8, signaling short-term liquidity pressure. Expansion hinges on the planned TFL, LLC acquisition and scaling recurring revenue from both segments, but execution risk and capital needs are pronounced. The next phase will test whether Kustom’s strategic refocus can overcome structural and market headwinds. [S1] [S2] [N1] [N2] [N3] [N5]
Kustom Entertainment, Inc. has undergone a significant transformation in 2026, shedding its healthcare operations to concentrate on two distinct businesses: digital video solutions for public safety and commercial fleets, and the TicketSmarter secondary ticketing platform for live events. This sharper focus is accompanied by both opportunity and risk. With the TFL, LLC acquisition on the horizon and a recent move to increase authorized shares, Kustom’s next act will depend on its ability to execute in highly competitive and capital-intensive markets.
Recent Corporate Actions Signal Strategic Refocus and Capital Needs
Kustom Entertainment, Inc. has streamlined its operations, completing the divestiture of its Nobility Healthcare subsidiary in January 2026, thereby exiting the Revenue Cycle Management segment and narrowing its focus to Video Solutions and Entertainment. This move is designed to sharpen the company’s strategic direction and align resources with its core competencies. [S1] [N5]
As of September 30, 2026, the company reported $1.72 million in cash and equivalents, with current liabilities of $6.51 million, resulting in a current ratio of 0.8 and a cash ratio of 0.26. [S2]
Net income for the same quarter was $2.35 million, with basic and diluted EPS of $4.51, suggesting recent operational profitability. However, it is unclear if this performance is sustainable given the stated capital constraints and the lumpy nature of event-driven and hardware sales. [S2]
The company has extended the deadline for its planned acquisition of TFL, LLC (now set for December 18, 2026) and filed a charter amendment to increase authorized shares to 1.2 billion, actions that collectively point to ongoing acquisition ambitions and possible preparation for future equity or convertible financing. [N1] [N2] [N3]
How Kustom’s Dual Segments Could Unlock Revenue and Margin Expansion
Kustom Entertainment’s economics hinge on two distinct but complementary models: hardware-plus-subscription in Video Solutions, and transaction-based plus inventory-driven ticketing in Entertainment. The Video Solutions segment generates revenue from the sale of in-car video systems, body-worn cameras, and related hardware, with additional recurring revenue from subscription-based cloud storage and extended warranties. This blend offers the potential for higher gross margins and improved revenue predictability, provided hardware sales can drive sufficient installed base for subscription attachment. However, the segment’s sales are typically project-driven and subject to procurement cycles in public safety and fleet verticals, which can result in revenue lumpiness and working capital swings.
The Entertainment segment, anchored by TicketSmarter.com, earns revenue via service charges on ticket sales, resale spreads, and company-held ticket inventory. In secondary ticketing, margins are generally low to mid-single digits on gross transaction value, but scale and technology integration can yield meaningful operating leverage. The segment’s economics are sensitive to event volume, consumer demand, and inventory risk, with the additional complication of regulatory scrutiny in some jurisdictions. Live event production and promotion activities can be high risk/reward, with potentially significant upfront costs and variable returns.
Both segments require ongoing investment: Video Solutions to fund R&D and maintain patent-driven differentiation, and Entertainment to secure event inventory, marketing, and platform technology.
Defensibility and Threats in Law Enforcement Tech and Ticketing Platforms
In Video Solutions, Kustom’s primary differentiator is its patented VuLink technology, which enables automatic activation and integration of body-worn and in-car cameras—a feature valued by law enforcement and commercial fleets for compliance and evidentiary integrity. However, this market is highly competitive, with established players and new entrants continuously innovating in areas such as AI-driven analytics, cloud-native platforms, and seamless device interoperability. The need for continuous R&D investment is a persistent barrier to maintaining technological leadership.
TicketSmarter operates in the crowded and price-sensitive secondary ticketing ecosystem, where network effects, inventory access, and brand trust are crucial. Larger rivals may enjoy superior event partnerships, marketing budgets, and technology stacks, making it challenging for smaller platforms to achieve durable differentiation. Kustom’s planned TFL, LLC acquisition could expand its event inventory and customer reach, but integration and execution risks remain. Regulatory scrutiny of ticketing practices and consumer protection is an additional headwind for all players in this space.
While Kustom’s dual-segment approach offers some diversification, it also dilutes focus and may limit the company’s ability to build a true moat in either business unless synergies—such as shared data infrastructure or cross-segment customer engagement—can be realized.
If Recurring Revenue and Ticketing Scale Outpace Capital Constraints
A favorable outcome for Kustom would see the Video Solutions segment successfully leveraging its installed hardware base to drive high-margin, recurring subscription revenue for cloud storage and digital evidence management. If law enforcement and commercial fleet customers increase adoption of integrated camera systems—motivated by regulatory mandates or liability reduction—the company could achieve greater revenue predictability and customer stickiness.
Simultaneously, if the TicketSmarter platform and the pending TFL, LLC acquisition significantly boost event inventory and consumer traffic, Kustom could benefit from network effects and operating leverage, improving both top-line growth and segment margins. Strategic partnerships or technology enhancements that differentiate TicketSmarter from larger incumbents would further support this scenario.
Evidence supporting this path would include sustained growth in deferred revenue (if disclosed), rising subscription attachment rates, event-driven revenue spikes, and improved gross margins in both segments. Demonstrated ability to raise capital on favorable terms or generate positive free cash flow would confirm the company’s capacity to fund expansion and innovation.
Sustained Profitability Depends on Execution and Capital Access
The most plausible outcome is that Kustom sustains modest profitability, with Video Solutions delivering steady but uneven sales cycles and the Entertainment segment capturing incremental ticketing volume through organic growth and the TFL, LLC acquisition. Recurring revenue from cloud and warranty subscriptions provides margin ballast, but growth is capped by hardware sales velocity and customer procurement cycles.
TicketSmarter’s performance remains tied to the health of the live events market and its ability to secure desirable event inventory. Without a step-change in scale or differentiation, the platform may struggle to meaningfully close the gap with larger rivals. Execution risk in integrating acquisitions and managing working capital remains high.
Liquidity Pressures and Execution Missteps Could Trigger Strategic Retreat
A negative scenario would see liquidity pressures intensify, forcing Kustom to curtail investment in product development, event inventory, or marketing, thereby eroding competitive position in both segments. If Video Solutions fails to keep pace with technological change or loses key procurement cycles, hardware sales and subsequent subscription revenue could stagnate or decline.
In Entertainment, underperformance of TicketSmarter—due to weak event demand, regulatory changes, or inability to secure attractive inventory—could lead to revenue shortfalls and increased marketing spend with diminishing returns. Integration challenges or failure to close the TFL, LLC acquisition on favorable terms would further strain resources.
Confirmation would include deteriorating cash and current ratios, missed debt or payment obligations (if disclosed), declining revenue or segment contribution, or the need to divest additional assets or seek distressed financing. Extended periods of negative operating cash flow or loss of Nasdaq compliance could force a strategic retrenchment or sale of core assets.
Signals That Will Clarify Whether Kustom’s Refocus Can Deliver Sustainable Growth
Subscription attachment rate and deferred revenue growth in the Video Solutions segment—if disclosed—would clarify the trajectory of recurring revenue and customer stickiness.
Gross margin trends across both segments, particularly the contribution of high-margin subscription and service revenues versus hardware or ticket inventory sales.
Quarterly cash flow from operations and changes in net cash position, to assess whether the company is internally funding its growth or increasingly reliant on external capital.
Progress and final terms of the TFL, LLC acquisition, including integration milestones and any disclosed revenue or customer base expansion.
TicketSmarter’s event inventory scale and ticketing volume growth, especially in relation to new partnerships or exclusive event access.
R&D and marketing spend as a percentage of segment revenue, indicating management’s willingness and ability to invest in innovation and customer acquisition.
Any updates on regulatory or legal developments affecting secondary ticketing or law enforcement procurement, which could materially alter addressable markets or cost structures.
Changes in authorized share usage or new equity/debt financings, which would impact dilution risk and signal underlying capital needs.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments