
Lion Copper & Gold: Project Funding, Exploration Progress, and the Realities of Junior Mining Economics
Lion Copper & Gold Corp. is advancing a portfolio of copper and gold projects, including the recently funded Yerington property, while navigating the sector’s inherent capital intensity and commodity risks. The company’s modest net income and liquidity position signal operational progress but also highlight the financial pressures typical for explorers at this stage.
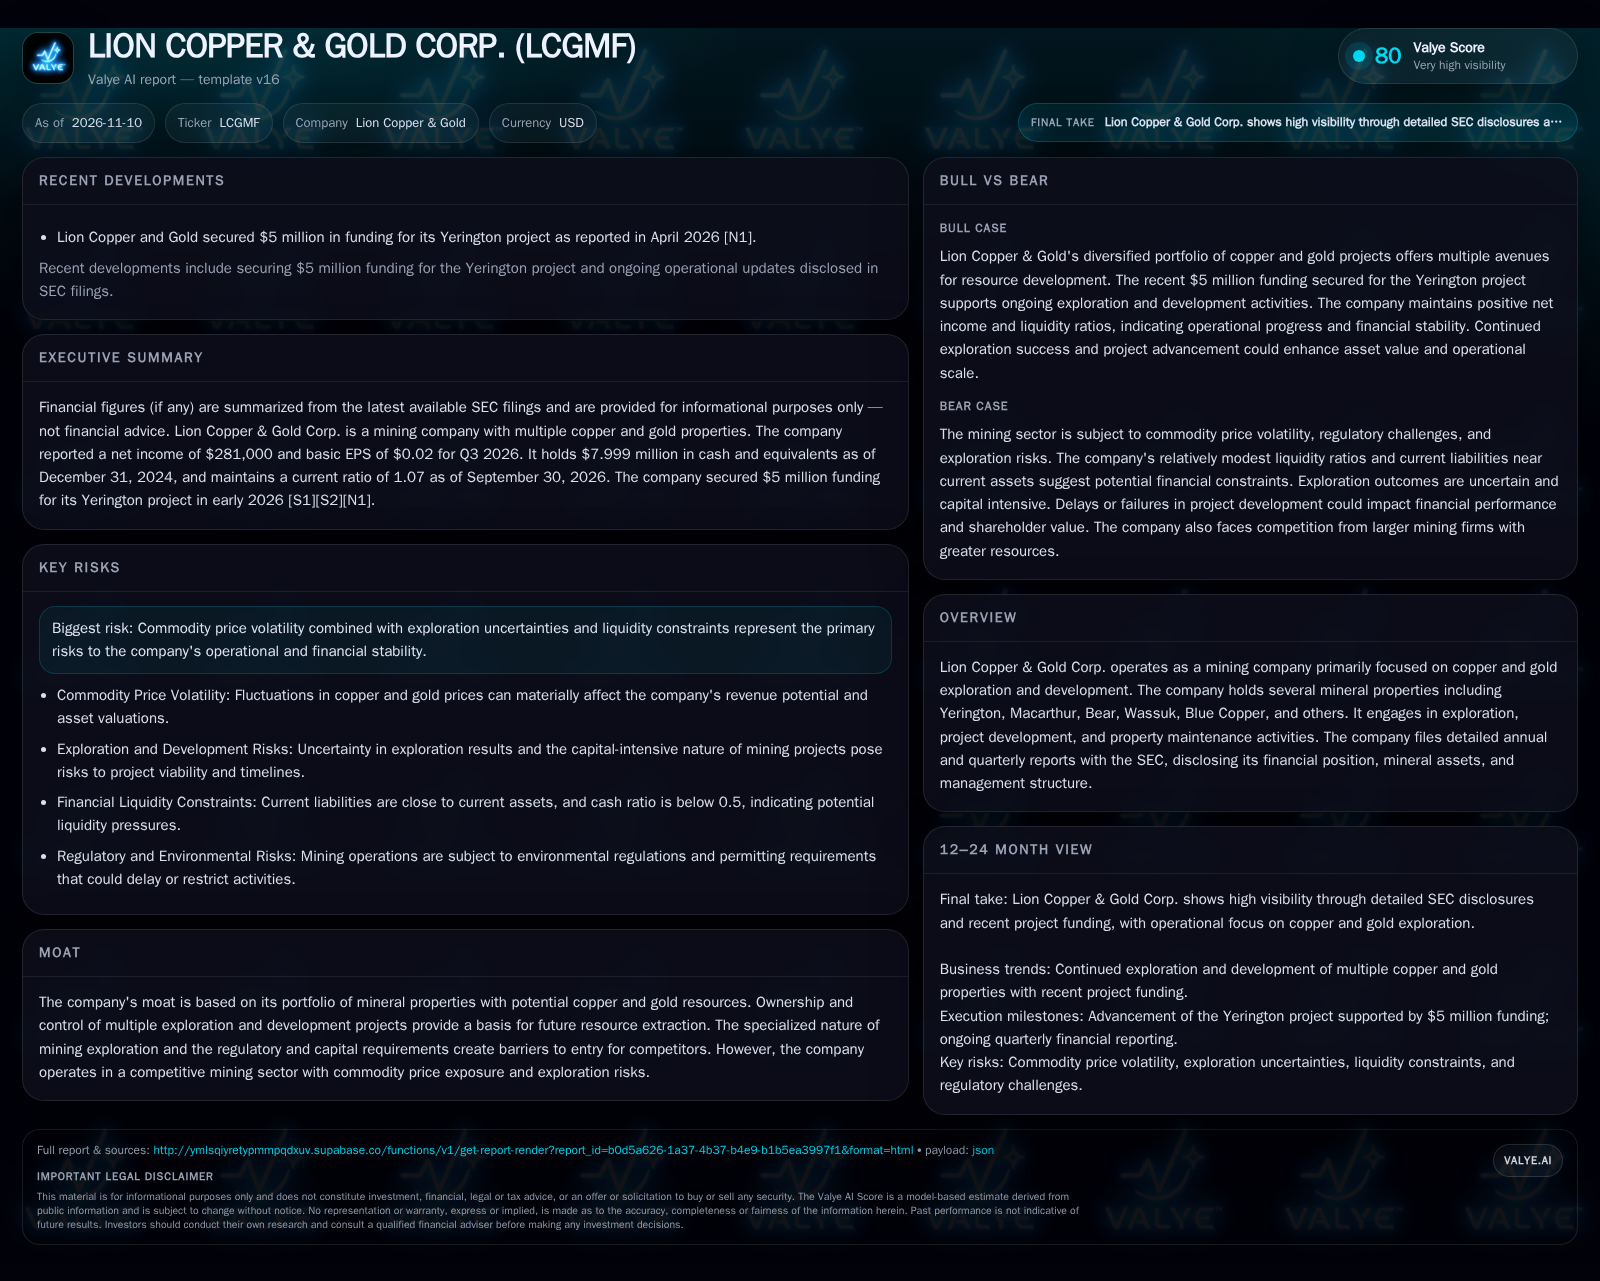
Lion Copper & Gold Corp. reported a small net income for Q3 2026 and holds a portfolio of copper and gold assets. The company secured $5 million in funding for its Yerington project, supporting ongoing exploration and development. Commodity price volatility and exploration risks remain central challenges for the company’s business model.[S2]
In a sector where project timelines, exploration outcomes, and commodity prices are often unpredictable, the next phase of Lion Copper & Gold’s journey hinges on translating project funding into tangible resource advancement and maintaining access to capital as development needs escalate.
Recent Funding and Financial Position Define the Near-Term Operating Landscape
Lion Copper & Gold Corp. reported net income of $281,000 and basic earnings per share of $0.02 for the quarter ended September 30, 2026, reflecting operational progress in a sector where early-stage companies often post losses. The company holds $7.999 million in cash and cash equivalents, with total current assets of $21.246 million and current liabilities of $19.836 million, resulting in a current ratio of 1.07 and a cash ratio of 0.44. These metrics indicate that while the company is meeting its short-term obligations, liquidity is tight and will require careful management as development spending increases. The $5 million in dedicated funding for the Yerington project, announced in April 2026, provides a near-term catalyst for resource advancement but underscores ongoing dependence on external capital to progress projects beyond the exploration phase. [S2]
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. This tight liquidity scenario necessitates a rigorous prioritization of exploration activities, focusing capital deployment on targets with the highest probability of resource delineation and economic viability. Additionally, maintaining investor confidence through transparent communication of progress and risk management becomes critical to facilitate timely access to follow-on funding. The interplay between cash management and exploration pacing will likely dictate the company’s ability to sustain momentum without resorting to dilutive financing under distressed conditions.
Mining Project Economics: Capital Intensity, Exploration Uncertainty, and Future Cash Flow Potential
Lion Copper & Gold’s business model is fundamentally shaped by the capital-intensive nature of mineral exploration and development. Early-stage project spending is dominated by exploration drilling, permitting, environmental studies, and technical evaluations, with little or no operating revenue until a property is de-risked and moves toward production. The company’s recent net income is notable but does not yet reflect recurring operational cash flow, as mining projects typically require years of investment before cash generation begins.
Revenue potential is highly sensitive to resource delineation success, project advancement, and ultimately, commodity prices. Should the company advance any property to production, unit economics would depend on ore grades, extraction costs, and prevailing copper and gold prices. Fixed costs are significant in the exploration and permitting phases, but potential operating leverage emerges as projects scale and throughput increases. Conversely, capital needs may escalate sharply if the company moves beyond exploration to construction or production, likely requiring additional equity or debt financing. Absent clear commercial arrangements or offtake contracts, future revenue timing and magnitude remain speculative at this stage.
The capital intensity inherent in mining exploration creates a cash flow profile characterized by extended periods of negative operating cash flow, followed by potential inflection points if a project advances to production. This dynamic underscores the importance of milestone-based capital deployment, where each phase of exploration or development is contingent on achieving defined technical or regulatory benchmarks. Such an approach can optimize capital efficiency and reduce risk exposure. Moreover, the sensitivity of project economics to commodity price fluctuations implies that the timing of project advancement decisions must consider macroeconomic and market cycles, as premature investment during price troughs can erode project returns and shareholder value.
Another critical consideration is the scalability of project infrastructure and its impact on unit costs. Early exploration phases often incur high per-unit costs due to limited throughput and the need for extensive geotechnical studies. However, as projects transition toward production, economies of scale and operational efficiencies can materially improve margins. This potential operating leverage is conditional on successful resource expansion and the ability to secure infrastructure access, such as transportation and power. Conversely, failure to scale efficiently or unforeseen technical challenges can lead to cost overruns, compressing margins and complicating financing efforts.
Asset Portfolio and Sector Structure: Barriers, Substitutes, and Peer Dynamics
Lion Copper & Gold’s competitive positioning rests on its control of multiple mineral properties, including the Yerington, Macarthur, Bear, Wassuk, and Blue Copper projects. In mining, the principal moat arises from property ownership, permitting progress, and resource potential, as well as management’s technical and financial execution. The company operates in a sector crowded with both junior explorers and established producers, many of which have significantly greater financial and technical resources.
Barriers to entry in mining include the high cost and complexity of exploration, regulatory and environmental permitting requirements, and the need for sustained capital access. However, competition for investor capital and project partners is intense, particularly when commodity prices are volatile. Substitution risk is tied not to direct product alternatives but to investor reallocation toward projects with higher resource confidence, lower costs, or better infrastructure access. The company’s ability to advance projects to defined resources or preliminary economic assessments would strengthen its negotiating position with potential partners or acquirers.
Catalyzing Value: Exploration Success and Project Advancements Unlock Re-Rating Potential
A favorable scenario for Lion Copper & Gold would see the recent $5 million funding drive successful exploration and resource delineation at the Yerington project, potentially resulting in a maiden resource estimate or a positive preliminary economic assessment. Such milestones could validate the technical and economic viability of the property, attract additional investment, and support a rerating of the company’s asset base. If commodity prices for copper and gold remain robust, the net present value of the company’s projects could increase substantially, incentivizing strategic partnerships or acquisition interest from larger mining firms.
Confirmation of this scenario would be evident in the release of positive drilling results, resource upgrades, or technical studies, followed by new funding rounds or joint venture agreements. Conversely, failure to deliver material exploration progress or to secure follow-on capital would quickly falsify the bullish thesis.
Progression Through Milestones Amid Tight Capital: The Most Plausible Trajectory
The most likely path for Lion Copper & Gold is incremental project advancement at Yerington and other properties, funded by the recent capital infusion but constrained by the company’s reported liquidity position. Exploration programs may yield resource updates, but project timelines could extend as the company balances technical progress against cash burn. The base case assumes no immediate transition to construction or production, but continued efforts to de-risk assets and attract additional investment or partnerships.
Failure to secure new funding, or significant adverse exploration outcomes, would challenge this scenario.
Liquidity Pressures and Exploration Disappointment: How Value Could Erode
In a negative scenario, exploration at Yerington or other properties fails to yield promising results, leading to a lack of resource upgrades or technical de-risking. The company’s reported cash balance and current liabilities would then force difficult choices: scaling back exploration, diluting shareholders through distressed equity issuance, or even mothballing projects. Weak copper and gold prices would exacerbate these pressures, further undermining asset valuations and investor appetite.
Confirmation of this downside would include disappointing drill results, sharply reduced exploration budgets, or unfavorable financing terms. An inability to maintain even minimal liquidity or to meet regulatory commitments could force asset sales or strategic retrenchment.
Milestones and Market Forces That Will Shape Lion Copper & Gold’s Next Phase
Progress and results from Yerington project exploration programs, including any resource definition or technical study announcements.
Disclosure of additional funding events, partnership agreements, or joint ventures that extend the company’s capital runway.
Commodity price trends for copper and gold, as these directly impact project economics and investor interest.
Permitting and regulatory developments affecting Yerington or other core assets.
Updates on exploration or development activity at non-Yerington properties, to gauge portfolio breadth and optionality.
If disclosed, operating cash burn rate and projected capital expenditures, to calibrate funding needs and timeline risk.
Announcements of resource upgrades, preliminary economic assessments, or feasibility studies that could re-rate asset value.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments